
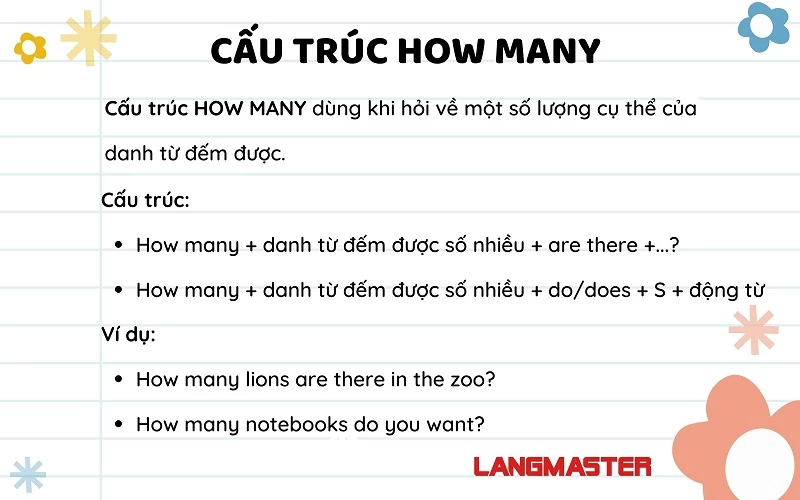
The deceptively simple question, “How much was that?”, often triggers a mere recall of a price tag. Yet, in the complex tapestry of personal finance, the true answer extends far beyond the number on a receipt. It encompasses a spectrum of hidden costs, missed opportunities, and the profound long-term implications of our financial decisions. Understanding the full scope of “how much was that” is fundamental to achieving financial clarity, mastering our money, and building a secure future. This exploration delves into the layers beneath the surface price, dissecting the unseen financial burdens, the true value of expenditures, and the strategic approaches to ensure every dollar spent or invested serves a meaningful purpose.
The Unseen Costs: Decoding Your Spending Habits
Many of us operate under the illusion that we have a firm grasp on our finances, only to be surprised by an empty bank account at the end of the month. This disconnect often stems from a failure to recognize the cumulative impact of what appear to be insignificant expenditures. The real “how much was that” often includes a multitude of small, almost invisible drains on our resources.
The Micro-Expense Avalanche
Consider the daily coffee, the impromptu lunch, the snack from the vending machine, or the impulse purchase at the grocery checkout. Individually, these items seem negligible—a few dollars here, a few dollars there. However, aggregated over weeks, months, or years, they form a formidable “micro-expense avalanche” that can significantly derail financial goals. A $5 daily coffee translates to $150 a month, or $1,800 annually. This money, seemingly inconsequential in isolation, could instead fund an emergency savings account, contribute to an investment portfolio, or pay down high-interest debt. The challenge lies in acknowledging that these small decisions are, in fact, significant financial commitments when viewed collectively.
Subscription Overload Syndrome
In the age of digital convenience, subscription services have proliferated, offering everything from streaming entertainment and fitness apps to software and meal kits. While each subscription might offer value, the cumulative cost can be staggering. Many individuals unknowingly pay for services they rarely use or have forgotten about entirely. This “subscription overload syndrome” is a classic example of hidden costs. A streaming service at $15 a month, a gym membership at $40, a productivity app at $10—these quickly add up to hundreds of dollars annually, often unnoticed because they are automatically deducted. Regularly auditing and canceling dormant subscriptions can reveal substantial savings, giving a clearer answer to “how much was that” for digital conveniences.
Lifestyle Creep and Its Consequences
As income rises, so too often does our spending. This phenomenon, known as lifestyle creep, involves incrementally upgrading our living standards with each raise or bonus. What once felt like a luxury—eating out more often, buying designer clothes, or opting for premium services—gradually becomes the new normal. The danger of lifestyle creep is that it erodes the financial benefits of increased income, making it difficult to save or invest more. Instead of feeling wealthier, individuals find their discretionary income remains stagnant, or even diminishes, as their expenses expand to fill their earnings. Understanding “how much was that” in the context of lifestyle creep means evaluating whether upgraded spending genuinely enhances well-being or simply traps us in a cycle of ever-increasing financial demands.
Beyond the Sticker Price: Understanding True Financial Impact
The initial price tag is just one dimension of an item’s true cost. To accurately answer “how much was that,” we must look deeper, considering the broader financial implications, both immediate and long-term. This involves evaluating opportunity costs, hidden fees, maintenance expenses, and the ultimate value derived from a purchase.
The Opportunity Cost of Every Purchase
Every dollar spent on one item is a dollar that cannot be spent or invested elsewhere. This is the essence of opportunity cost. When you purchase a new gadget, the “cost” is not just its price, but also what you could have done with that money instead—investing it for future growth, paying down high-interest debt, or saving for a down payment on a home. Understanding opportunity cost forces a critical evaluation of priorities. Is the immediate gratification of a new purchase worth sacrificing a future financial goal? This perspective shifts the question from simply “how much money did I spend?” to “what potential financial benefit did I forgo by making this choice?”
Depreciation, Maintenance, and Hidden Fees
Many assets come with significant ongoing costs that are not reflected in the initial purchase price. A new car, for example, not only depreciates rapidly but also incurs expenses for insurance, fuel, maintenance, repairs, and registration. Similarly, a new home comes with property taxes, utilities, insurance, and potential repair costs. Even smaller purchases can have hidden fees; credit card interest, ATM fees, or expedited shipping charges can inflate the true cost of an item. To truly answer “how much was that,” one must factor in these supplementary expenses over the lifespan of the item, revealing a much higher figure than initially perceived.
The Value Versus Cost Conundrum
Not all expenses are created equal. Some high-cost items can offer substantial long-term value, while inexpensive ones might prove to be poor investments. The “value versus cost” conundrum encourages a holistic view. Buying a high-quality, durable appliance might cost more upfront but could save money on repairs and replacements over time. Investing in education or professional development might carry a hefty price tag, but the increased earning potential and career advancement could yield significant returns. Conversely, repeatedly purchasing cheap, low-quality goods might seem cost-effective initially but often leads to premature failure and higher replacement costs. True financial literacy requires discerning when an expense is a wise investment in value and when it is merely a drain on resources.
Mastering Your Money: Strategies for Financial Awareness
Moving beyond passively observing where money goes, mastering your finances requires active engagement and strategic implementation. The goal is to move from asking “how much was that?” in retrospect, to knowing the answer proactively and intentionally.
The Power of Budgeting and Tracking
The cornerstone of financial awareness is a robust budgeting system. A budget is not merely a restriction; it’s a roadmap for your money, allocating every dollar to a specific purpose. By categorizing income and expenses, individuals gain unparalleled insight into their spending patterns. Tools ranging from simple spreadsheets to sophisticated budgeting apps can facilitate this process. Equally important is diligent expense tracking. Manually reviewing bank statements, using budgeting software, or linking accounts to financial aggregators allows for real-time monitoring of expenditures. This consistent oversight transforms the vague question “how much was that?” into a precise understanding of where every penny goes, empowering individuals to identify areas for adjustment and savings.
Embracing Mindful Consumption
Beyond the numbers, cultivating a mindset of mindful consumption is crucial. This involves pausing before a purchase and asking critical questions: Do I truly need this? Does it align with my values and financial goals? Can I achieve the same outcome differently or more affordably? Mindful consumption encourages delaying gratification, differentiating between wants and needs, and resisting the pervasive pressures of consumerism. It’s about making conscious choices that reflect an understanding of the true cost—financial, environmental, and personal—of every purchase. This practice helps individuals move from reactive spending to intentional resource allocation, ensuring that “how much was that” always leads to a justifiable answer.
Leveraging Financial Technology
The digital age offers an array of powerful tools to enhance financial awareness and management. Budgeting apps like Mint, YNAB (You Need A Budget), or Personal Capital automate expense tracking, categorize transactions, and provide visual insights into spending habits. Investment platforms offer user-friendly interfaces for managing portfolios, while robo-advisors make investing accessible even for beginners. Automated savings tools can funnel small, regular amounts into savings or investment accounts without requiring constant vigilance. By leveraging these technologies, individuals can streamline financial processes, gain deeper insights into their “how much was that” questions, and automate their journey towards financial goals, making money management more efficient and less burdensome.
Investing in Tomorrow: When “Expensive” Becomes an Asset
Not all high costs are detrimental. In fact, some of the most significant expenditures can be the most valuable investments, yielding substantial returns over time. Differentiating between a wasteful expense and a strategic investment is key to answering “how much was that?” with an eye towards long-term prosperity.
Education, Skills, and Personal Growth
Investing in oneself through education, skill development, or personal growth initiatives can be among the most financially rewarding decisions. While tuition, courses, or certifications might seem expensive upfront, they can significantly enhance earning potential, career advancement, and job security. A specialized degree, a professional certification, or even a workshop to develop a high-demand skill can unlock new opportunities and a higher income trajectory, making the initial outlay a powerful long-term asset. The question “how much was that?” for education becomes less about the immediate dollar figure and more about the return on human capital.
Quality Over Quantity: Durable Goods and Services
Sometimes, paying more upfront for a higher-quality product or service can be a prudent financial decision. Investing in durable goods, such as well-made furniture, reliable appliances, or efficient vehicles, often results in lower maintenance costs, fewer replacements, and a longer lifespan, ultimately saving money over time. Similarly, choosing a reputable service provider, even if slightly more expensive, can prevent costly mistakes or subpar results down the line. The initial “how much was that?” might be higher, but the total cost of ownership over the product’s life or the service’s efficacy makes it a superior financial choice.
Strategic Investments for Long-Term Wealth
The most direct answer to “how much was that?” when it comes to building wealth is through strategic investments. Allocating capital to stocks, bonds, real estate, or other investment vehicles, while requiring an initial outlay, is designed to generate future income or capital appreciation. While the immediate “cost” is the amount invested, the long-term perspective reveals the potential for compound growth, outpacing inflation and building substantial wealth over decades. This involves understanding risk, diversification, and aligning investments with long-term financial goals, such as retirement planning, buying a home, or funding education. In these instances, “how much was that?” is not a question of an expense but a foundational step towards financial freedom.
Ultimately, “How much was that?” transcends a simple monetary figure. It is an invitation to deeply analyze our financial choices, understand their ripple effects, and make informed decisions that align with our values and long-term aspirations. By embracing financial awareness, strategic spending, and mindful investing, we transform this basic question into a powerful tool for building a more secure and prosperous financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.