
The S&P 500 is widely regarded as the most accurate barometer of the United States stock market and, by extension, the health of the broader economy. Comprising 500 of the largest publicly traded companies in the U.S., its performance is a critical metric for institutional investors, pension funds, and individual retail traders alike. When investors ask, “How much is the S&P 500 up year to date?” they are seeking more than just a percentage; they are looking for a narrative that explains the current state of global finance, the trajectory of corporate earnings, and the effectiveness of monetary policy. Understanding the year-to-date (YTD) performance requires a deep dive into the macroeconomic catalysts, sector-specific movements, and historical context that define the current market cycle.
Analyzing the Current Year-to-Date Performance
The year-to-date performance of the S&P 500 is a moving target, reflecting the daily ebb and flow of investor sentiment, economic data releases, and geopolitical events. To understand where the index stands today, one must first look at the momentum carried over from the previous calendar year. Often, a strong YTD performance is the result of a “soft landing” narrative—the idea that the Federal Reserve can successfully curb inflation without triggering a significant recession.
The Significance of the YTD Metric
Year-to-date performance is a standardized measure used to evaluate the return on an investment from the first trading day of the current calendar year to the current date. For the S&P 500, this figure provides a snapshot of how the equity market is responding to the year’s unique challenges. A positive YTD return suggests investor confidence and robust corporate profitability, while a negative or stagnant return may signal underlying economic fragility or overvaluation. Professional money managers use this metric to benchmark their portfolios, often striving to “beat the S&P” to justify their management fees.
Market Capitalization and Index Weighting
It is essential to recognize that the S&P 500 is a market-capitalization-weighted index. This means that the largest companies—such as Microsoft, Apple, NVIDIA, and Amazon—have a disproportionate impact on the index’s YTD performance. In recent periods, a phenomenon known as “market concentration” has become a central theme. Often, the YTD gains are driven heavily by a handful of mega-cap technology stocks, sometimes referred to as the “Magnificent Seven.” Consequently, while the headline YTD figure might show a double-digit gain, the “equal-weighted” version of the index might show much more modest growth, indicating that the rally is not necessarily broad-based.
Primary Drivers of the Market Rally
Several core factors dictate why the S&P 500 moves the way it does in any given year. For the current YTD period, the narrative has been dominated by three main pillars: the revolution in Artificial Intelligence (AI), the stabilization of inflation, and the shifting expectations regarding interest rate cuts.
The Artificial Intelligence Boom
Technology remains the primary engine of growth for the S&P 500. The rapid integration of generative AI across various industries has led to a massive revaluation of tech companies. NVIDIA, for instance, has seen its valuation skyrocket as demand for high-performance chips exceeds supply. This enthusiasm has a halo effect on the entire index. Investors are no longer just looking at current earnings; they are pricing in a future where AI significantly enhances productivity and profit margins across the software, hardware, and service sectors.
Monetary Policy and the Federal Reserve
The Federal Reserve’s stance on interest rates is perhaps the single most influential factor on YTD performance. When inflation began to cool from its 2022 peaks, the market started pricing in a transition from a “hawkish” stance (raising rates) to a “dovish” stance (cutting or maintaining rates). Lower interest rates are generally bullish for stocks because they reduce the cost of borrowing for companies and lower the discount rate used to value future cash flows. Every Federal Open Market Committee (FOMC) meeting and every speech by the Fed Chair can cause significant swings in the YTD percentage as investors recalibrate their expectations for the “cost of money.”
Resilience in Corporate Earnings
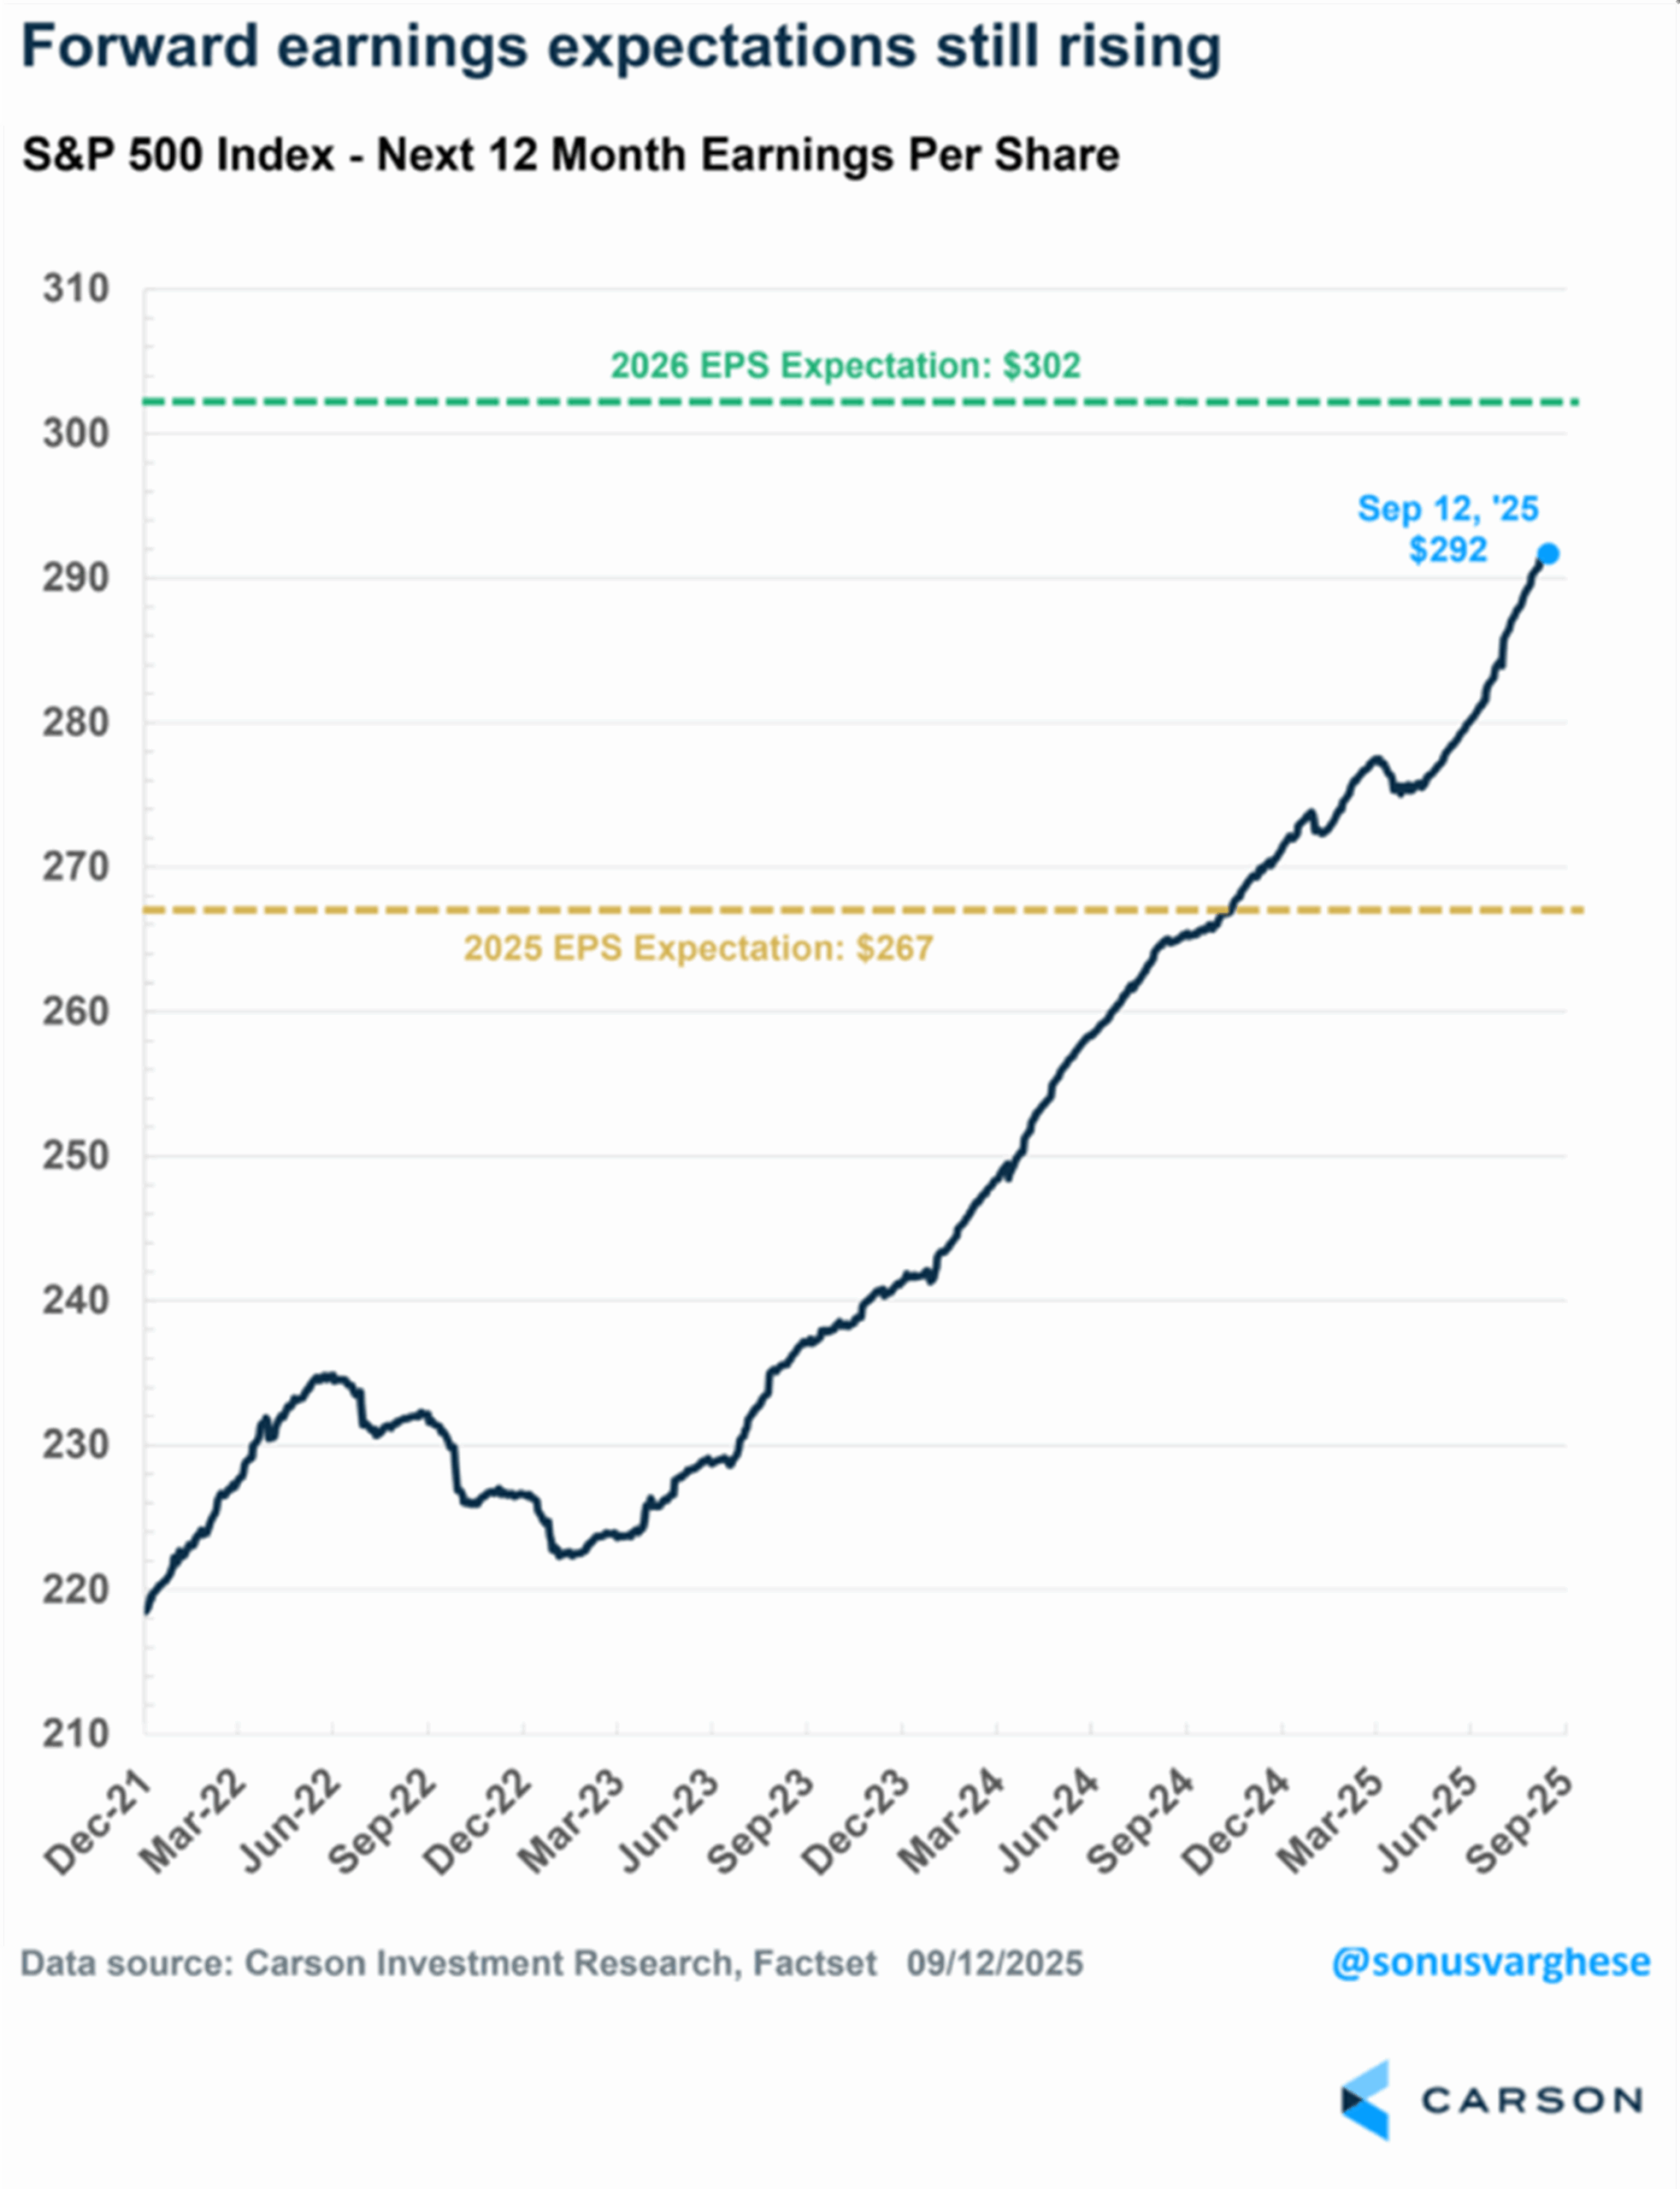
Despite fears of a slowdown, corporate America has shown remarkable resilience. Year-to-date growth is often underpinned by earnings reports that exceed analyst expectations. Companies have managed to maintain high profit margins by implementing cost-cutting measures and passing on higher costs to consumers. As long as earnings per share (EPS) continue to grow, the S&P 500 has a fundamental foundation to support its upward trajectory, even if valuations appear stretched on a historical basis.
Sector Performance: Winners and Losers Within the Index
To truly understand how much the S&P 500 is up, one must look beneath the surface at the 11 sectors that comprise the index. Market performance is rarely uniform; different sectors react differently to economic cycles.
The Dominance of Information Technology and Communication Services
Year to date, the Information Technology and Communication Services sectors typically lead the pack during bull runs. These sectors house the high-growth companies that benefit most from innovation and digital transformation. When the S&P 500 is up significantly YTD, it is almost always because these sectors are performing at an exceptional level. Investors flock to these areas for capital appreciation, often overlooking the lack of dividends in favor of massive price growth.
Defensive Sectors: Utilities and Consumer Staples
Conversely, when the market faces uncertainty, “defensive” sectors like Utilities, Consumer Staples, and Health Care may lag behind or provide a cushion during volatility. These companies produce essential goods and services that consumers need regardless of the economic climate. In a high-growth YTD environment, these sectors often underperform the broader index as investors rotate capital into higher-risk, higher-reward growth stocks. However, their performance is a key indicator of market sentiment; if Utilities start outperforming Tech, it usually signals that the market is bracing for a downturn.
Cyclical Sectors: Energy, Financials, and Industrials
The Energy and Financial sectors are highly sensitive to the economic cycle. Financials, including major banks, benefit from a healthy interest rate environment but can suffer if a recession looms. Energy stocks are tied directly to the price of crude oil and global demand. A strong YTD showing from these sectors indicates a “reopening” or “expansion” phase of the economy, suggesting that the rally in the S&P 500 is becoming more diversified and sustainable.
Historical Context and Valuation Metrics
Evaluating the S&P 500 YTD performance in a vacuum can be misleading. To gain perspective, investors must compare current returns to historical averages and look at valuation multiples like the Price-to-Earnings (P/E) ratio.
Average Annual Returns
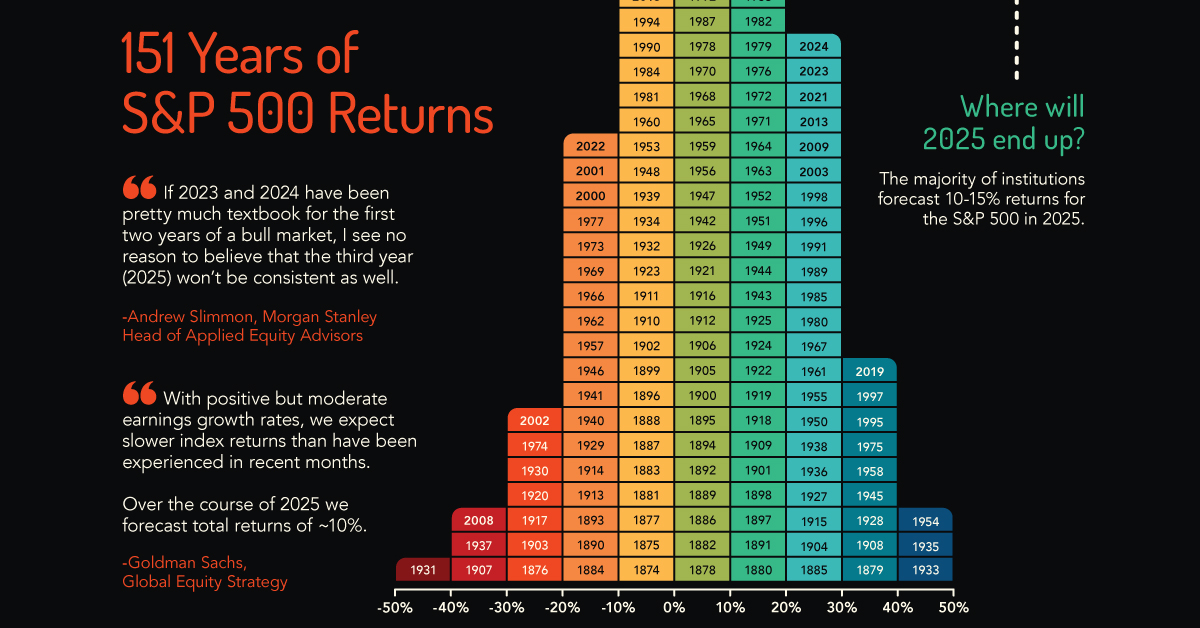
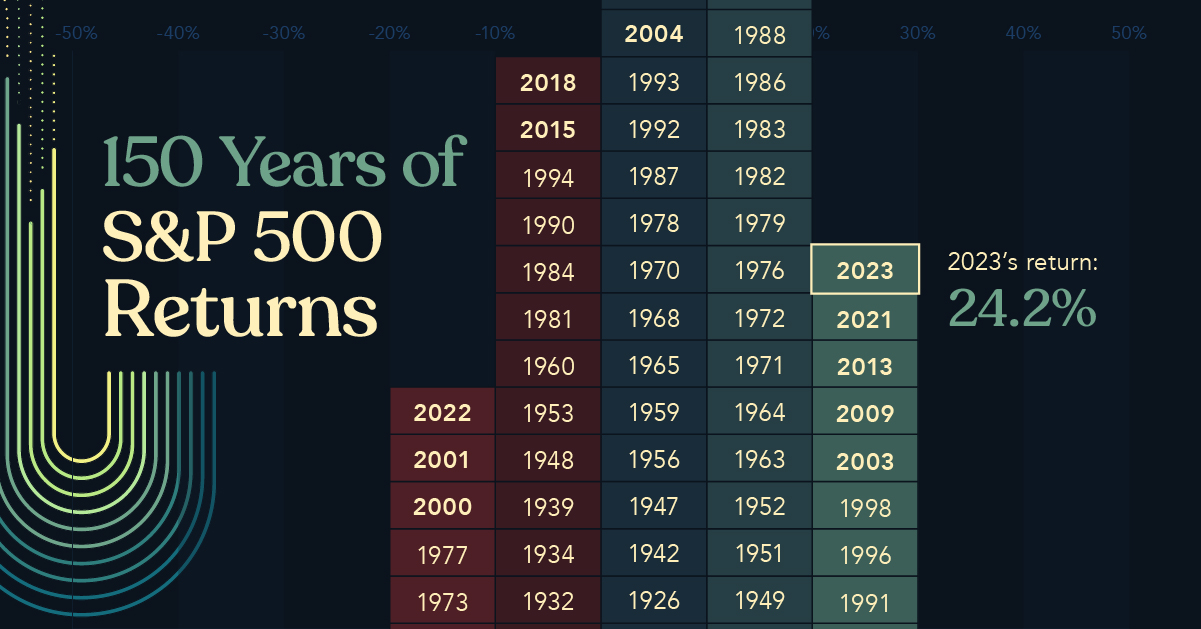
Historically, the S&P 500 has delivered an average annual return of approximately 10% before inflation. If the YTD return is already at 15% by mid-year, the market may be considered “overextended,” suggesting a potential for a correction or a period of sideways trading. Conversely, a flat or negative YTD return after a strong previous year is often viewed as a healthy “digestion” of gains. Long-term investors focus less on the specific YTD number and more on the rolling 5-year and 10-year averages, which tend to smooth out the noise of annual volatility.
The P/E Ratio and Market Value
The P/E ratio measures the index’s current price relative to its per-share earnings. A high P/E ratio relative to the historical mean (which sits around 16x to 18x) suggests that the S&P 500 is expensive. If the YTD gains are driven by price increases without a corresponding increase in earnings—a process known as “multiple expansion”—the market becomes more vulnerable to bad news. Insightful investors monitor whether the YTD rise is backed by “fundamental” growth (earnings) or “speculative” growth (investor excitement).
Strategic Implications for Investors
Knowing how much the S&P 500 is up year to date is only the first step. The more important question for those focused on personal finance and investing is: “What should I do with this information?”
The Risks of Performance Chasing
One of the most common mistakes investors make is “chasing” a strong YTD performance. When the index is up 20% by October, the fear of missing out (FOMO) often drives retail investors to pour money into the market at its peak. Historically, the best time to invest is often when the YTD performance is lackluster or negative, as this provides a lower entry point. A disciplined approach involves ignoring the short-term YTD fluctuations and sticking to a consistent investment schedule.
Dollar-Cost Averaging and Rebalancing
For those managing their own portfolios, a high YTD return in the S&P 500 might mean their portfolio is now “overweighted” in equities. For example, if an investor aims for a 60/40 split between stocks and bonds, a massive surge in the S&P 500 could shift that ratio to 70/30. Rebalancing involves selling a portion of the winning stocks to buy underperforming assets, effectively “selling high and buying low.” Additionally, dollar-cost averaging—investing a fixed amount of money at regular intervals—remains the most effective way to navigate the volatility of the S&P 500’s YTD movements.
Looking Ahead: The Path Forward
As the year progresses, the S&P 500’s YTD performance will continue to be shaped by earnings seasons, inflation data, and geopolitical stability. While the headline number provides a quick health check of the market, the sophisticated investor looks at the quality of those gains. Whether the index is up 5% or 25%, the principles of diversification, low-cost index fund investing, and a long-term horizon remain the most reliable tools for wealth creation. By understanding the “why” behind the “how much,” investors can make informed decisions that transcend simple daily fluctuations and build lasting financial security.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.