
The question “how much do people” might seem deceptively simple, yet its implications are profound when viewed through a financial lens. It probes deeply into the core of personal finance, touching upon everything from individual earnings and spending habits to long-term wealth accumulation and the pursuit of financial independence. Understanding these metrics is not merely about curiosity; it’s essential for individuals and businesses alike to make informed decisions, benchmark progress, and navigate the complex economic landscape.
Gauging Personal Income and Wealth
The foundation of “how much do people” earn begins with income. This isn’t a monolithic figure; it encompasses a wide spectrum of sources, ranging from traditional salaries to complex investment portfolios. Beyond just earning, the concept extends to wealth, which reflects what people have after accounting for assets and liabilities.

The Income Spectrum: Wages vs. Passive Earnings
For most, primary income is derived from wages or salaries, representing compensation for labor in a job or business. The amount varies dramatically based on industry, experience, education, geography, and negotiation skills. Entry-level positions naturally command lower figures than senior leadership roles or specialized professions. However, a growing number of people are diversifying their income streams beyond the traditional paycheck. This includes active income from side hustles, consulting, or freelancing, where direct effort correlates with earnings.
Increasingly significant are passive income streams, which generate revenue with minimal ongoing effort after an initial setup. Examples include rental income from real estate, dividends from stocks, interest from savings accounts or bonds, royalties from intellectual property, or profits from automated online businesses. While active income is often capped by time, passive income has the potential for exponential growth, contributing significantly to overall financial well-being and security. Understanding this distinction is crucial for strategic financial planning, as a robust financial future often involves a blend of both active and passive earnings.
Factors Influencing Individual Wealth
Wealth is not solely a function of high income. It’s a complex interplay of income, spending habits, saving discipline, and investment acumen over time. Key factors include:
-
Savings Rate: How much of one’s income is consistently saved directly impacts wealth accumulation. A higher savings rate accelerates the timeline for reaching financial goals.
-
Investment Returns: Money saved needs to be put to work through investments to combat inflation and benefit from compounding. The types of investments (stocks, bonds, real estate, etc.) and their performance play a critical role.
-
Time Horizon: The longer money is invested, the greater the potential for growth due to the power of compounding. Starting early, even with small amounts, can lead to substantial wealth over decades.
-
Debt Management: While some debt (like a mortgage) can be strategic, excessive high-interest debt (credit cards, personal loans) erodes wealth by diverting income towards interest payments rather than savings and investments.
-
Financial Literacy: Knowledge about budgeting, investing, taxes, and economic principles empowers individuals to make smarter financial decisions and avoid costly mistakes.
-
Economic Conditions: Broader economic factors like inflation rates, interest rates, and market performance also influence the value of assets and the purchasing power of money.
Dissecting Spending Patterns and Consumption
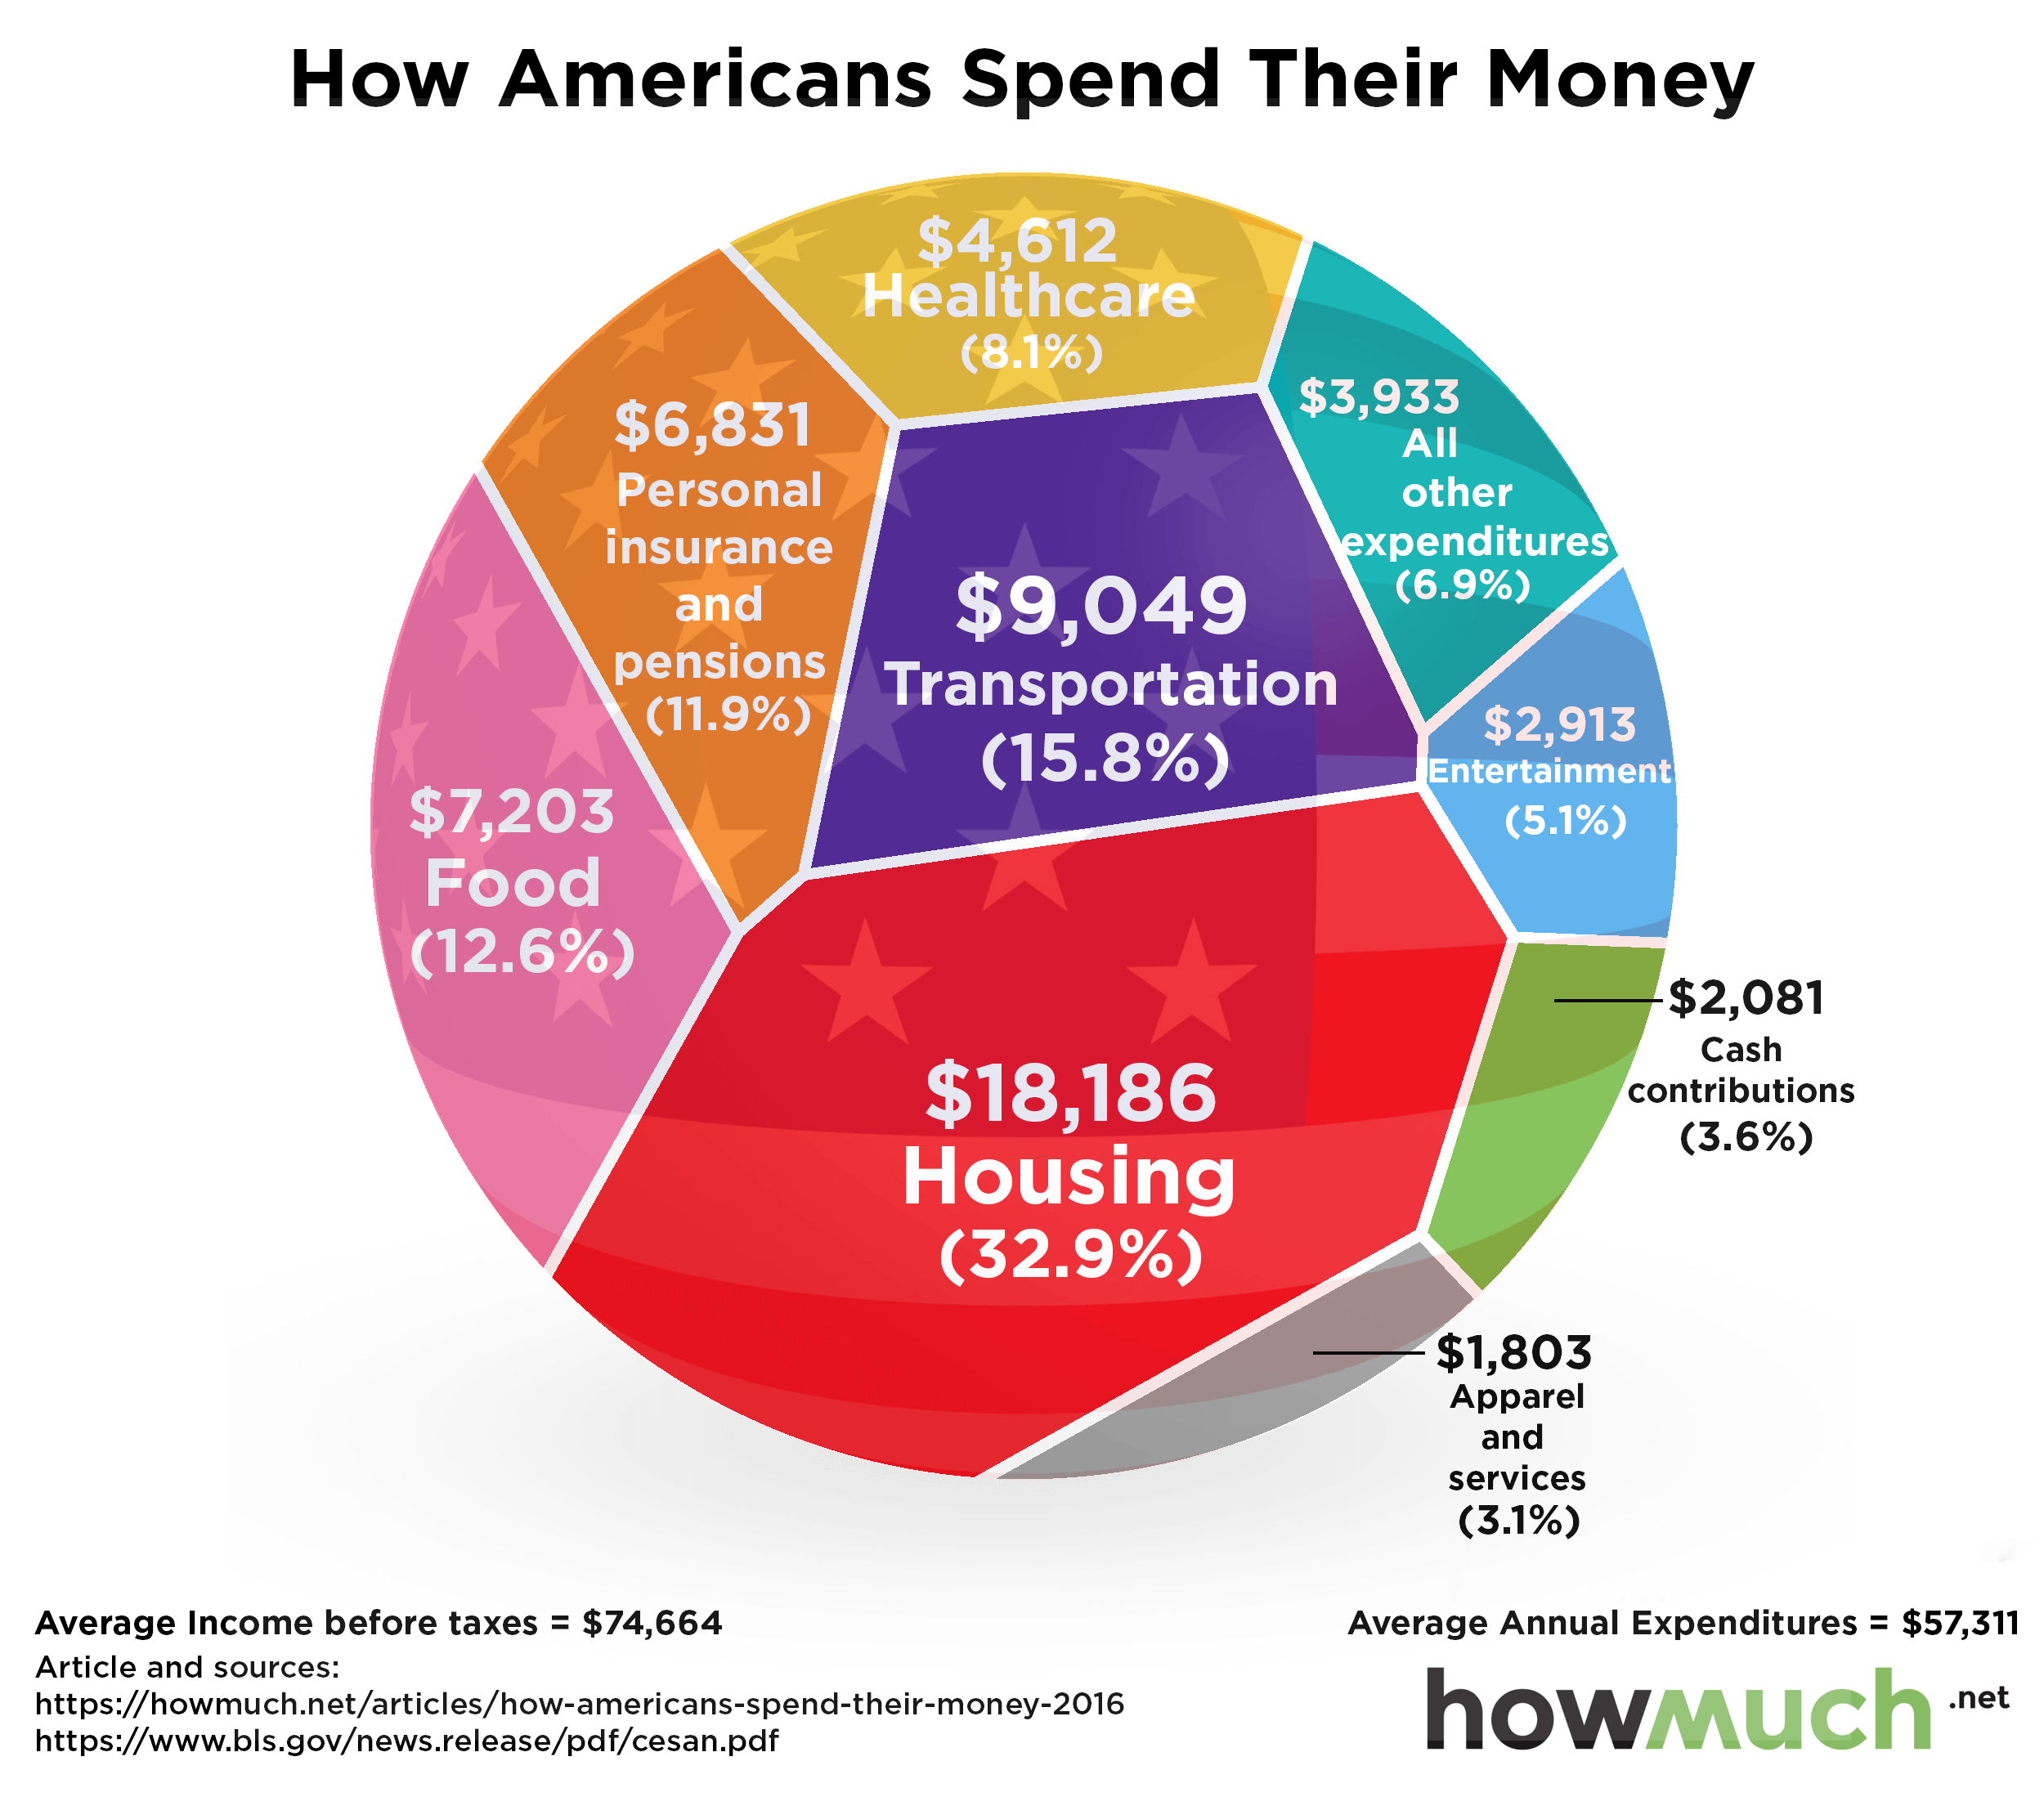
“How much do people” spend is arguably as important as how much they earn, as it directly impacts their ability to save, invest, and build wealth. Consumer behavior is shaped by a myriad of psychological, social, and economic factors, leading to diverse spending patterns across different demographics.
Discretionary vs. Essential Spending
All spending can broadly be categorized into two groups:
-
Essential Spending: These are non-negotiable expenses required for daily living. This includes housing (rent/mortgage), utilities, groceries, transportation, healthcare, and basic clothing. The proportion of income allocated to essentials varies widely depending on cost of living in a particular area, family size, and individual needs. Responsible budgeting prioritizes these expenses first.
-
Discretionary Spending: This refers to expenses that are not strictly necessary but contribute to quality of life, entertainment, and personal preferences. Examples include dining out, entertainment subscriptions, travel, hobbies, designer goods, and luxury services. While often viewed as “extra,” discretionary spending is a significant indicator of lifestyle and can be a flexible area for budget adjustments when aiming for specific financial goals. Understanding the balance between these two categories is fundamental to effective financial management.
Impact of Lifestyle Inflation
A common challenge many individuals face as their income grows is lifestyle inflation, also known as “lifestyle creep.” This phenomenon occurs when an increase in disposable income leads to an upgrade in one’s standard of living, often resulting in increased expenses that absorb the additional earnings. For example, a pay raise might lead to buying a larger house, a more expensive car, or dining out more frequently.
While some improvements in lifestyle are natural and desirable, unchecked lifestyle inflation can severely impede wealth accumulation. It makes it harder to save for retirement, invest for the future, or pay down debt, as the percentage of income saved remains stagnant or even decreases despite higher earnings. Conscious budgeting and a commitment to maintaining a reasonable standard of living relative to income are crucial for combating this often subtle yet powerful financial trap.
Digital Payments and Spending Insights
The proliferation of digital payment methods – credit cards, debit cards, mobile payment apps, and online banking – has revolutionized how people spend. While offering unparalleled convenience, these methods can sometimes blur the lines of real-time spending, making it harder to track expenses manually. However, they also offer unprecedented opportunities for data collection.
Many financial tools and apps now integrate with bank accounts and credit cards to automatically categorize spending, provide detailed reports, and even offer personalized insights into consumer habits. This data can reveal surprising patterns, such as how much is spent on subscriptions, impulse buys, or specific categories like food or entertainment. Leveraging these digital insights can empower individuals to gain a clearer understanding of their financial outflows, identify areas for reduction, and make more informed budgeting decisions.
Navigating Savings and Investment Strategies
The question “how much do people” save and invest directly addresses financial security and future prosperity. While earning and managing spending are vital, it’s the consistent act of setting aside money and strategically growing it that truly builds long-term wealth.
Emergency Funds and Short-Term Goals
A cornerstone of sound personal finance is establishing an emergency fund. This is a dedicated pool of accessible cash, typically held in a high-yield savings account, designed to cover unexpected expenses like job loss, medical emergencies, or significant home repairs. Experts generally recommend having 3-6 months’ worth of essential living expenses saved. Without an adequate emergency fund, unforeseen events can derail financial progress, forcing reliance on high-interest debt.
Beyond emergencies, people save for various short-term goals: a down payment on a house, a new car, a vacation, or a child’s education. These goals often have specific timelines and require a disciplined approach to saving. Setting clear targets, tracking progress, and separating these funds from daily spending accounts are common strategies to achieve them effectively.
Long-Term Investment Strategies
For goals stretching further into the future – most notably retirement – investing becomes paramount. Simply saving money in a low-interest account will often lead to a loss of purchasing power due to inflation. Investing, conversely, aims to grow capital over time. Common investment avenues include:
-
Stocks: Representing ownership in companies, stocks offer potential for high returns but also carry higher risk.
-
Bonds: Debt instruments issued by governments or corporations, generally considered less risky than stocks but with lower potential returns.
-
Mutual Funds and Exchange-Traded Funds (ETFs): Portfolios of stocks, bonds, or other assets managed by professionals, offering diversification and convenience.
-
Real Estate: Investing in properties can generate rental income and capital appreciation, though it requires significant capital and management.
A critical aspect of long-term investing is diversification – spreading investments across different asset classes to mitigate risk. Additionally, a long-term perspective is crucial, riding out market fluctuations rather than reacting impulsively. The specific strategy depends on individual risk tolerance, financial goals, and time horizon.
Retirement Planning and Wealth Preservation
Retirement planning is arguably the most significant long-term financial goal for most people. It involves estimating future expenses, calculating the amount of capital needed, and implementing a savings and investment plan to reach that target. This often includes utilizing tax-advantaged accounts like 401(k)s, IRAs, or Roth IRAs, which offer significant benefits for long-term growth.
Wealth preservation becomes increasingly important as one approaches and enters retirement. This shifts the focus from aggressive growth to protecting capital, generating income, and managing withdrawals to ensure the money lasts. Estate planning, long-term care insurance, and understanding social security benefits also become crucial components of this phase, ensuring that the wealth accumulated serves its intended purpose and can potentially be passed on to future generations.
Exploring Diverse Income Streams and Financial Resilience
The traditional model of a single, full-time job providing all income is evolving. “How much do people” earn is increasingly a question with multiple answers, as individuals actively seek out diverse income streams to boost earnings, build financial resilience, and gain greater control over their financial futures.
Side Hustles and Gig Economy Earnings
The rise of the gig economy has created unprecedented opportunities for individuals to leverage existing skills or develop new ones to earn supplemental income. Side hustles, ranging from freelance writing and graphic design to ride-sharing and food delivery, allow people to generate extra cash outside their primary employment. These ventures offer flexibility and can be a valuable way to pay off debt faster, save for specific goals, or even test a business idea before committing fully.
The income generated from side hustles varies immensely based on the time invested, the demand for the service, and the individual’s skill level. For some, it might be a few hundred dollars a month; for others, it can rival or even surpass their main job’s salary. Beyond the direct financial gain, side hustles contribute to financial resilience by diversifying income sources, reducing reliance on a single employer, and providing a safety net in uncertain economic times.
Online Businesses and Digital Products
The internet has democratized entrepreneurship, allowing individuals to create and scale online businesses with relatively low overhead. This includes selling digital products (e-books, online courses, templates), e-commerce ventures (drop-shipping, artisanal goods), content creation (blogging, vlogging, podcasting with advertising or sponsorship revenue), and affiliate marketing.
These online income streams often have the potential for greater scalability and automation than traditional side hustles. Once established, some digital products can generate passive income, further contributing to long-term wealth. However, building a successful online business requires significant initial effort, marketing savvy, and a deep understanding of target audiences. The rewards, in terms of financial independence and flexible lifestyles, can be substantial.

Real Estate and Other Asset-Based Incomes
Beyond active and digital income, many individuals seek to generate income from assets they own. Real estate remains a popular choice, with rental properties providing steady cash flow and potential for appreciation. This can range from long-term residential rentals to short-term vacation rentals, each with its own set of management demands and potential returns.
Other asset-based income streams include dividends from stock portfolios, interest from bonds or peer-to-peer lending, royalties from creative works, or even licensing intellectual property. The key characteristic of these streams is that the asset itself generates income, often with minimal ongoing active involvement from the owner once established. Building a portfolio of income-generating assets is a long-term strategy for creating robust financial resilience and moving towards financial independence, ensuring that “how much do people” earn isn’t solely tied to their active working hours.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.