
In the high-stakes world of commercial aviation, safety is not merely a moral imperative; it is the fundamental pillar of financial stability. For investors, stakeholders, and market analysts, the question “how many spirit planes have crashed” serves as a entry point into a deeper discussion about the economic resilience of the Ultra-Low-Cost Carrier (ULCC) business model. While the public perception of budget airlines is often colored by memes and anecdotal complaints regarding seat comfort or baggage fees, the fiscal reality of their safety record tells a much more significant story.
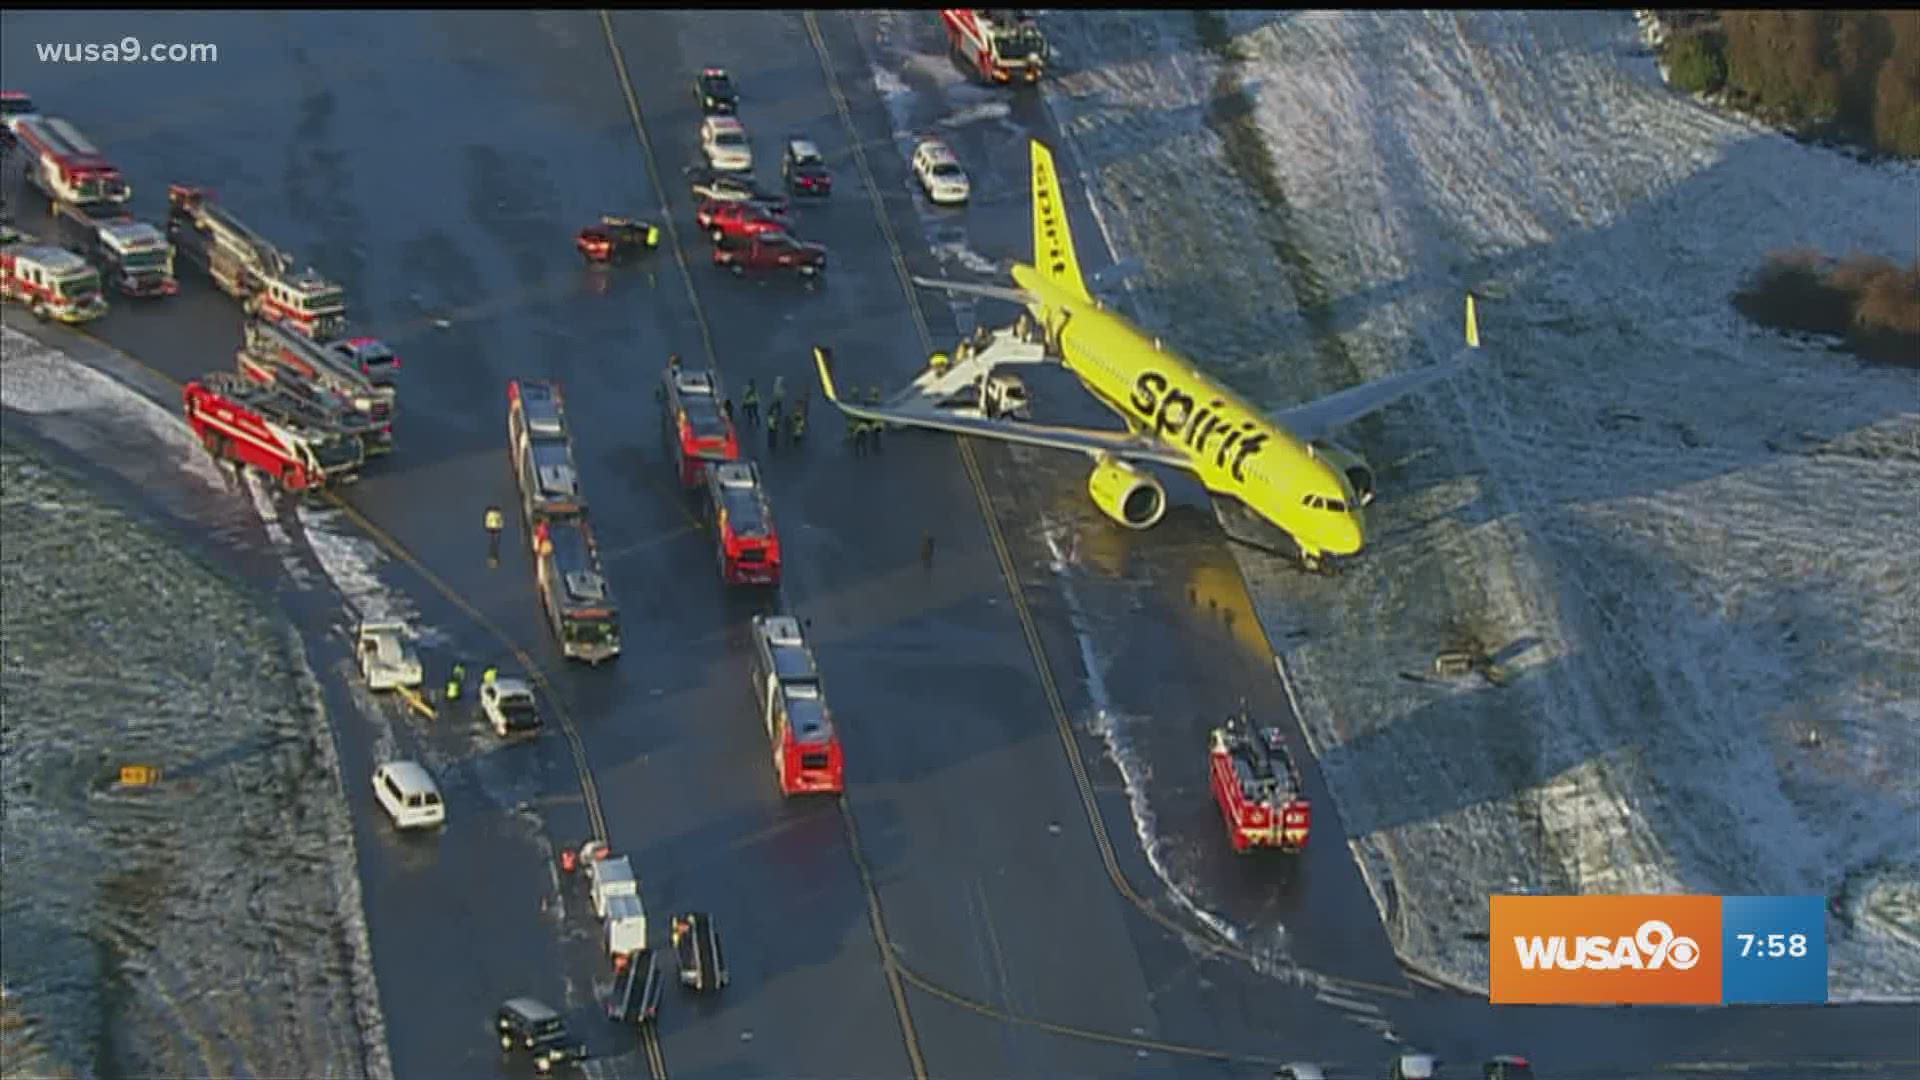
To date, Spirit Airlines has recorded zero fatal crashes in its history as a commercial operator. This statistical fact is a cornerstone of the company’s valuation and its ability to remain competitive in a capital-intensive industry. In the aviation sector, a single catastrophic event can lead to billions of dollars in lost market capitalization, astronomical insurance premium hikes, and a brand devaluation that can take decades to recover. By maintaining a clean safety record, Spirit has protected its bottom line from the most volatile risk factor in the transport economy.
The Quantitative Reality: Spirit Airlines’ Safety Record in Financial Context
When analyzing the safety of an airline through a financial lens, we look at hull losses, major incidents, and FAA regulatory compliance. Spirit Airlines operates a fleet of over 200 Airbus A320 family aircraft, and throughout its expansion from a regional carrier to a national powerhouse, it has avoided the catastrophic losses that often plague emerging airlines in developing markets.
The Fiscal Impact of Zero Hull Losses
In aviation accounting, a “hull loss” occurs when an aircraft is damaged beyond economical repair. For an airline like Spirit, which operates on razor-thin margins, the loss of an airframe represents a massive hit to the balance sheet. Spirit’s record of zero hull losses means they have maximized the ROI on their most expensive assets. Each aircraft in their fleet represents an investment of roughly $50 million to $100 million (list price, though often discounted in bulk orders). Avoiding losses ensures that debt service on these assets remains predictable and that the airline can maintain its aggressive growth strategy.
Incident Rates and Operating Margins
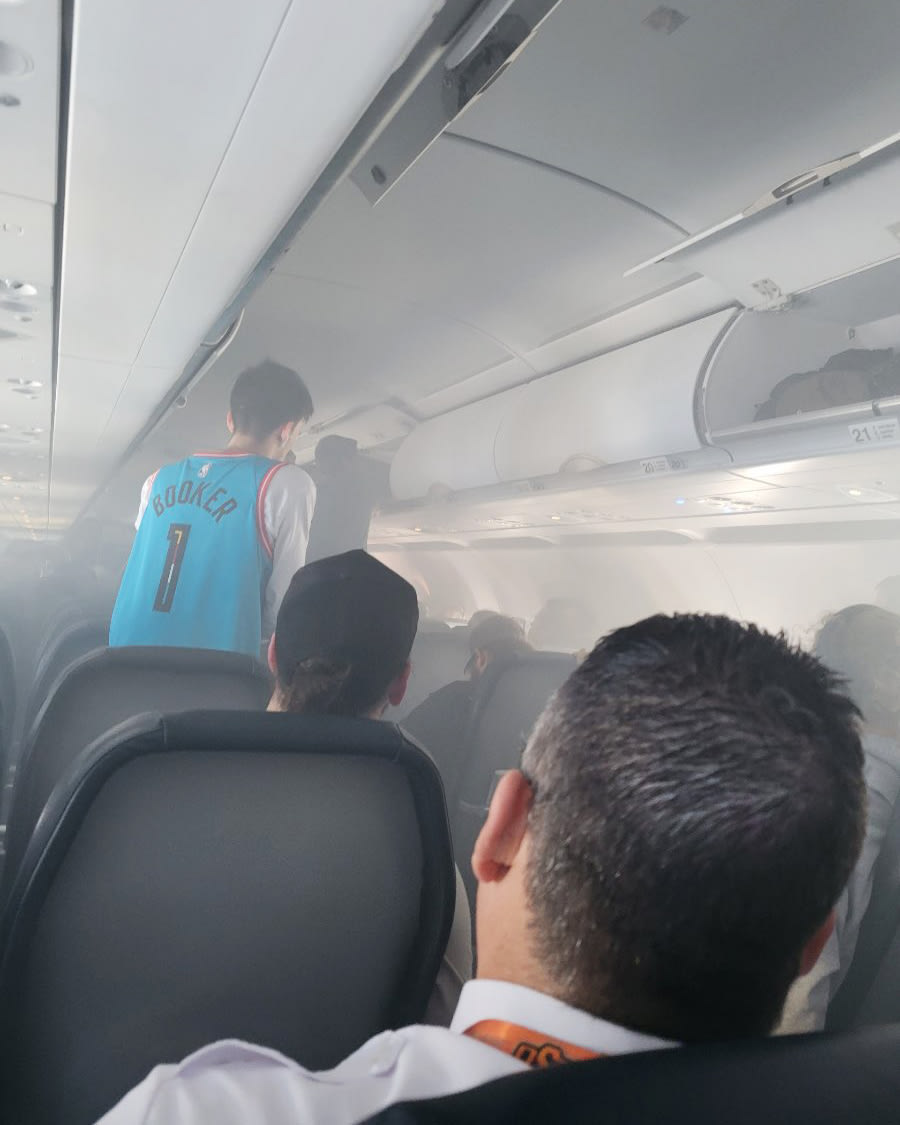
While Spirit has avoided crashes, it—like all major carriers—experiences mechanical diversions and minor incidents. However, the frequency of these incidents is remarkably low relative to its number of daily departures. From a business finance perspective, this indicates a high level of operational efficiency. Frequent unscheduled maintenance or emergency landings create “soft costs,” including passenger re-accommodation, crew timing issues, and gate delays. Spirit’s ability to minimize these disruptions is a key driver of its low-cost structure.
The Financial Architecture of Safety: How ULCCs Invest in Maintenance
A common misconception in the “Money” niche of aviation is that lower ticket prices equate to lower safety standards. In reality, the regulatory environment in the United States makes safety a fixed cost. For Spirit Airlines, the economic strategy is not to cut corners on safety, but to optimize the technology and age of the fleet to reduce long-term maintenance liabilities.
Fleet Modernization as a Cost-Saving Strategy
Spirit Airlines maintains one of the youngest fleets in the industry, with an average aircraft age of around seven years. This is a deliberate financial move. Newer aircraft, such as the Airbus A320neo, are not only more fuel-efficient—directly impacting the airline’s largest variable cost—but they also require less heavy maintenance compared to the aging fleets of legacy carriers like Delta or United.
By investing heavily in new technology, Spirit reduces the “maintenance-to-flight-hour” ratio. This lowers the overhead required for specialized mechanics and spare parts inventory. For investors, this translates to a more predictable burn rate and higher asset utilization. A plane that is not in the shop for repairs is a plane that is generating revenue.
The Economics of Training and Compliance
Spirit’s financial commitment to safety is also reflected in its training infrastructure. The airline recently opened a massive corporate campus and training center in Dania Beach, Florida. This capital expenditure demonstrates a long-term investment in human capital. High-quality training reduces the probability of pilot error—the leading cause of aviation accidents—thereby insulating the company from the massive legal and financial liabilities that follow human-error-driven incidents.
Market Perception vs. Fiscal Performance: The Cost of Reputation
There is often a disconnect between an airline’s “brand” and its financial “safety value.” In the case of Spirit, the brand is frequently maligned for its “no-frills” approach. However, for a savvy investor, the gap between public perception and actual safety data represents an opportunity.
The Social Media Premium and Stock Volatility
In the modern digital economy, viral videos of cabin disputes or minor delays can cause temporary dips in stock prices. However, these are often superficial market reactions. The underlying value of Spirit remains tied to its operational safety. Because the answer to “how many spirit planes have crashed” remains “zero,” the airline avoids the “safety premium” that insurers charge more volatile carriers. This keeps Spirit’s insurance costs significantly lower than those of international carriers operating in higher-risk jurisdictions, directly benefiting the net income.
Valuation and the “Safety Discount”
When analysts value an airline, they apply a risk discount based on the likelihood of operational failure. Because Spirit has proven its ability to scale without compromising safety, it has historically enjoyed a lower risk discount than many of its global low-cost peers. This has allowed Spirit to access credit markets with more favorable terms, enabling them to finance their massive aircraft orders from Airbus. The ability to borrow at competitive rates is entirely dependent on the confidence that the collateral (the aircraft) will not be destroyed through negligence or poor maintenance.
The Future of Spirit Airlines: Safety, Scale, and Financial Restructuring
As of 2024, Spirit Airlines faces significant financial headwinds, not due to its safety record, but due to shifting market dynamics, the blocked merger with JetBlue, and issues with Pratt & Whitney GTF engines. However, its safety record remains its most valuable intangible asset as it navigates these challenges.
The Pratt & Whitney Engine Issue: A Technical and Financial Crisis
While not related to crashes, the grounding of several Spirit aircraft due to issues with Pratt & Whitney engines has been a major financial blow. This situation highlights how “safety-first” protocols can create short-term financial pain for long-term stability. Spirit chose to ground aircraft and inspect engines rather than risk operational failure. While this led to a decrease in capacity and revenue, it preserved the airline’s safety integrity. The financial fallout is being mitigated through compensation agreements with the engine manufacturer, proving that even in “technical” failures, the legal and financial framework of the industry favors those who prioritize safety protocols.
Merger Valuations and Safety Assets
During the merger negotiations with JetBlue and the subsequent antitrust litigation, Spirit’s operational record was a key component of its valuation. A “troubled” airline with a history of accidents is a liability in a merger; a “clean” airline is a growth platform. For JetBlue, the attraction was Spirit’s fleet and its operational footprint. Had Spirit had a history of crashes, the “Brand Damage” would have made the acquisition a non-starter for any board of directors concerned with fiduciary duty.

Conclusion: The Bottom Line for the Investor
In the final analysis, the safety record of Spirit Airlines is a masterclass in risk management within a low-margin business model. The answer to how many Spirit planes have crashed—none—is the most important financial metric the company possesses. It allows for lower insurance premiums, better financing terms for fleet expansion, and a foundational level of consumer trust that permits the airline to continue its high-volume, low-cost operations.
For those tracking the intersection of aviation and finance, Spirit proves that a “budget” price tag does not necessitate a “budget” approach to safety. As the airline looks toward restructuring and navigating its current debt load, its impeccable safety record will be the primary asset that gives creditors and the market confidence in its long-term viability. In the business of flying, safety is the ultimate currency, and Spirit Airlines has managed its account with expert precision.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.