
Understanding your yearly income is far more than a simple numerical exercise; it’s the bedrock of sound financial planning, budgeting, tax preparation, and goal setting. Whether you’re a salaried employee, a burgeoning freelancer, a seasoned business owner, or juggling multiple income streams, accurately calculating your annual earnings provides the clarity needed to make informed financial decisions. Without this fundamental insight, it’s challenging to assess your financial health, track progress towards savings goals, or even determine your eligibility for loans and other financial products. This guide will walk you through the process, breaking down the components of income and offering practical steps to ascertain your total yearly earnings with precision.
Understanding the Foundation: What Constitutes Your Income?
Before diving into calculations, it’s crucial to establish a clear understanding of what “income” entails and its different forms. This foundational knowledge ensures you don’t overlook any sources or misinterpret financial figures.
Differentiating Gross vs. Net Income
One of the most common points of confusion is the distinction between gross and net income.
-
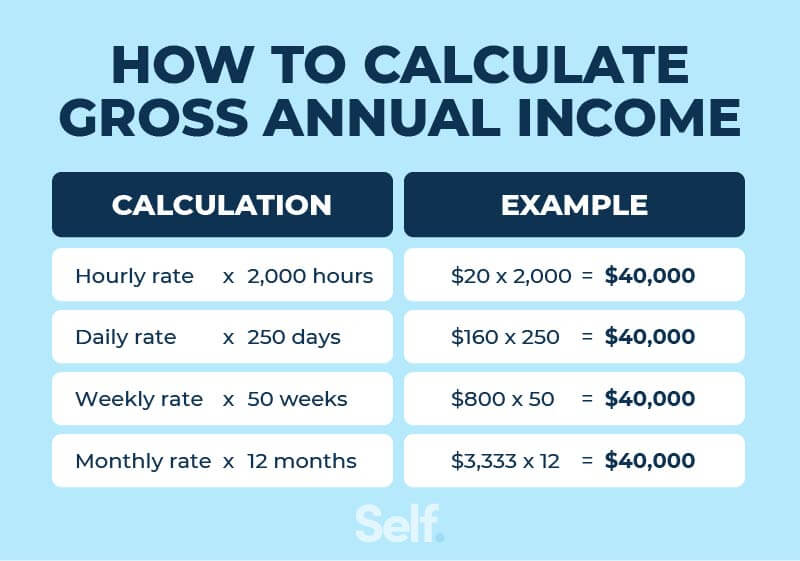
Gross Income refers to the total amount of money you earn before any taxes, deductions, or other expenses are withheld or subtracted. For an employee, this is your salary or hourly wage multiplied by hours worked, plus any bonuses or commissions. For a business owner or freelancer, it’s the total revenue generated before business expenses are paid.
-
Net Income (or Take-Home Pay) is the amount of money you actually receive after all mandatory and voluntary deductions have been taken out. These deductions typically include federal, state, and local income taxes, Social Security and Medicare contributions (FICA), retirement plan contributions (like 401(k) or 403(b)), health insurance premiums, and other pre-tax or post-tax withholdings.
When figuring out your yearly income for financial planning, it’s often most useful to calculate your gross yearly income first, as this represents your total earning capacity. However, understanding your net yearly income is equally vital for budgeting your daily expenses and savings.
Identifying All Income Streams
Most people’s financial lives are rarely a single, straightforward stream. To accurately calculate your total yearly income, you must identify every single source from which money flows into your accounts. This includes:
-
Primary Employment: Wages, salaries, commissions, bonuses.
-
Self-Employment/Freelance Work: Income from clients, contract gigs, consulting.
-
Business Profits: Distributions or owner’s draw from a sole proprietorship, partnership, or LLC.
-
Investment Income: Dividends from stocks, interest from savings accounts or bonds, capital gains from selling investments, rental property income.
-
Side Hustles: Earnings from gig economy apps, selling handmade goods, online courses, etc.
-
Benefits: Unemployment benefits, disability payments, pensions, Social Security benefits, alimony, child support.
-
Other Miscellaneous Income: Royalties, gambling winnings, gifts (though often not taxable, they contribute to your overall financial picture).
A comprehensive list ensures no stone is left unturned, providing the most accurate picture of your financial inflows.
The Importance of a Defined Timeframe
While the title specifies “yearly income,” it’s worth noting the importance of this timeframe. Your income can fluctuate monthly, quarterly, or seasonally, especially if you’re self-employed or rely on commissions. Aggregating these figures over a full 12-month period provides a stable, representative average that smooths out short-term variations, making it much more reliable for long-term financial planning and tax purposes. Always ensure your calculations cover a consistent, complete calendar year or fiscal year.
Step-by-Step Calculation for Salaried Employees (W2)
For individuals employed by a company who receive a W-2 form, calculating yearly income is generally more straightforward, as much of the tracking is handled by your employer.
Locating Key Figures from Pay Stubs and Tax Documents
The most reliable sources for your income figures are your pay stubs and your year-end W-2 form.
-
Pay Stubs: Each pay stub (bi-weekly, semi-monthly, or monthly) will detail your gross pay for that period, along with all deductions. While you could sum up 26 bi-weekly pay stubs, it’s more efficient to wait for the annual statement.
-
W-2 Form: This is the ultimate document for calculating your yearly income as an employee. Box 1, “Wages, tips, other compensation,” provides your taxable gross income for federal income tax purposes. Box 3, “Social Security wages,” and Box 5, “Medicare wages and tips,” typically reflect your total gross earnings up to the Social Security wage base limit. For most purposes, Box 1 is the primary figure you’ll use to determine your yearly income from employment, as it accounts for certain pre-tax deductions that reduce your taxable income (like 401(k) contributions).
Accounting for Bonuses, Commissions, and Overtime
If your compensation structure includes variables beyond a fixed salary, ensure these are accurately reflected.
-
Bonuses: Any bonuses received throughout the year are part of your gross income. Your W-2 will typically include these in Box 1.
-
Commissions: Sales commissions are also part of your gross income and will be reported on your W-2.
-
Overtime Pay: Extra hours worked and paid at a higher rate contribute directly to your gross earnings. All overtime compensation is included in your W-2 figures.
Make sure to include all these variable components in your annual sum.
Handling Pre-Tax Deductions (401k, Health Insurance Premiums)
It’s important to understand how pre-tax deductions affect your reported income. Contributions to pre-tax retirement accounts (like a traditional 401(k) or 403(b)) and certain health insurance premiums are subtracted from your gross pay before income taxes are calculated. This means your Box 1 income on your W-2 is lower than your total salary + bonus + overtime earnings. For a holistic view of your earning power, you might sum your Box 1 income and any pre-tax contributions reported on your pay stubs or W-2 (e.g., Box 12 codes D, E, F, G, S).
The Role of Year-End Statements (W-2 Form)
The W-2 form, issued by your employer by January 31st of the following year, is the definitive document for your annual employment income. It summarizes all your wages, tips, and other compensation, along with taxes withheld, making it the primary tool for accurately determining your yearly income from that employer. If you had multiple employers in a year, you’ll receive a W-2 from each, and you’ll simply combine the Box 1 figures from all of them.
Navigating Income for Freelancers, Contractors, and Business Owners (1099)
Calculating yearly income for self-employed individuals, freelancers, and business owners requires a more proactive approach, as there’s no employer doing the tracking for you.
Tracking All Revenue Sources (Invoices, Payment Processors)
The first step is meticulously tracking all money flowing into your business or personal accounts from your work. This includes:
-
Invoices: Maintain a clear record of every invoice issued and paid.
-
Payment Processors: Review statements from platforms like PayPal, Stripe, Square, Upwork, Fiverr, or other online payment gateways.
-
Bank Statements: Regularly reconcile your business bank accounts to ensure all deposits are accounted for.
-
Cash Payments: If you receive cash, establish a system to record it immediately.
The Critical Role of Expense Tracking
For the self-employed, gross revenue isn’t your true income. What matters is your net business income, which is revenue minus legitimate business expenses. This is crucial for tax purposes and for understanding your actual profitability. Keep meticulous records of all expenses, such as:
-
Office supplies and equipment
-
Software subscriptions
-
Marketing and advertising costs
-
Professional development and training
-
Business travel and meals
-
Home office deductions
-
Contractor payments
-
Insurance premiums
-
Legal and accounting fees
Categorize these expenses regularly to make annual summation easier.

Calculating Net Business Income (Revenue – Expenses)
Once you have your total annual revenue and total annual expenses, your net business income is straightforward:
Total Annual Revenue – Total Annual Business Expenses = Net Business Income
This net figure is what you will typically report on Schedule C (Form 1040) for sole proprietorships and single-member LLCs, or similar forms for partnerships and corporations.
Estimating Self-Employment Taxes
Unlike W-2 employees, self-employed individuals are responsible for both the employer and employee portions of Social Security and Medicare taxes (FICA), known as self-employment tax. This significantly impacts your true take-home pay. While not directly part of your income calculation, it’s a crucial consideration when projecting your net financial position. You’ll typically need to pay estimated taxes quarterly.
Utilizing Financial Software for Easier Management
To simplify income and expense tracking, consider using accounting software designed for small businesses and freelancers, such as QuickBooks Self-Employed, FreshBooks, or Wave. These tools can:
-
Automate expense categorization.
-
Generate invoices and track payments.
-
Provide real-time reports on your income and expenses.
-
Help estimate quarterly taxes.
This technology can save significant time and reduce errors compared to manual spreadsheets.
Incorporating Other Income Streams for a Holistic View
To arrive at your total yearly income, you must add up all other sources of earnings beyond your primary employment or business.
Investment Income (Dividends, Interest, Capital Gains)
Review statements from your investment accounts (brokerage, bank savings accounts, mutual funds) for the year.
-
Dividends: Payments from stocks or mutual funds. These are reported on Form 1099-DIV.
-
Interest: Earnings from savings accounts, CDs, or bonds. Reported on Form 1099-INT.
-
Capital Gains: Profits from selling an investment for more than you bought it. These are tracked on Form 1099-B.
Sum all these figures for your annual investment income.
Rental Income (and Associated Expenses)
If you own rental properties, calculate your total rent collected for the year. Remember to subtract eligible rental property expenses (mortgage interest, property taxes, insurance, repairs, depreciation, property management fees) to determine your net rental income, which is what you’ll typically report on Schedule E (Form 1040).
Side Hustle Earnings and Gig Economy Income
Any income earned outside your primary job or main business venture should be added. This includes earnings from:
-
Ridesharing or food delivery apps (Uber, Lyft, DoorDash).
-
Selling items on platforms like eBay, Etsy, or Poshmark.
-
Consulting or small projects done on the side.
-
Tutoring or coaching.
Many of these platforms will issue a Form 1099-NEC or 1099-K if your earnings exceed certain thresholds, making tracking easier. Otherwise, keep meticulous records of all income and associated expenses.
Benefits and Pensions
If you receive income from sources like Social Security, unemployment benefits, disability payments, or a pension, these amounts also contribute to your yearly income. You’ll typically receive year-end statements (e.g., Form SSA-1099 for Social Security, Form 1099-R for pensions/retirement distributions, Form 1099-G for unemployment) detailing these amounts.
Other Miscellaneous Income (Gifts, Royalties, etc.)
Don’t forget any other unique income sources, such as:
-
Royalties from books, music, or patents.
-
Alimony received.
-
Gambling winnings (reported on Form W2-G).
While some gifts may not be taxable income, they are still financial inflows that impact your overall personal finances.
The Power of Regular Review and Tools for Accuracy
Calculating your yearly income isn’t a one-time event; it’s a continuous process that benefits from regular attention and the right tools.
Why Annual Income Review is Crucial
Reviewing your yearly income is vital for several reasons:
-
Budgeting: It forms the foundation for creating and sticking to a realistic budget.
-
Goal Setting: Helps you track progress towards financial goals like saving for a down payment, retirement, or paying off debt.
-
Tax Planning: Essential for accurate tax preparation and identifying potential deductions or credits.
-
Financial Health Check: Provides a snapshot of your earning capacity and financial stability.
-
Loan Eligibility: Lenders will require accurate income figures for mortgages, car loans, and personal loans.
-
Identifying Opportunities: Highlighting fluctuations can reveal patterns or opportunities to increase earnings or cut expenses.
Leveraging Spreadsheets and Budgeting Apps
For most individuals, a well-structured spreadsheet (using programs like Excel or Google Sheets) can be an invaluable tool. You can create columns for each income source and sum them annually.
Alternatively, numerous budgeting and financial management apps (e.g., Mint, YNAB, Personal Capital, Empower) can help aggregate your financial data, categorize transactions, and provide an overview of your income and expenses. Many can link directly to your bank and investment accounts, automating much of the data collection.
Consulting with Financial Professionals
If your financial situation is complex—perhaps you have multiple businesses, extensive investments, or unique tax circumstances—consulting with a certified public accountant (CPA) or a financial advisor is highly recommended. These professionals can ensure accuracy, optimize your tax strategy, and provide personalized advice tailored to your specific financial goals. Their expertise can be particularly valuable in identifying all legitimate deductions and correctly reporting various income types.

Preparing for Tax Season (and Future Planning)
Accurately figuring out your yearly income is, at its heart, about preparing for tax season. Having all your income figures organized and documented throughout the year makes tax preparation far less stressful. Beyond taxes, this clarity allows you to:
-
Plan for future investments.
-
Determine how much you can afford to save.
-
Make informed decisions about career changes or new business ventures.
-
Understand your financial trajectory and make adjustments as needed.
The journey to financial clarity begins with accurately understanding your yearly income. By meticulously tracking all your earnings, differentiating between gross and net, and leveraging available tools and professional advice, you empower yourself with the knowledge needed to build a secure and prosperous financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.