
In the current era of digital-first finance, the ability to move capital fluidly between platforms is more than a convenience; it is a necessity for effective cash flow management. PayPal and Venmo stand as the two titans of the mobile payment world, both owned by PayPal Holdings, Inc., yet operating as distinct ecosystems with unique user interfaces and financial purposes. While PayPal remains the global standard for e-commerce, international transactions, and professional invoicing, Venmo has carved out a dominant niche in the peer-to-peer (P2P) social payment space.
For the modern consumer or side-hustler, the question of how to link these two accounts often arises from a desire to consolidate funds or bridge the gap between business earnings and personal spending. Although there is no single “sync” button that merges the two balances, creating a strategic bridge between them is a fundamental skill for anyone looking to optimize their personal finance toolkit.
The Financial Synergy of PayPal and Venmo
To understand the mechanics of linking these platforms, one must first understand their different roles in a financial portfolio. PayPal is often treated as a digital checking account or a merchant gateway. It offers robust buyer and seller protections, supports multiple currencies, and integrates with nearly every major online retailer. In contrast, Venmo is designed for high-velocity, small-dollar transactions—splitting dinner bills, paying rent to a roommate, or receiving tips for freelance work.
The primary financial benefit of linking these accounts is liquidity. If you receive a payment from a client via PayPal but need that money to pay a friend via Venmo, knowing how to navigate the transfer process efficiently ensures you aren’t waiting days for funds to clear or paying unnecessary fees. By creating a unified pipeline, you effectively treat these two separate apps as a single, multi-functional financial hub.
Capital Allocation and Ecosystem Management
Efficient money management requires minimizing the “dead time” where your money is sitting in a digital wallet not earning interest or being utilized. When you link Venmo and PayPal through a centralized banking hub, you gain the ability to reallocate capital based on your immediate needs. This is particularly useful for individuals who manage their personal and “gig economy” finances across multiple platforms.
The Strategic Bridge: How to Interconnect Your Funds
Because PayPal and Venmo operate on separate ledgers, “linking” them is actually a process of connecting both to a common intermediary. There are three primary methods to achieve this, each with its own set of financial implications regarding speed and cost.
Method 1: The Centralized Bank Account Hub
The most reliable way to link Venmo and PayPal is by using a single, verified bank account as the anchor for both. This creates a “hub-and-spoke” model where your bank sits at the center.
-
Verification: First, ensure your primary checking account is linked and verified on PayPal. This usually involves confirming two small “micro-deposits.”
-
Venmo Integration: Add the same bank account to your Venmo profile. Venmo uses Plaid for instant verification, making this step relatively seamless.
-
The Transfer Loop: To move money from PayPal to Venmo, you must first withdraw your PayPal balance to your bank account. Once the funds land (which can be instant for a small fee or 1–3 business days for free), you can then “Pull” that money into Venmo if you have a Venmo Debit Card, or simply use the bank balance to fund your Venmo payments.
Method 2: The PayPal Debit Card Strategy
For those who need immediate access to PayPal funds within the Venmo ecosystem without waiting for bank processing times, the PayPal Business or Personal Debit Mastercard is a vital tool.
By adding your PayPal Debit Card as a “Payment Method” within Venmo, you can essentially fund Venmo transactions directly using your PayPal balance. This bypasses the need to move money to a bank account first. However, users should be aware that Venmo may classify this as a card transaction, which could carry different implications than a direct bank transfer, especially regarding transaction limits.

Method 3: The Venmo Mastercard Integration
Conversely, you can add your Venmo Debit Card to your PayPal wallet. This is particularly useful for users who keep a significant balance in Venmo and want to use those funds at online retailers where Venmo isn’t an option but PayPal is. By adding the Venmo card as a funding source in PayPal, you create a direct “spend” link from Venmo to the wider world of PayPal merchants.
Optimizing Cash Flow for Freelancers and Gig Workers
For the self-employed, the distinction between PayPal and Venmo often represents the line between professional and personal life. Many freelancers use PayPal to invoice clients because of its professional layout and detailed record-keeping. Meanwhile, they use Venmo for daily expenses.
Managing Business vs. Personal Liquidity
The “linking” of these accounts allows for a sophisticated “pay yourself” model. When a client pays an invoice on PayPal, a savvy freelancer will calculate their tax obligations and operating expenses, keeping those in the PayPal/Bank ecosystem, and then “link-transfer” the remaining personal draw to Venmo for discretionary spending. This creates a clear digital paper trail, which is invaluable during tax season.
The Impact of 1099-K Regulations
It is important to note that as the IRS moves toward lower thresholds for 1099-K reporting, both PayPal and Venmo are required to track “goods and services” payments. Linking these accounts doesn’t hide your income; rather, it allows you to centralize your reporting. By using a common bank account to bridge the two, you can more easily reconcile your annual earnings and ensure that you aren’t double-counting transfers between your own accounts as new income.
Security and Fee Structures: Protecting Your Assets
When you link financial platforms, you inherently increase your “attack surface.” If one account is compromised, a malicious actor might attempt to drain the connected accounts. Furthermore, the convenience of moving money between PayPal and Venmo can come at a cost if you aren’t careful with fee structures.
Prioritizing Security in a Linked Ecosystem
To maintain financial integrity when linking Venmo and PayPal, several precautions are mandatory:
-
Two-Factor Authentication (2FA): Enable 2FA on both platforms and the intermediary bank account. Use an authenticator app rather than SMS for better security.
-
Balance Minimums: Avoid keeping large sums of money in your PayPal or Venmo balances. These are not FDIC-insured bank accounts in the traditional sense. It is better to move funds through the link to your verified bank account as quickly as possible.
-
Notification Triggers: Set up instant alerts for any transfer out of PayPal or Venmo. This ensures that if a “link” is used without your permission, you can freeze the accounts immediately.
Navigating the Cost of Instant Transfers
The biggest pitfall of linking these platforms is the temptation of the “Instant Transfer.” Both PayPal and Venmo charge a percentage (typically around 1.75%, with minimums and maximums) to move money to a debit card instantly.
For a $1,000 transfer, you could lose $15–$17 simply for the sake of speed. Over the course of a year, these fees can erode your net worth significantly. A disciplined financial strategy involves planning ahead so you can utilize the “Standard Transfer” (ACH), which is free and typically takes 1–3 business days. By mastering the timing of your “link,” you save hundreds of dollars in convenience fees.
The Future of Unified Digital Finance
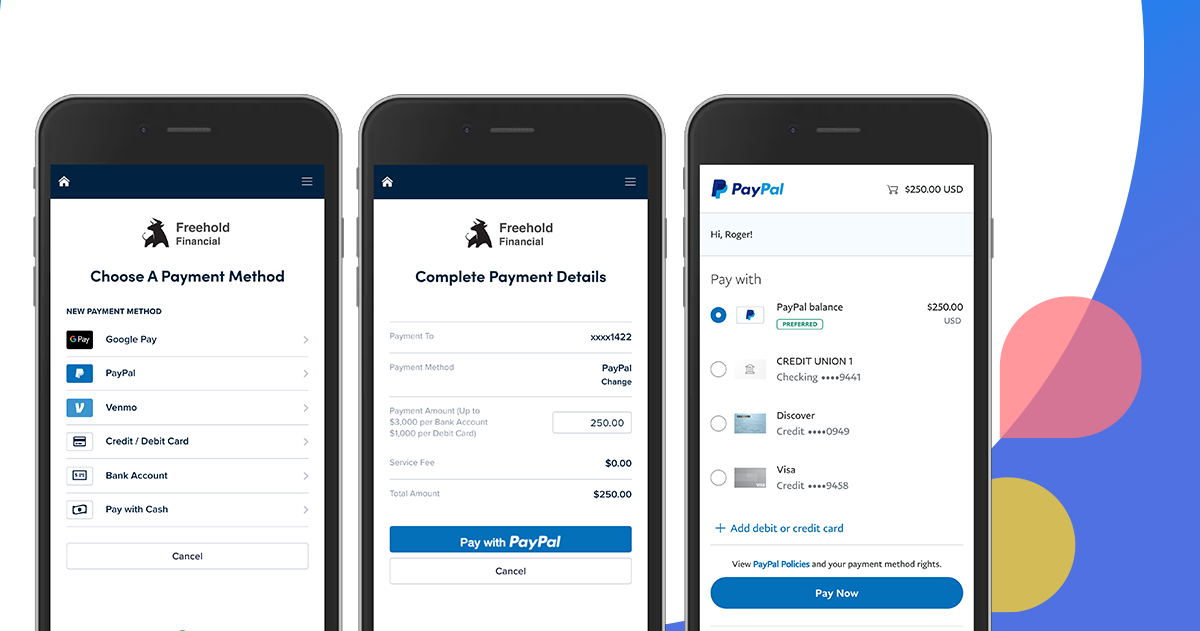
As PayPal Holdings continues to evolve, we are likely to see even tighter integration between Venmo and PayPal. We are already seeing “Pay with Venmo” buttons appearing at PayPal checkout screens, signaling a move toward a more frictionless internal exchange.
However, until a direct “Transfer to Venmo” button exists within the PayPal interface, the bank-hub method remains the gold standard for financial control. By understanding the flow of money from a professional gateway (PayPal) through a secure intermediary (Bank) to a social spending tool (Venmo), you empower yourself to manage your capital with the precision of a corporate treasurer.
Linking Venmo and PayPal is not just a technical task; it is a strategic move that enhances your financial agility. Whether you are a consumer looking to simplify your digital wallet or a freelancer managing a complex income stream, the ability to bridge these two platforms ensures that your money is always where you need it, when you need it, and at the lowest possible cost.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.