
For the vast majority of households, a vehicle represents the second largest financial investment after a primary residence. Yet, unlike a brokerage account or a savings balance, the value of an automobile is in a constant state of flux, influenced by a complex interplay of depreciation, market demand, and economic variables. Understanding how to check the value of your car is not merely a matter of curiosity; it is a fundamental component of proactive personal finance management. Whether you are planning to trade in your vehicle for a newer model, selling it to a private party to boost your investment capital, or simply updating your net worth statement, having an accurate grasp of your car’s current market value is essential for making informed fiscal decisions.
Leveraging Digital Valuation Tools and Financial Databases
The first step in any valuation process involves utilizing the robust digital tools that aggregate millions of data points from auctions, dealership sales, and private transactions. In the modern financial landscape, these platforms serve as the “Gold Standard” for establishing a baseline price.
The Big Three: KBB, J.D. Power, and Edmunds
Most financial advisors recommend starting with Kelley Blue Book (KBB), J.D. Power (formerly NADA Guides), and Edmunds. Each of these platforms uses a slightly different proprietary algorithm to determine value.
-
Kelley Blue Book is perhaps the most recognized name, offering a range of values based on the “Blue Book Value.” It provides specific figures for trade-in value, private party value, and typical listing price.
-
J.D. Power is often the preferred tool for lenders and credit unions. If you are looking to refinance an auto loan or determine how much a bank will lend against your car, this is the most relevant metric.
-
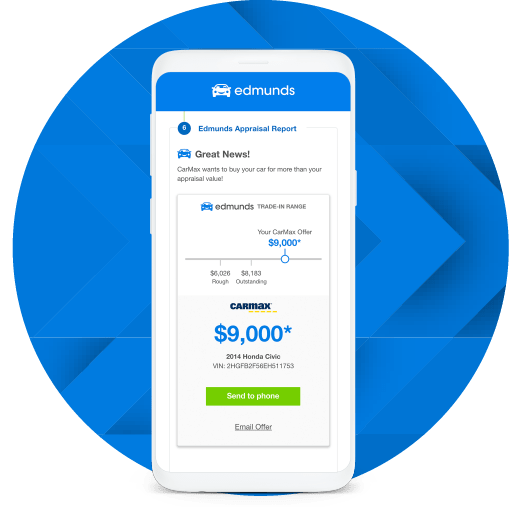
Edmunds provides a “True Market Value” (TMV) which often reflects the actual transaction price rather than the asking price, offering a more realistic view of what cash you might actually walk away with.
Understanding Value Definitions
When using these tools, you will encounter different categories of value. Distinguishing between them is critical for your financial planning.
-
Trade-In Value: This is the amount a dealer will offer you toward the purchase of another vehicle. It is typically the lowest figure because the dealer must account for reconditioning costs and a profit margin.
-
Private Party Value: This is what you can expect to receive if you sell the car yourself to another individual. This is usually significantly higher than the trade-in value but requires more effort and marketing.
-
Retail Value: This is the price at which a dealer would list the car on their lot. You will rarely receive this amount as a seller, but it is useful for insurance purposes to know the replacement cost.
The Role of Real-Time Online Buyers
In recent years, the rise of “instant offer” platforms like Carvana, Vroom, and CarMax has changed the valuation landscape. By entering your Vehicle Identification Number (VIN) or license plate into these sites, you receive a concrete, time-bound cash offer. Unlike the estimates from KBB, these are actual liquid offers. In a fast-moving economy, these platforms often provide the most accurate “floor” for your car’s value—the absolute minimum you should accept in any transaction.
Understanding the Variables That Impact Financial Worth
A car is a depreciating asset, but the rate of that depreciation is not uniform. To accurately check your car’s value, you must perform an honest assessment of its specific condition and the external factors affecting its desirability.
The Depreciation Curve and Mileage
Depreciation is the single largest “hidden” cost of vehicle ownership. Most cars lose about 20% of their value in the first year and roughly 15% each year thereafter until they hit a plateau. Mileage is the primary driver of this curve. In the financial world, certain mileage milestones act as psychological barriers for buyers. A car with 98,000 miles is often perceived as significantly more valuable than one with 102,000 miles, simply because it hasn’t crossed the six-figure threshold. When checking your value, look at how your current mileage compares to the average of 12,000 to 15,000 miles per year.
Condition Ratings: A Financial Reality Check
One of the most common mistakes in vehicle valuation is overestimating the car’s condition. Online tools usually offer categories: Excellent, Very Good, Good, and Fair.
-
Excellent: This usually applies to fewer than 5% of all used vehicles. It means the car looks and runs like new, with no mechanical or cosmetic defects.
-
Good/Very Good: This is where most well-maintained vehicles fall. There may be minor wear, but no major repairs are needed.
-
Fair: This category is for vehicles with significant cosmetic issues or mechanical needs that are still drivable.
Choosing “Excellent” when your car is actually “Good” can lead to a valuation discrepancy of several thousand dollars, which can derail your budgeting for a new purchase.

The Impact of Options and Maintenance Records
While base models provide the foundation for value, specific “add-ons” can influence the final number. Safety features, upgraded technology packages, and premium sound systems often retain a portion of their value. Conversely, aftermarket modifications—such as custom paint, oversized rims, or performance chips—often decrease the value or shrink the pool of potential buyers. Furthermore, a documented service history is a financial asset. A vehicle with a complete “paper trail” of oil changes and scheduled maintenance can often command a 5% to 10% premium over an identical vehicle with no records.
Strategic Timing and Market Dynamics
Checking the value of your car is not a one-time event; it is a snapshot of a moving target. The broader economy and seasonal trends play a massive role in what your asset is worth at any given moment.
Seasonal Fluctuations and Regional Demand
The value of your car can change based on the weather and the calendar. Convertibles and sports cars typically see a value spike in the spring and summer, whereas all-wheel-drive SUVs and trucks become more valuable as winter approaches. Additionally, geography matters. A rear-wheel-drive sedan is worth more in Florida than it is in a mountainous region of Colorado. Financial tools often ask for your zip code for this very reason; they are adjusting for local supply and demand.
Economic Indicators: Fuel Prices and Interest Rates
The macro-economy dictates the “opportunity cost” of your vehicle. When fuel prices spike, the value of large, inefficient SUVs tends to drop, while the value of hybrids and electric vehicles (EVs) increases. Similarly, interest rates influence your car’s value indirectly. When interest rates on new car loans are high, more consumers enter the used car market, driving up the value of existing vehicles. Monitoring these trends allows you to time your “exit” from a vehicle to maximize your return.
The “New Model” Effect
When a manufacturer releases a completely redesigned version of your car, the value of the previous generation often takes a sudden hit. This is known as “model year depreciation.” If you are checking your car’s value and notice a redesign is imminent, it may be financially prudent to sell or trade-in before the new model hits the showroom floors.
Integrating Vehicle Value into Your Personal Finance Strategy
Once you have determined the value of your car, the next step is to apply that data to your broader financial goals. Your car’s value is a key metric in several financial calculations.
Calculating Equity vs. Debt
If you have an outstanding auto loan, the most important figure is your “equity position.” This is calculated by taking the current market value of the car and subtracting your remaining loan balance. If your car is worth $20,000 and you owe $15,000, you have $5,000 in equity—a positive asset. However, if you owe $25,000 on a car worth $20,000, you are “underweight” or “upside down.” Knowing this allows you to decide whether to accelerate loan payments or adjust your insurance coverage.
Insurance and Risk Management
Checking your car’s value is essential for ensuring you are neither under-insured nor over-insured. If your vehicle has depreciated significantly, you might consider dropping “collision” or “comprehensive” coverage if the annual premium exceeds a significant percentage of the car’s total value. Conversely, if your car is a rare model that has appreciated (as seen in some enthusiast markets), you may need an “agreed value” policy to protect your investment properly.
Net Worth Tracking
For those who track their net worth monthly or quarterly, using a conservative “Private Party” value for your vehicle provides a realistic view of your liquidity. While a car is not as liquid as cash or stocks, it is a significant part of your “Total Assets” column. Keeping this number updated ensures that your financial statements reflect reality, providing a clearer picture of your overall financial health.
By systematically using digital tools, honestly assessing the condition of the vehicle, and understanding the external market forces at play, you can confidently answer the question, “How much is my car worth?” This knowledge transforms your vehicle from a mysterious expense into a managed financial asset, allowing you to navigate the complexities of the automotive market with the precision of a seasoned investor.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.