
The dream of entrepreneurship beckons many, promising autonomy, innovation, and the potential for significant financial reward. Yet, transforming a brilliant idea into a thriving commercial enterprise is a journey paved with crucial decisions, paramount among which are those concerning finance. Setting up a business isn’t merely about having a product or service; it’s fundamentally about understanding and managing the economic machinery that makes it viable. This guide will delve into the essential financial considerations, strategies, and systems necessary to successfully launch and sustain your entrepreneurial venture within the Money niche.
Laying the Financial Foundation: Essential Pre-Launch Steps
Before any tangible product is built or service offered, a robust financial foundation must be meticulously constructed. This phase is critical for understanding market viability, estimating costs, and projecting potential income.
Idea Validation and Market Research (Financial Lens)
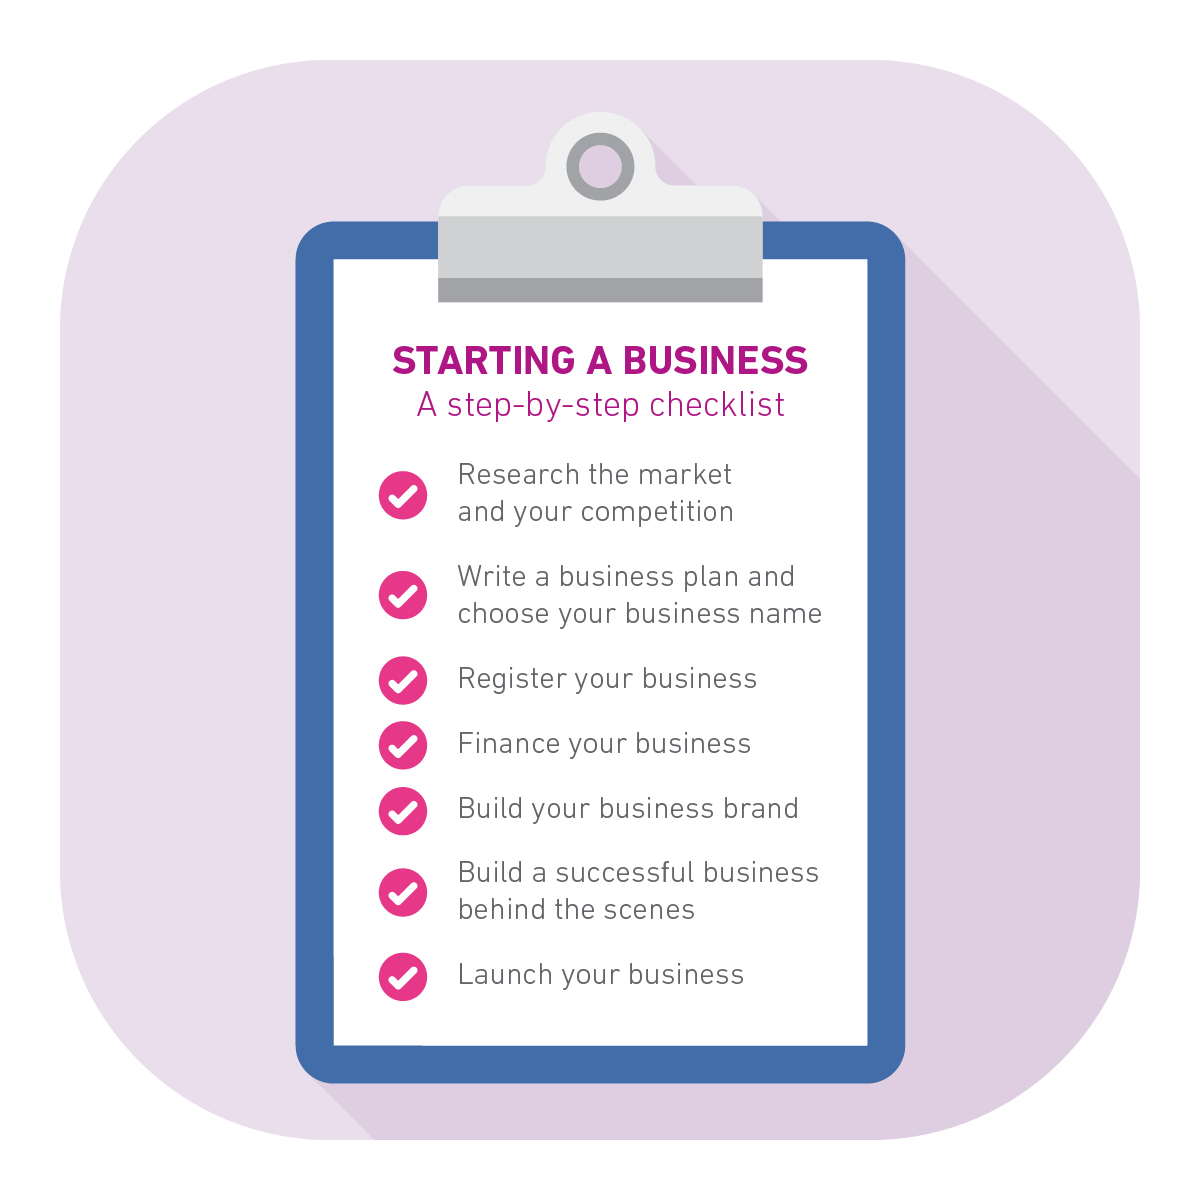
Every successful business addresses a specific market need, and the first financial step is to ascertain if customers are willing to pay for your solution. Financial market research involves more than just identifying target demographics; it means evaluating the economic landscape. Are there enough potential paying customers to justify your investment? What is the current pricing structure for similar products or services in the market, and how does your proposed pricing strategy compare? Understanding competitor pricing, customer willingness to pay, and the overall market size directly informs your potential revenue streams and helps validate the financial viability of your idea. This stage minimizes the risk of investing time and capital into an unmarketable concept.
Crafting a Robust Business Plan (The Financial Blueprint)
A business plan serves as your venture’s financial roadmap, guiding every decision from startup capital to profit distribution. Within the Money niche, the financial section of this plan is paramount. It should include:
-
Startup Costs: A detailed breakdown of every initial expense, from legal fees and permits to equipment purchases, initial inventory, and website development. Underestimating these can lead to critical funding shortfalls.
-
Operational Expenses: Projecting ongoing monthly costs such as rent, utilities, salaries, marketing budget, raw materials, and software subscriptions. Differentiating between fixed and variable costs is crucial for budgeting flexibility.
-
Revenue Forecasts: Realistic projections of sales volume and pricing over the first 1-3 years. This should be supported by your market research and consider different scenarios (optimistic, realistic, pessimistic).
-
Break-Even Analysis: Calculating the point at which your total revenues equal your total costs. Knowing this number is vital for setting early sales targets and understanding when your business will become profitable.
-
Cash Flow Projections: A forecast of money coming in and out of your business, ensuring you have enough liquidity to cover expenses at all times, especially during initial growth phases. This is often the lifeblood of a new business.
This financial blueprint not only provides clarity for you but is also indispensable when seeking external funding from lenders or investors.
Legal Structure and Registration (Cost Implications)
The legal structure you choose for your business has significant financial and tax implications. Common options include:
-
Sole Proprietorship: Simple and inexpensive to set up, but offers no personal liability protection, meaning your personal assets are at risk. Taxed as personal income.
-
Limited Liability Company (LLC): Offers personal liability protection for owners and pass-through taxation (profits/losses reported on personal tax returns). Setup costs are higher than a sole proprietorship, varying by state.
-
Corporation (S-Corp, C-Corp): Provides the strongest liability protection but involves more complex setup, ongoing compliance, and often higher administrative costs. C-Corps are subject to “double taxation” (corporate profits taxed, then dividends taxed again at the shareholder level), while S-Corps avoid this by passing profits/losses directly to owners’ personal income.
Beyond the initial formation costs, you’ll need to account for fees associated with obtaining necessary business licenses and permits, which vary widely depending on your industry and location. Consulting with a legal and financial professional at this stage can prevent costly mistakes down the line.
Funding Your Venture: Capitalizing Your Dream
Once your financial plan is in place, the next critical step is securing the capital needed to bring your business to life. Financing options vary widely, each with its own advantages, disadvantages, and financial implications.
Self-Funding (Bootstrapping)
Many entrepreneurs begin by self-funding, or “bootstrapping,” their ventures. This involves using personal savings, credit cards (with caution due to high-interest rates), or loans from friends and family. The primary advantage of bootstrapping is maintaining complete ownership and control over your business, avoiding the dilution of equity or the obligation of debt repayment to external parties. However, it can limit the speed and scale of growth due to constrained capital, and carries significant personal financial risk if the business fails. For many, a side hustle that generates initial income before going full-time is an excellent bootstrapping strategy.
Debt Financing
Debt financing involves borrowing money that must be repaid, typically with interest, over a specified period. This is a common route for established businesses, but also available to startups with a solid business plan and good personal credit.
-
Small Business Loans: Offered by banks and financial institutions, often backed by government agencies like the Small Business Administration (SBA) in the U.S. SBA loans can offer more flexible terms and lower down payments but require a rigorous application process and a strong business plan.
-
Lines of Credit: Provide access to a revolving credit pool, useful for managing cash flow fluctuations or covering unexpected expenses. Interest is usually paid only on the amount drawn.
-
Microloans: Smaller loans (typically under $50,000) offered by non-profit organizations to underserved entrepreneurs, often with more flexible eligibility criteria than traditional bank loans.
While debt financing allows you to retain full ownership, it introduces fixed repayment obligations that can strain cash flow if revenues are slow to materialize.
Equity Financing
Equity financing involves selling a portion of your company’s ownership in exchange for capital. This is often pursued by high-growth startups seeking substantial funding without the burden of immediate loan repayments.
-
Angel Investors: High-net-worth individuals who invest their own money in early-stage startups, often providing mentorship alongside capital.
-
Venture Capitalists (VCs): Firms that invest institutional money in companies with high growth potential, typically in exchange for significant equity stakes and often seats on the board of directors.
-
Seed Funding: The earliest stage of equity investment, often from angel investors or small VC firms, to help a startup prove its concept and develop its initial product.
The major trade-off with equity financing is the dilution of ownership and control. However, it can provide significant capital infusions and invaluable expertise, propelling rapid growth that might not be possible with debt or self-funding alone.
Grants and Crowdfunding
-
Grants: Non-repayable funds, typically offered by government agencies, foundations, or corporations to businesses that meet specific criteria (e.g., innovation, social impact, specific industries). They are highly competitive and often require detailed proposals.
-
Crowdfunding: Platforms like Kickstarter or Indiegogo allow businesses to raise small amounts of money from a large number of people.
-
Reward-based crowdfunding: Pre-selling products or offering unique experiences in exchange for financial pledges. This is excellent for validating demand and generating initial sales.
-
Equity crowdfunding: Selling small equity stakes to individual investors, often through regulated online platforms.
-
These options can be powerful, but require compelling storytelling and significant marketing effort to attract funders.
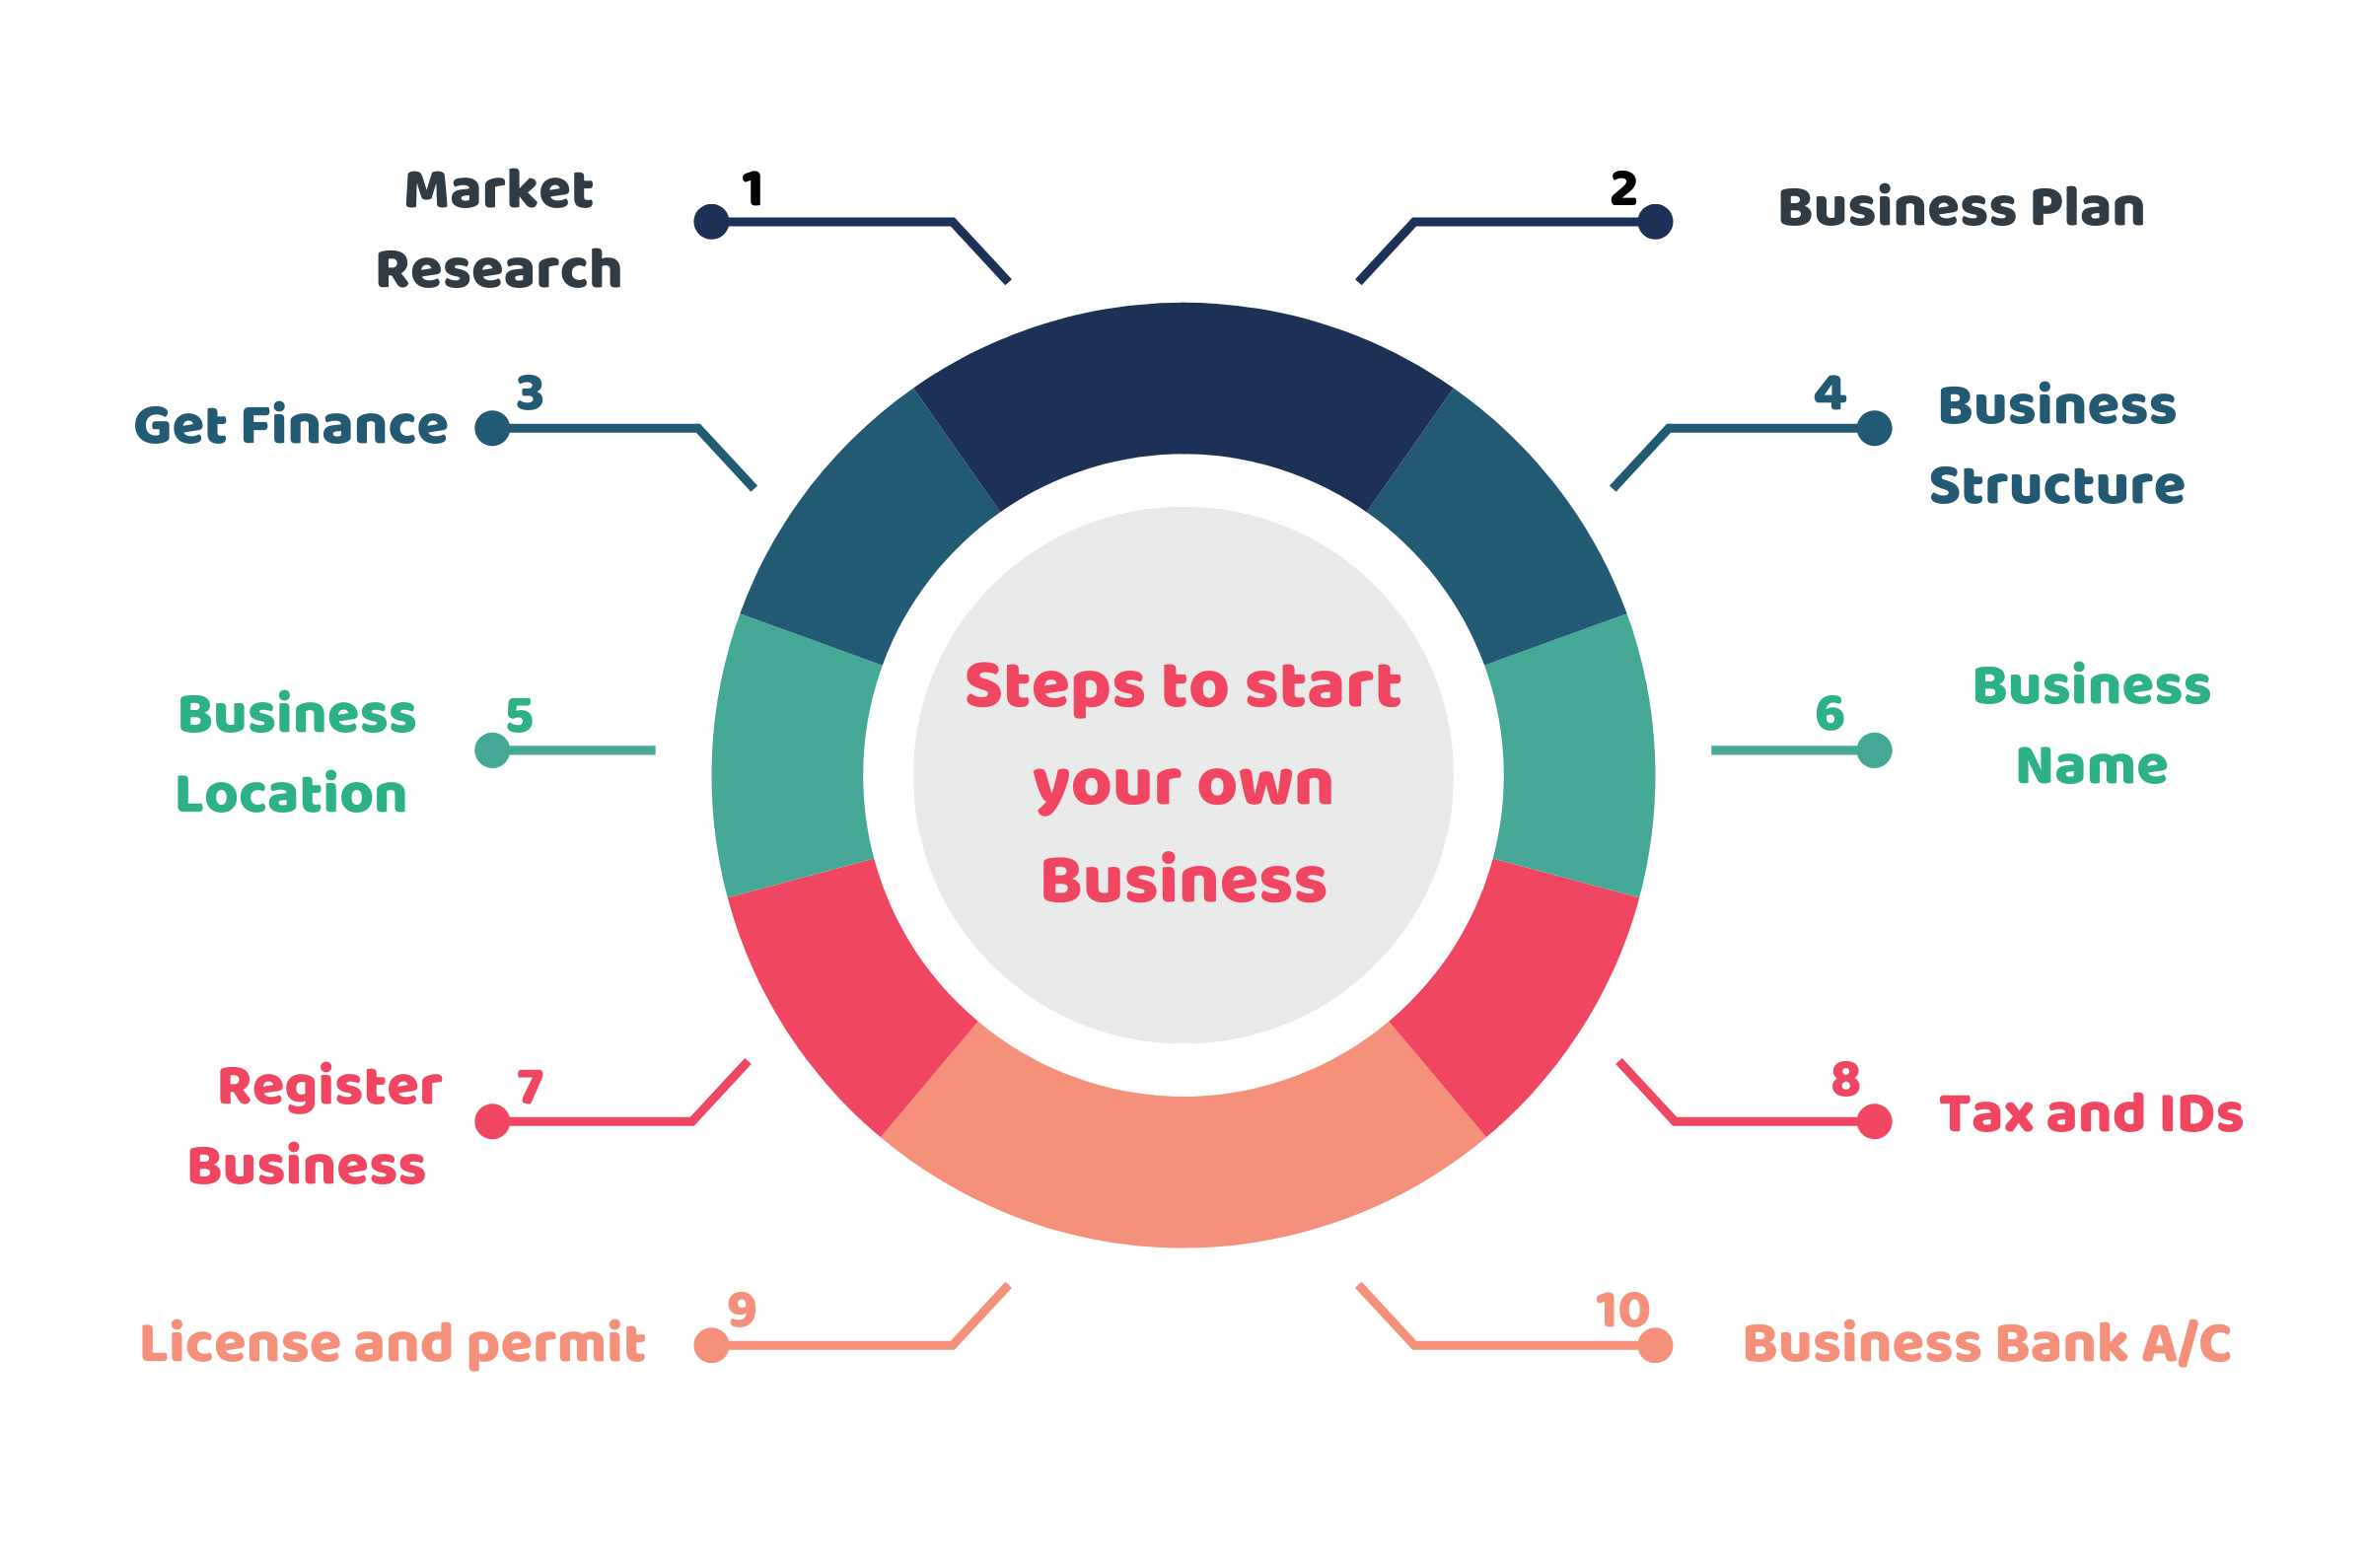
Managing Business Finances: Sustaining Growth
Securing capital is just the beginning; effective financial management is the bedrock of long-term business survival and growth. Without diligent oversight, even a well-funded venture can quickly run into solvency issues.
Setting Up Financial Systems
The first step is to establish clear boundaries between personal and business finances.
-
Business Bank Accounts: Open separate checking and savings accounts for your business. This simplifies accounting, tax preparation, and presents a professional image.
-
Accounting Software: Implement robust accounting software (e.g., QuickBooks, Xero, FreshBooks) from day one. These tools streamline invoicing, expense tracking, budgeting, payroll, and financial reporting, providing real-time insights into your financial health.
-
Payment Processing: Set up reliable payment processing solutions (e.g., Stripe, PayPal, Square) to accept payments from customers efficiently and securely, whether online or in-person. Understanding associated transaction fees is crucial for accurate pricing.
Budgeting and Expense Control
A meticulously crafted budget is your primary tool for financial control. It details anticipated income and expenses, allowing you to allocate resources effectively and monitor spending.
-
Create and Adhere to a Budget: Regularly review your budget against actual expenditures. This proactive approach helps identify areas of overspending before they become critical.
-
Identify Fixed vs. Variable Costs: Understand which costs remain constant (rent, insurance) and which fluctuate with sales volume (raw materials, shipping). This knowledge empowers better forecasting and cost-cutting strategies.
-
Cost Reduction Strategies: Continuously seek opportunities to reduce expenses without compromising quality or operational efficiency. This could involve negotiating with suppliers, optimizing workflows, or leveraging technology.
Effective expense control directly impacts your profitability and cash flow, ensuring you have enough capital to reinvest in growth or weather lean periods.
Pricing Strategies and Revenue Management
How you price your products or services directly impacts your revenue and perceived value.
-
Cost-Plus Pricing: Adding a markup percentage to the cost of production. Simple but may not reflect market value.
-
Value-Based Pricing: Setting prices based on the perceived value to the customer, often allowing for higher margins.
-
Competitive Pricing: Benchmarking prices against competitors, useful in saturated markets.
-
Subscription Models: For services or software, subscription models provide predictable recurring revenue, aiding financial forecasting.
-
Cash Flow Monitoring: Regularly review your cash flow statements to understand the movement of money. Positive cash flow is essential for paying bills and investing in future growth, even if your business is technically profitable on paper.
Tax Planning and Compliance
Navigating the complexities of business taxes is a non-negotiable aspect of financial management.
-
Understand Business Taxes: Familiarize yourself with federal, state, and local income taxes, sales taxes, payroll taxes, and self-employment taxes applicable to your business structure and industry.
-
Quarterly Estimated Payments: Many small businesses are required to pay estimated taxes quarterly rather than annually to avoid penalties.
-
Professional Assistance: Engage a qualified accountant or tax advisor from the outset. Their expertise can ensure compliance, identify legitimate deductions, and optimize your tax strategy, saving you significant money and stress.
Scaling and Financial Exit Strategies (Long-term Money Focus)
A successful business is not just about starting; it’s about sustaining and eventually monetizing the value you’ve created. This requires strategic long-term financial thinking.
Reinvesting Profits for Growth
Once your business achieves profitability, a crucial financial decision is how to allocate those earnings. Smart entrepreneurs strategically reinvest a portion of their profits back into the business to fuel further growth. This could mean:
-
Expanding Marketing Efforts: Allocating funds to acquire more customers, increasing your reach and revenue potential.
-
Research & Development: Investing in new product lines, service enhancements, or technological improvements to stay competitive.
-
Operational Expansion: Funding new equipment, larger facilities, or hiring additional staff to meet growing demand.
Understanding the Return on Investment (ROI) for these reinvestments is key to making financially sound decisions that genuinely propel the business forward rather than merely consuming profits.
Managing Debt and Equity Dilution
As your business grows, you might require additional funding, potentially leading to further debt or equity rounds. Strategically managing these is vital:
-
Debt Management: While debt can fuel expansion, excessive leverage can make a business vulnerable during economic downturns. Maintain a healthy debt-to-equity ratio and ensure debt service payments are manageable within your cash flow projections.
-
Equity Dilution: Each round of equity financing reduces the founders’ ownership stake. While necessary for growth, strategic planning (e.g., ensuring high valuations in later rounds, using convertible notes) can help minimize dilution and preserve founder control and future financial upside.
Balancing growth objectives with financial prudence is a continuous challenge that defines long-term financial success.

Planning for the Future: Exit Strategies
Every business will eventually transition, and having a financially sound exit strategy provides a clear long-term goal for value creation.
-
Selling the Business: This is a common exit for many entrepreneurs. Building a business that is financially robust, scalable, and not overly reliant on the owner makes it an attractive acquisition target. Preparing for a sale involves meticulous financial record-keeping, due diligence, and often, professional valuation.
-
Succession Planning: Passing the business on to family members or employees requires careful financial planning to ensure a smooth transition of ownership, management, and financial control, often involving trust funds or staged buyouts.
-
Initial Public Offering (IPO): While rare for most small businesses, going public involves selling shares to the general public on a stock exchange. This is a complex, costly, and highly regulated process for very high-growth companies, offering significant capital but also intense scrutiny and public accountability.
Understanding potential exit strategies informs how you build and manage the financial value of your company from its inception.
Setting up a business is an exciting endeavor that requires far more than just a great idea; it demands a deep understanding and unwavering commitment to financial prudence. From meticulously planning your startup costs and securing appropriate funding to diligently managing your day-to-day cash flow and strategizing for long-term growth and eventual exit, every step is underpinned by financial considerations. By embracing the principles of sound financial management, aspiring entrepreneurs can transform their vision into a financially sustainable and successful enterprise, achieving both personal autonomy and economic prosperity.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.