
In the landscape of American finance, few names carry as much historical weight or market presence as Wells Fargo & Company. As a member of the “Big Four” American banks—alongside JPMorgan Chase, Bank of America, and Citigroup—Wells Fargo is a cornerstone of the global economy. For the individual consumer, the small business owner, and the institutional investor, understanding who Wells Fargo is requires a deep dive into its multifaceted operations, its influence on the credit markets, and its role as a primary provider of financial tools and services.
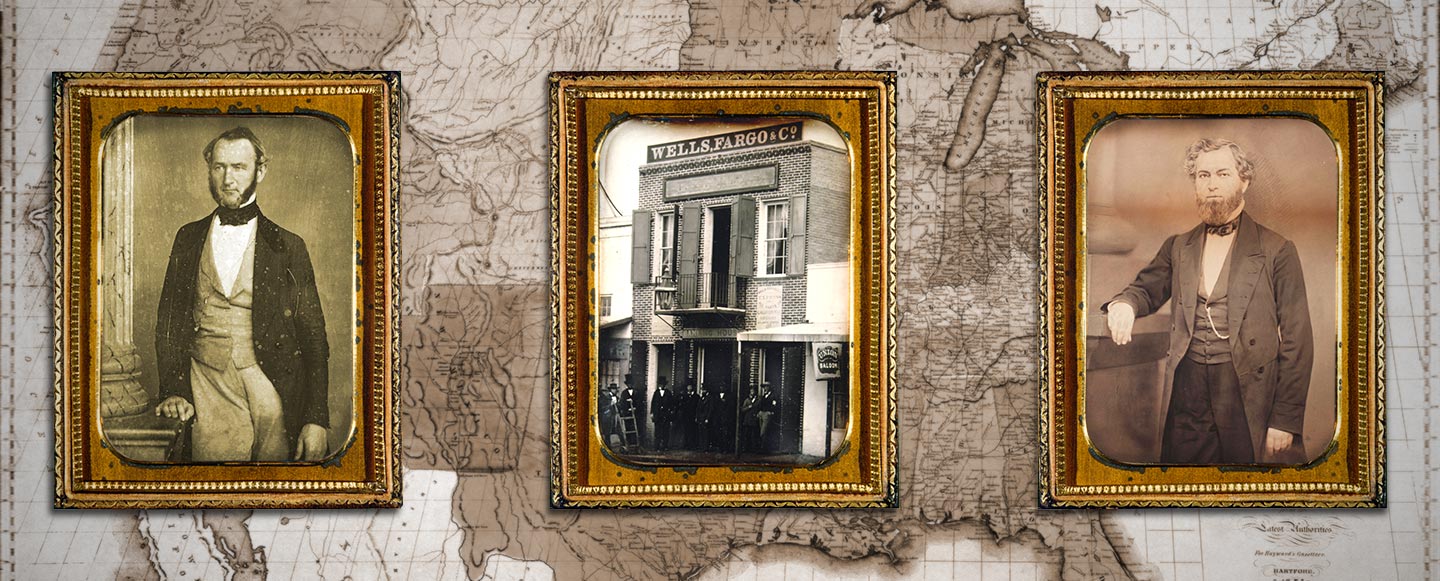
Wells Fargo is a diversified, community-based financial services company with approximately $1.9 trillion in assets. While it is often recognized by its iconic stagecoach logo—a nod to its 1852 origins—today’s Wells Fargo is a high-tech powerhouse driving millions of transactions daily. It operates through four primary segments: Consumer Banking and Lending; Commercial Banking; Corporate and Investment Banking; and Wealth and Investment Management. By analyzing these pillars, we can better understand how the institution shapes personal finance and corporate liquidity in the 21st century.
A Pillar of the American Financial Infrastructure
Wells Fargo’s primary identity is that of a systemically important financial institution (SIFI). This designation means that the bank is so integrated into the economy that its stability is paramount to the health of the broader financial system. For the average person, this translates to a level of security and accessibility that few other institutions can match.
Retail Banking and Consumer Reach
The core of Wells Fargo’s business is its consumer banking division. With thousands of branches and one of the largest ATM networks in the United States, it provides the essential plumbing for personal finance. This segment includes everything from basic checking and savings accounts to complex mortgage products. By holding a significant portion of American deposits, Wells Fargo acts as a massive repository of capital, which it then redeploys into the economy through consumer loans and community reinvestment.
The Power of Mortgage Lending
Historically, Wells Fargo has been a dominant force in the U.S. mortgage market. For decades, it was the largest retail mortgage lender in the country. While the bank has recently shifted its strategy to focus more on existing customers and underserved communities, its influence on homeownership remains profound. By setting standards for creditworthiness and interest rates, Wells Fargo helps dictate the accessibility of the American Dream. Their mortgage servicing portfolios remain among the largest in the world, meaning even if a consumer didn’t get their loan directly from Wells Fargo, there is a high probability that Wells Fargo manages the payments and escrow for that loan.
Commercial and Corporate Banking
Beyond the individual consumer, Wells Fargo is a vital partner for the business sector. Their Commercial Banking segment serves middle-market companies, providing them with the working capital needed to expand operations, hire employees, and innovate. This involves sophisticated treasury management services, asset-based lending, and international trade financing. For the “Money” niche, this is where the bank fuels the engine of the economy, ensuring that businesses have the liquidity to navigate different economic cycles.
The Diverse Ecosystem of Financial Services
To answer “Who is Wells Fargo” is to look at the sheer breadth of their financial product suite. The bank is not merely a place to store cash; it is a full-service financial ecosystem designed to capture every stage of a customer’s financial life cycle.
Credit Cards and Personal Credit Lines
Wells Fargo has aggressively expanded its credit card portfolio in recent years, launching competitive rewards programs like the “Autograph” and “Active Cash” series. These products are designed to compete with fintech disruptors and other major issuers. By offering high-yield rewards and robust digital security features, the bank attracts a diverse demographic of spenders. From a personal finance perspective, these tools are essential for building credit history and managing short-term cash flow.
Small Business Support
The bank is one of the leading providers of Small Business Administration (SBA) loans. For entrepreneurs, Wells Fargo acts as a bridge between a startup idea and a viable commercial enterprise. Their small business tools include specialized checking accounts, merchant services for processing payments, and business-specific credit cards. This focus on the “SME” (Small and Medium Enterprise) sector is a critical part of their identity, as they support the segment of the economy that generates the most jobs.
Corporate and Investment Banking (CIB)
While many associate Wells Fargo with local branches, their Corporate and Investment Banking arm competes on a global scale. They provide capital markets services, including debt and equity underwriting, and advisory services for mergers and acquisitions. This allows them to service massive corporations and institutional investors, providing the sophisticated financial engineering required for multi-billion dollar deals. This segment highlights the bank’s evolution from a regional lender to a global financial powerhouse.
Innovative Wealth Management and Investment Strategies

One of the most significant aspects of Wells Fargo’s modern identity is its role as an investment advisor. Through Wells Fargo Advisors and its private bank, the institution manages trillions of dollars in client assets, making it one of the largest wealth management firms in the United States.
The Role of Wells Fargo Advisors
This division serves a wide spectrum of investors, from those just starting their retirement journey to high-net-worth individuals requiring complex estate planning. They offer a “full-service” model where clients work with financial advisors to create personalized investment strategies. This includes access to proprietary research, mutual funds, and alternative investments. In the context of “Investing” and “Personal Finance,” this segment is crucial because it helps individuals navigate the complexities of the stock and bond markets.
Digital Investing and Intuitive Tools
Recognizing the shift toward self-directed investing, Wells Fargo has integrated digital brokerage tools into its core platform. Their “Intuitive Investor” service is a robo-advisor designed for those who want a professional portfolio management experience at a lower cost. This tool uses algorithms to rebalance portfolios and optimize tax efficiency, reflecting how the bank is merging traditional financial wisdom with modern software.
Retirement Planning and Trust Services
Wells Fargo is deeply embedded in the retirement sector, managing 401(k) plans for corporations and providing Individual Retirement Accounts (IRAs) for consumers. Their trust services also ensure that wealth is transitioned between generations effectively. By providing these long-term financial tools, the bank establishes a multi-generational relationship with its clients, reinforcing its position as a life-long financial partner.
Navigating Modern Personal Finance via Digital Integration
In the current era, a bank is defined as much by its software as by its vaults. Wells Fargo has undergone a massive digital transformation to ensure that its “Money” services are available 24/7 through mobile and web applications.
The Mobile Banking Revolution
The Wells Fargo mobile app is the primary touchpoint for millions of users. It integrates advanced budgeting tools, credit score monitoring, and Zelle for peer-to-peer payments. For the modern consumer, this app is the command center for their personal finance. Features like “LifeSync” allow users to set specific financial goals—such as buying a home or saving for a vacation—and track their progress in real-time. This focus on “Financial Tools” demonstrates the bank’s commitment to improving the financial health of its users through technology.
Cybersecurity and Digital Security
As a major financial target, Wells Fargo invests billions annually in digital security. This includes multi-factor authentication, biometric logins, and advanced encryption. From a “Digital Security” perspective, the bank’s ability to protect its customers’ assets is a core part of its value proposition. They provide customers with tools to freeze cards instantly and receive real-time alerts for suspicious activity, which is essential in an era of increasing online fraud.
Artificial Intelligence in Banking
Wells Fargo has introduced “Fargo,” an AI-powered virtual assistant. Fargo helps users navigate the app, provides insights into spending habits, and can even answer complex questions about account balances or transaction history. By leveraging AI, Wells Fargo is making personal finance more proactive rather than reactive, helping users identify potential savings or alerting them to upcoming bills before they become a problem.
Institutional Governance and the Future of the Enterprise
To fully answer who Wells Fargo is, one must acknowledge its journey through regulatory scrutiny and its subsequent focus on institutional resilience. The bank has spent the last several years under a “Consent Order” from the Federal Reserve, which capped its growth until it improved its risk management and internal controls.
The Path to Restoration
Under leadership that took over in the late 2010s, Wells Fargo has undergone a total cultural and operational overhaul. The focus shifted from aggressive sales targets to “doing what’s right for the customer.” This involved streamlining the business, divesting non-core assets (like their student loan and rail leasing businesses), and reinvesting in compliance. For the investor, this signifies a bank that is becoming leaner, more focused, and more stable.
Corporate Social Responsibility and ESG
Wells Fargo has also committed to significant Environmental, Social, and Governance (ESG) goals. They have pledged to reach net-zero greenhouse gas emissions by 2050 and have allocated billions to sustainable finance and community lending. In the “Money” niche, this is an important trend to watch, as institutional investors increasingly favor companies that prioritize long-term sustainability alongside profitability.
The Economic Outlook
As interest rates fluctuate and the global economy faces uncertainty, Wells Fargo remains a bellwether for the financial sector. Its quarterly earnings reports are closely watched by analysts as an indicator of consumer health and corporate sentiment. Because it touches so many parts of the economy—from the car loan of a first-time buyer to the multi-million dollar credit line of a tech startup—the bank’s performance is a reflection of the broader economic landscape.
In conclusion, Wells Fargo is more than just a bank; it is a sprawling financial engine that provides the tools, capital, and expertise necessary for modern economic life. Whether through a simple checking account, a sophisticated investment portfolio, or a large-scale corporate loan, it remains an indispensable fixture in the world of money. Its ongoing evolution through digital innovation and regulatory discipline ensures that it will continue to define the American financial experience for decades to come.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.