
Determining the asking price for a vehicle is more than a simple estimation; it is a calculated financial maneuver. For most individuals, a vehicle represents one of the largest depreciating assets in their portfolio. Consequently, the process of pricing that asset for liquidation requires a deep understanding of market dynamics, valuation metrics, and the psychological levers of negotiation. Whether you are looking to reinvest the proceeds into a new vehicle or liquidating the asset to increase your cash reserves, precision in pricing is the difference between a swift, profitable transaction and a stale listing that costs you time and money.
Understanding Market Valuation and the Financial Lifecycle of a Vehicle
To price a car effectively, one must first view the vehicle through the lens of a financial analyst. A car is not merely a mode of transportation; it is a commodity subject to the laws of supply, demand, and depreciation. Understanding the lifecycle of your vehicle’s value is the foundation of a successful sale.
Depreciation: The Silent Cost of Ownership
Depreciation is the most significant expense of vehicle ownership, often exceeding the costs of fuel, insurance, and maintenance combined. From a financial perspective, most vehicles lose approximately 15% to 20% of their value each year. However, this curve is not linear. The “steepest” drop occurs the moment a new car leaves the lot, followed by another significant dip around the three-year and five-year marks, often coinciding with the expiration of manufacturer warranties.
When pricing your car, you must assess where your vehicle sits on this depreciation curve. A car that has just exited its warranty period may require a more competitive price to offset the buyer’s perceived risk of future repair costs. Conversely, a vehicle that has already “bottomed out” in depreciation—typically older models with high reliability—can often be priced with more stability, as their value is tied more to utility than to age.
Factors Influencing Residual Value
The residual value—the estimated value of the asset at the end of a specific period—is influenced by several variables that you must quantify. These include mileage, condition, and localized demand.
Mileage is perhaps the most quantifiable metric. In the financial world of automotive sales, there are “psychological milestones”—such as 36,000, 60,000, and 100,000 miles. Pricing a car with 98,000 miles is significantly different from pricing one with 102,000 miles, even though the mechanical difference is negligible. The six-figure mark often triggers a shift in buyer financing options, as many lenders increase interest rates for high-mileage vehicles, effectively reducing your pool of buyers and lowering the price you can realistically demand.
Quantitative Research: Using Financial Tools and Data Aggregators
In the modern marketplace, data is your greatest ally. Relying on “gut feeling” or what a neighbor sold their car for three years ago is a recipe for financial loss. You must utilize the same tools that dealerships and insurance companies use to assess value.
Leveraging Online Valuation Tools
There are three primary benchmarks in the United States: Kelley Blue Book (KBB), Edmunds, and J.D. Power (formerly NADA). Each uses a slightly different algorithm to determine value.
-
Kelley Blue Book: Often seen as the industry standard for consumer-facing prices. It provides a “Fair Purchase Price” based on actual transactions.
-
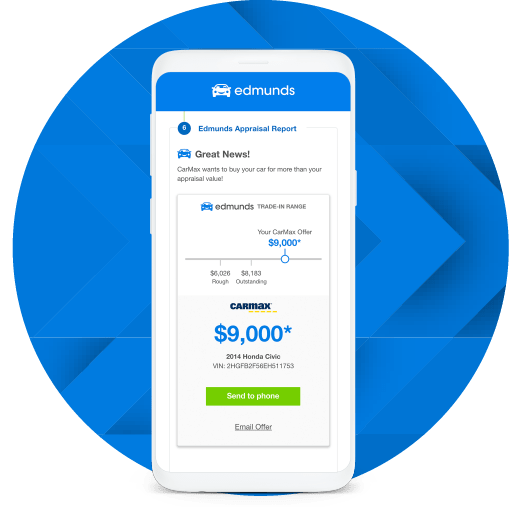
Edmunds: Known for its “True Market Value” (TMV) tool, which factors in historical data and current localized trends.
-
J.D. Power/NADA: Frequently used by credit unions and banks to determine loan values. This is crucial because if you price your car higher than the NADA “Clean Retail” value, your buyer may struggle to secure financing, potentially killing the deal.
When using these tools, be brutally honest about the vehicle’s condition. The “Excellent” category is reserved for the top 3% of vehicles. Most well-maintained cars fall into the “Good” or “Fair” categories. Overestimating condition in your initial research will lead to an inflated price that the market will eventually correct, often after weeks of zero inquiries.
Comparative Market Analysis (CMA) for Private Sales
While valuation tools provide a baseline, they operate on historical data. To understand the “Live Market,” you must perform a Comparative Market Analysis. This involves searching platforms like Autotrader, Cars.com, and Facebook Marketplace for vehicles of the same year, make, model, and trim level within a 50-to-100-mile radius.
Look for the “Ask vs. Sell” spread. The asking price is what a seller hopes to get; the selling price is what the market dictates. By observing how long certain listings stay active, you can identify “price ceilings”—points at which buyers refuse to engage. If a car identical to yours has been listed for $15,000 for three weeks without moving, your price should likely be $14,500 or lower to attract immediate interest.
Psychological Pricing and Negotiation Strategies
Pricing is as much about human psychology as it is about mathematics. Once you have determined the fair market value (FMV), you must decide how to present that number to the public to maximize your net return.
The Anchor Effect in Automotive Sales
In behavioral economics, “anchoring” describes the common human tendency to rely too heavily on the first piece of information offered. When you set your asking price, you are setting the anchor for the entire negotiation.
If your research suggests the car is worth $18,000, and you want to walk away with at least $17,500, you should not list it at $18,000. Instead, consider listing it at $18,900. This provides “negotiation padding.” It allows the buyer to feel they have “won” a concession when you drop the price to $18,000, while you still remain above your internal “floor” price. However, be careful not to anchor too high; if the price is outside the search filters of your target audience (e.g., someone filtering for “under $20,000”), you will lose visibility entirely.
Tiered Pricing and Room for Negotiation
Strategic pricing often utilizes “charm pricing”—the practice of ending a price in “900” or “950” rather than a round number. A car priced at $19,900 feels significantly cheaper than one at $20,000, even though the difference is only $100.
Furthermore, consider the “Cash Discount” strategy. If you are a private seller, you can often afford to price your vehicle lower than a dealership because you do not have the overhead of a showroom or sales staff. Highlighting this in your listing—essentially “passing the savings on to the buyer”—can justify a firm price. You are positioning the vehicle as a high-value asset at a wholesale price.
Tax Implications and Financial Considerations of the Sale
The final price you receive is not necessarily the “net” gain you keep. Several financial and legal factors can influence the total value of the transaction.
Trade-in Tax Credits vs. Private Sale Gains
One of the most overlooked aspects of pricing a car is the tax benefit of a dealership trade-in. In many jurisdictions, you only pay sales tax on the difference between the price of the new car and the trade-in value of the old one.
For example, if you are buying a $40,000 car and your trade-in is worth $20,000, you only pay sales tax on the remaining $20,000. If your state sales tax is 8%, that is a $1,600 savings. Therefore, to break even in a private sale, you would need to sell the car for $21,600. When pricing your car for a private sale, calculate this “tax delta” to ensure the extra effort of a private sale actually results in a higher net profit.
Capital Gains and Documentation for Personal Assets
While it is rare for a standard consumer vehicle to sell for more than its original purchase price, it does happen with classic cars or during unique market anomalies (such as the 2021-2022 used car surge). If you sell a vehicle for a profit, it is technically considered a capital gain by the IRS and must be reported.
Conversely, for most sellers, the “loss” on the sale of a personal vehicle is not tax-deductible. Regardless of the outcome, maintaining a clean financial paper trail—including the original bill of sale, maintenance records, and the final sale contract—is vital for your personal financial records and potential audits.
Timing the Market for Peak Financial Return
Just like the stock market, the automotive market has cycles. Your ability to price your car aggressively or conservatively should be informed by the current economic climate.
Seasonal Demand and Economic Cycles
The time of year significantly impacts the price you can command. Convertibles and sports cars see a price premium in the spring and early summer. Conversely, All-Wheel Drive (AWD) vehicles and SUVs command higher prices in late autumn and early winter.
Beyond seasonality, keep an eye on interest rates. When the Federal Reserve raises rates, the cost of financing a used car increases. This effectively lowers the purchasing power of your potential buyers. In a high-interest-rate environment, you may need to price your car more competitively to account for the increased monthly payment your buyer will face.

The Impact of New Model Releases
Finally, keep track of the manufacturer’s release schedule. When a new generation of your vehicle is released, the previous generation typically sees a measurable drop in value as it is no longer the “current” body style. If you know a new model is debuting in September, pricing and selling your car in July or August can save you thousands in “obsolescence depreciation.”
By treating the sale of your car as a strategic financial exit rather than a simple chore, you ensure that you extract the maximum possible value from the asset. Comprehensive research, psychological pricing, and an awareness of tax implications are the hallmarks of a sophisticated seller who understands that in the world of personal finance, every dollar of resale value counts.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.