
In the world of mathematics, the answer to “what is 1/4 + 1/4” is a simple 1/2. However, when translated into the language of wealth management, personal finance, and investment strategy, this basic equation represents the fundamental building blocks of a diversified portfolio. While the numerical result is 50%, the strategic result is the bridge between risk and security. In modern finance, understanding how to combine these “quarters” is the difference between a volatile gamble and a resilient financial future.
When we look at wealth through the lens of fractional components, we move away from the dangerous “all-in” mentality that plagues many retail investors. Instead, we embrace a modular approach to capital. By breaking down a portfolio into 25% increments—or “quarters”—investors can create a balanced ecosystem that thrives across different economic cycles. This exploration delves into the sophisticated math of money, where the sum of your parts defines your ultimate financial ceiling.
The Quadrant Strategy: Breaking Down the “Whole” Portfolio
To understand the weight of 1/4 + 1/4, one must first view their net worth as a unified 100%. In professional wealth management, the “Rule of Four” or the Quadrant Strategy is often used to ensure that no single market event can wipe out an individual’s holdings. When you combine two distinct 25% allocations, you are not just reaching 50%; you are creating a “core” or a “tilt” that dictates the trajectory of your growth.
The Psychology of 25% Increments
The human brain often struggles with complex percentages, but it intuitively understands quarters. This is why many of the world’s most successful investment models, such as the Harry Browne Permanent Portfolio, utilize 25% buckets. By allocating exactly one-quarter of your capital to four distinct asset classes, you remove the emotional burden of “timing the market.” When you add one quarter (for example, equities) to another quarter (such as real estate), you have effectively secured half of your wealth in growth-oriented assets. This structural simplicity prevents the “paralysis by analysis” that often stops new investors from taking action.
The Permanent Portfolio Model
One of the most famous applications of “1/4 + 1/4” is the Permanent Portfolio. This strategy suggests that a portfolio should be split into four equal parts: 25% Stocks, 25% Long-term Treasury Bonds, 25% Cash, and 25% Gold. In this context, asking “what is 1/4 + 1/4” takes on a specific meaning. If you add your 25% in stocks to your 25% in gold, you have a 50% hedge against both inflation and deflation. This mathematical balance ensures that while one quadrant may be underperforming, another is likely surging, keeping the total value stable.
Strategic Asset Allocation: Building the 50% Core
In personal finance, the “50% core” is the engine of your wealth. By combining two strategic 25% allocations, you create a foundation that can withstand market corrections. This is where the math of 1/4 + 1/4 becomes a tactical advantage. Most successful investors do not try to pick 100 different winning stocks; they pick two or four overarching themes and master the allocation between them.
Balancing Risk and Reward in Equal Quarters
Suppose an investor decides to allocate 1/4 of their income to a high-yield savings account or money market fund and another 1/4 to a diversified S&P 500 index fund. The sum—50%—represents a balanced “Barbell Strategy.” This approach provides the liquidity needed for emergencies (the first 1/4) while capturing the compounding power of the stock market (the second 1/4). The remaining 50% of their income might go toward living expenses and debt repayment. By focusing on these two 25% “wealth buckets,” the investor ensures that half of their gross income is working toward a future goal, regardless of short-term market noise.
The Math of Rebalancing
One of the most critical aspects of maintaining two 25% positions is the act of rebalancing. If your 1/4 allocation in Tech Stocks grows to become 40% of your portfolio, and your 1/4 in Bonds drops to 15%, your equation is no longer balanced. The savvy financier knows that the answer to “1/4 + 1/4” must always return to 1/2. This requires selling a portion of the winners (the overperforming 25%) and buying more of the laggards. This disciplined “sell high, buy low” behavior is mathematically enforced by the commitment to the 25% quadrant structure.
Beyond the Portfolio: Diversifying Income Streams
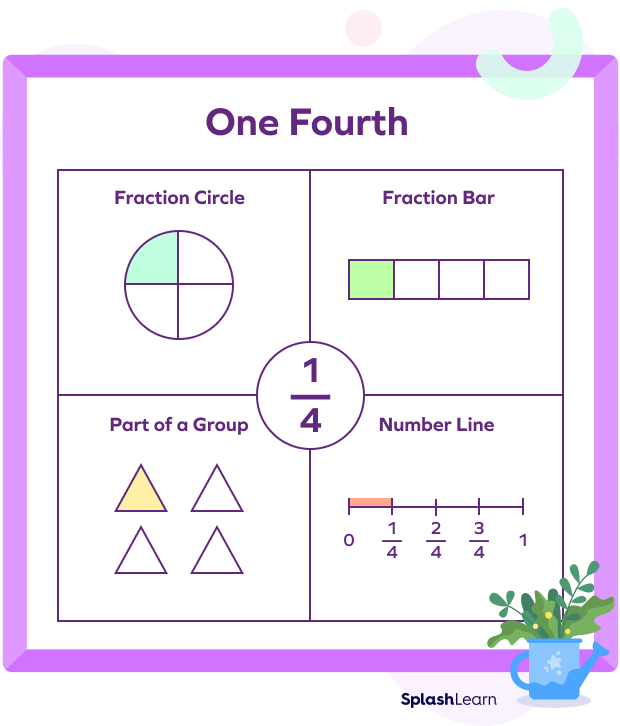
The concept of 1/4 + 1/4 extends beyond stocks and bonds; it applies directly to how we generate income in the modern economy. Relying on a single source of income—100% from a 9-to-5 job—is a high-risk strategy. In the context of “Money,” adding a second income stream that represents 25% of your total earnings can radically change your financial risk profile.
The Rule of Four in Passive Income
Financial independence is rarely achieved through a single salary. Instead, it is built by stacking “quarters.” Imagine a scenario where:
-
1/4 of income comes from a primary career.
-
1/4 of income comes from rental properties or REIT dividends.
-
1/4 of income comes from a side hustle or digital business.
-
1/4 of income comes from interest-bearing investments.
In this model, if the primary career (the first 1/4) is compromised due to layoffs or industry shifts, the individual still has 75% of their income intact. When you add the first 1/4 to the second 1/4, you have 50% “autonomous income”—money that is not tied to a single employer. This mathematical redundancy is the ultimate form of financial security.
Case Study: The 25% Side Hustle
Consider a professional earning $100,000 annually. If they build a side venture that generates $25,000 (1/4 of their base), they haven’t just increased their wealth; they have decreased their “dependency ratio.” By adding that second 1/4, they have reached a point where they could theoretically live on 50% of their total income while investing the other 50%. This “1/4 + 1/4” logic accelerates the timeline to retirement by years, if not decades, because it shifts the focus from “earning more” to “diversifying more.”
Fractional Investing and the Democratization of Wealth
Technological shifts in the financial sector have changed the literal meaning of 1/4. In the past, you needed enough capital to buy a whole share of a stock or a whole piece of real estate. Today, fractional investing allows us to answer the question “what is 1/4 + 1/4” at the micro-level.
Leveraging Micro-Investing Tools
Fractional shares allow an investor with only $100 to own a piece of high-priced assets like Amazon or Berkshire Hathaway. If you buy 1/4 of a share today and 1/4 of a share next month, you own 1/2 of a share. While this seems elementary, it represents the democratization of wealth. It allows for “Dollar Cost Averaging” (DCA) in precise increments. This ability to add small fractions together means that even those with limited disposable income can build a robust, diversified portfolio by consistently adding quarters together until they own significant “wholes.”
The Compound Effect of Small Additions
The true magic of 1/4 + 1/4 lies in compounding. In finance, we often discuss “basis points” and small percentage gains. Adding a 0.25% (1/4 of a percent) increase in your annual yield through better tax management, and another 0.25% through lower expense ratios, equals a 0.50% total gain. Over a 30-year investment horizon, that half-percent difference can result in hundreds of thousands of dollars in additional wealth. This is the “Money” niche’s version of the equation: small, fractional improvements added together result in massive terminal value.
Future-Proofing Through Mathematical Balance
As we look toward the future of global finance, the ability to think in fractions will become even more vital. With the rise of digital assets, tokenized real estate, and global equity markets, the “whole” is becoming less important than the “components.”
Rebalancing Strategies for Longevity
A portfolio that starts as 1/4 + 1/4 + 1/4 + 1/4 will naturally drift. The growth of the “Money” niche emphasizes that wealth is not a static number but a dynamic ratio. Professional investors use “Target Date” strategies or “Life Cycle” funds that automatically adjust these quarters. As an investor nears retirement, the 1/4 allocated to aggressive growth might be shifted into a 1/4 allocation for capital preservation. The equation remains the same, but the variables within the fractions change to match the individual’s risk tolerance.

The Conclusion of Cumulative Growth
In the final analysis, “what is 1/4 + 1/4” is a question about the philosophy of accumulation. It teaches us that wealth is built through the deliberate addition of parts. Whether it is adding 25% of your paycheck to a 401(k), diversifying 25% of your assets into a different currency, or spending 25% of your time developing a new skill, the cumulative effect is what creates financial resilience.
Wealth is rarely the result of a single 100% “win.” It is the result of adding 1/4 to 1/4, over and over again, until the sum of the parts is a fortress. By mastering the math of these fractions, you move from a participant in the economy to an architect of your own financial destiny. In the world of money, 1/2 is not just a fraction; it is the halfway point to total independence, built one quarter at a time.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.