
In the landscape of modern personal finance and real estate investing, the search for high-yield assets often leads investors toward volatile markets or complex commercial ventures. However, one of the most powerful financial tools for wealth generation is currently sitting—quite literally—in the backyards of millions of homeowners. The Accessory Dwelling Unit, or ADU, has emerged as a premier “Money” category asset, blending real estate investing, passive income generation, and strategic property valuation into a single, tangible project.
An ADU is a secondary housing unit on a single-family residential lot. While they are known by many names—granny flats, carriage houses, or backyard cottages—their financial identity is much more significant. For the savvy investor, an ADU represents a high-margin side hustle that leverages existing land to create a multi-generational wealth-building engine.
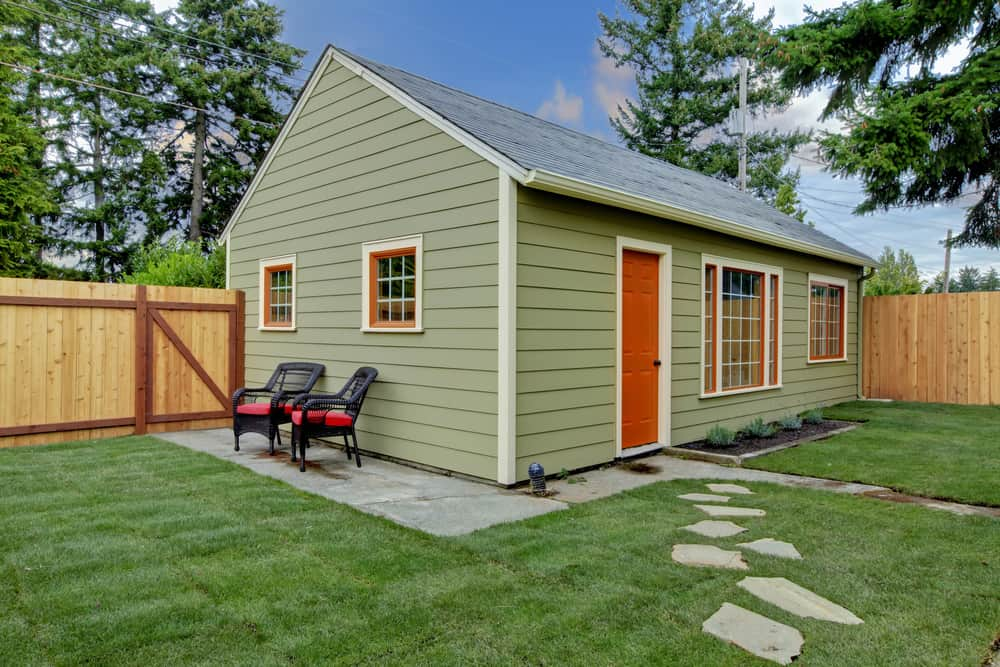
Understanding the ADU: An Asset-Class Deep Dive
Before diving into the spreadsheets, it is essential to define what constitutes an ADU from a business and financial perspective. An ADU is not merely a “renovation”; it is the creation of a new, income-producing asset. These units must be complete, independent living facilities with their own kitchen, bathroom, and sleeping area.
Types of ADUs and Their Investment Profiles
The financial entry point and eventual Return on Investment (ROI) vary significantly depending on the type of unit constructed:
-
Detached ADUs (DADUs): These are standalone structures separate from the primary residence. While they require the highest upfront capital investment (often ranging from $150,000 to $350,000), they typically command the highest rental premiums and offer the most significant boost to property appraisal values.
-
Attached ADUs: These share at least one wall with the primary home. They are often more cost-effective to build because they can leverage existing utility lines and structural components, leading to a faster “break-even” point for investors.
-
Junior ADUs (JADUs): These are smaller units (under 500 square feet) created within the walls of an existing residence, such as a converted bedroom or garage. For the budget-conscious investor, JADUs represent the most accessible entry into real estate investing, requiring minimal structural changes while still providing a distinct rental income stream.
The Regulatory Shift as a Market Opportunity
For decades, strict zoning laws limited the ability of homeowners to monetize their land. However, a massive shift in legislative policy—particularly in high-demand markets like California, Oregon, and Washington—has unlocked the “Money” potential of residential lots. By streamlining the permitting process and eliminating “owner-occupancy” requirements, local governments have essentially handed homeowners a license to operate a small-scale development firm from their primary residence.
The Financial Engine: ROI and Property Valuation
When evaluating an ADU through the lens of personal finance, one must look beyond the monthly rent check. The true power of an ADU lies in its dual-purpose financial impact: immediate cash flow and long-term equity growth.
Calculating the Value Add
In real estate appraisal, an ADU is often valued using a combination of the “Cost Approach” and the “Income Approach.” In hot markets, the addition of an ADU can increase a property’s total market value by 20% to 35%. For a property worth $800,000, adding an ADU that costs $200,000 might result in a new total valuation of $1,100,000. This immediate equity gain of $100,000 represents a massive return on capital that far outpaces traditional savings or stock market indexes in the short term.
Cash-on-Cash Return Analysis
For the income-focused investor, the cash-on-cash return is the primary metric of success. If an investor spends $200,000 to build an ADU and earns $2,500 per month in rent ($30,000 annually), the gross yield is 15%. Even after accounting for property taxes, insurance, and maintenance, the net yield often settles between 8% and 11%. Compared to the 4% “safe withdrawal rate” of a traditional retirement portfolio, an ADU functions as a high-performance dividend-paying asset.
Highest and Best Use (HBU)
In financial terms, adding an ADU is often the “Highest and Best Use” of residential land. By increasing the density of the lot without the cost of purchasing new land, the investor effectively lowers their average cost per square foot for the entire property. This is a fundamental principle of business finance: maximizing the productivity of an underutilized asset.
The Income Stream: Leveraging ADUs for Passive Cash Flow
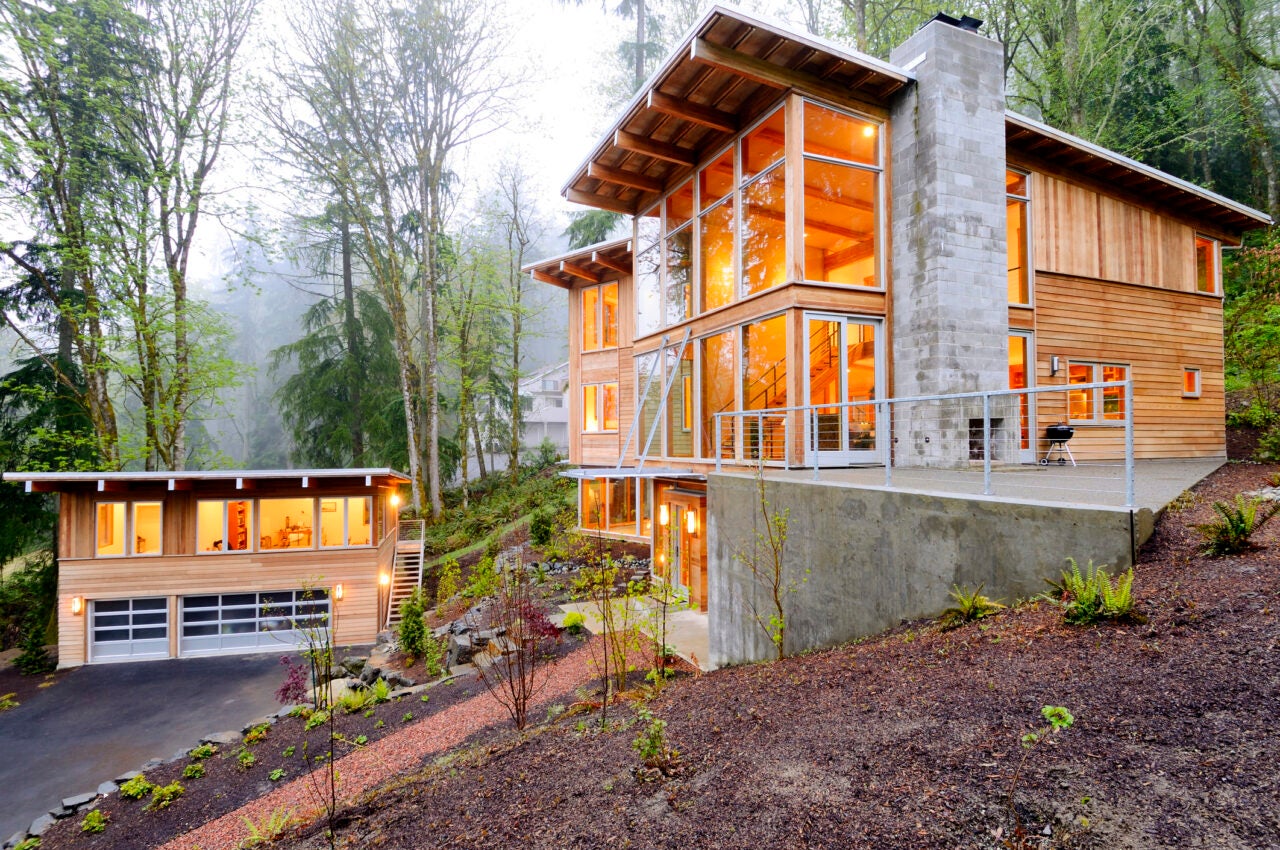
The most compelling “Money” aspect of an ADU is its versatility as a side hustle. It provides a platform for various income-generating strategies that can be tailored to the investor’s risk tolerance and time commitment.
Long-Term Residential Leasing
The “set it and forget it” model of ADU investing involves long-term leases (12 months or more). This provides a stable, predictable monthly income that can be used to offset mortgage payments, fund retirement accounts, or reinvest in other assets. In many urban centers, the rent from an ADU can cover 50% to 75% of the primary home’s mortgage, effectively allowing the owner to live for a fraction of the market rate—a strategy known in the finance community as “house hacking.”
The Short-Term Rental Premium
In jurisdictions where it is legally permitted, converting an ADU into a short-term rental (STR) via platforms like Airbnb or VRBO can double or triple the monthly revenue compared to long-term leasing. While this requires more active management and results in higher operational costs, the net profit can be substantial. For an investor located near a major university, hospital, or tourist hub, an ADU can generate $4,000 to $6,000 per month, transforming a backyard structure into a significant small business.
Portfolio Diversification
From a wealth management perspective, the income from an ADU serves as a hedge against market volatility. While stock prices may fluctuate, the demand for housing in metropolitan areas remains consistently high. An ADU provides a “hard asset” that produces “soft income,” diversifying an investor’s portfolio away from purely paper-based assets like 401(k)s and IRAs.
Financing Your ADU: Strategic Funding for the Modern Investor
One of the biggest hurdles to ADU ownership is the upfront cost. However, the modern financial landscape offers several sophisticated tools for funding construction without depleting personal savings.
Home Equity Lines of Credit (HELOCs)
For many homeowners, the most efficient way to fund an ADU is by tapping into the existing equity of their primary home. A HELOC allows the investor to borrow against their home’s value at relatively low interest rates. Because the ADU itself will increase the home’s value, this is a form of “good debt” where the borrowed capital is used to create an asset that generates more income than the cost of the interest.
Construction Loans and Renovation Mortgages
Specialized financial products, such as the FHA 203(k) or the Fannie Mae Homestyle Renovation loan, allow buyers to wrap the cost of ADU construction into their primary mortgage. This is a powerful tool for new investors, as it allows them to acquire a property and fund the income-producing ADU simultaneously with a single, long-term, low-interest loan.
Ground-Lease and Revenue-Share Models
A new frontier in ADU finance involves “ADU-as-a-Service” companies. These firms will fund, build, and manage an ADU on your property in exchange for a share of the rental revenue for a set period. While this reduces the investor’s total profit, it eliminates the capital risk and operational burden, making it an attractive option for those who prioritize time over maximum yield.
Tax Implications and Long-Term Wealth Building
To maximize the “Money” potential of an ADU, one must navigate the tax landscape with precision. Like any professional real estate investment, ADUs offer significant tax advantages that can shield income and accelerate wealth accumulation.
Depreciation and Expense Deductions
The IRS allows ADU owners to depreciate the cost of the structure over 27.5 years. This non-cash expense can be used to offset the rental income received, often resulting in a “tax-free” or “tax-deferred” cash flow. Furthermore, a portion of the property’s overall utility bills, landscaping costs, and maintenance can be deducted as business expenses, reducing the investor’s overall taxable income.
The 1031 Exchange Strategy
For the long-term wealth builder, an ADU-equipped property is a prime candidate for a 1031 Exchange. This section of the tax code allows investors to sell a property and reinvest the proceeds into a “like-kind” asset while deferring all capital gains taxes. Because an ADU significantly increases the sale price of a home, the “gain” realized can be rolled into a larger multi-family complex or a commercial property, allowing the investor to scale their portfolio exponentially.
Estate Planning and Multi-Generational Wealth
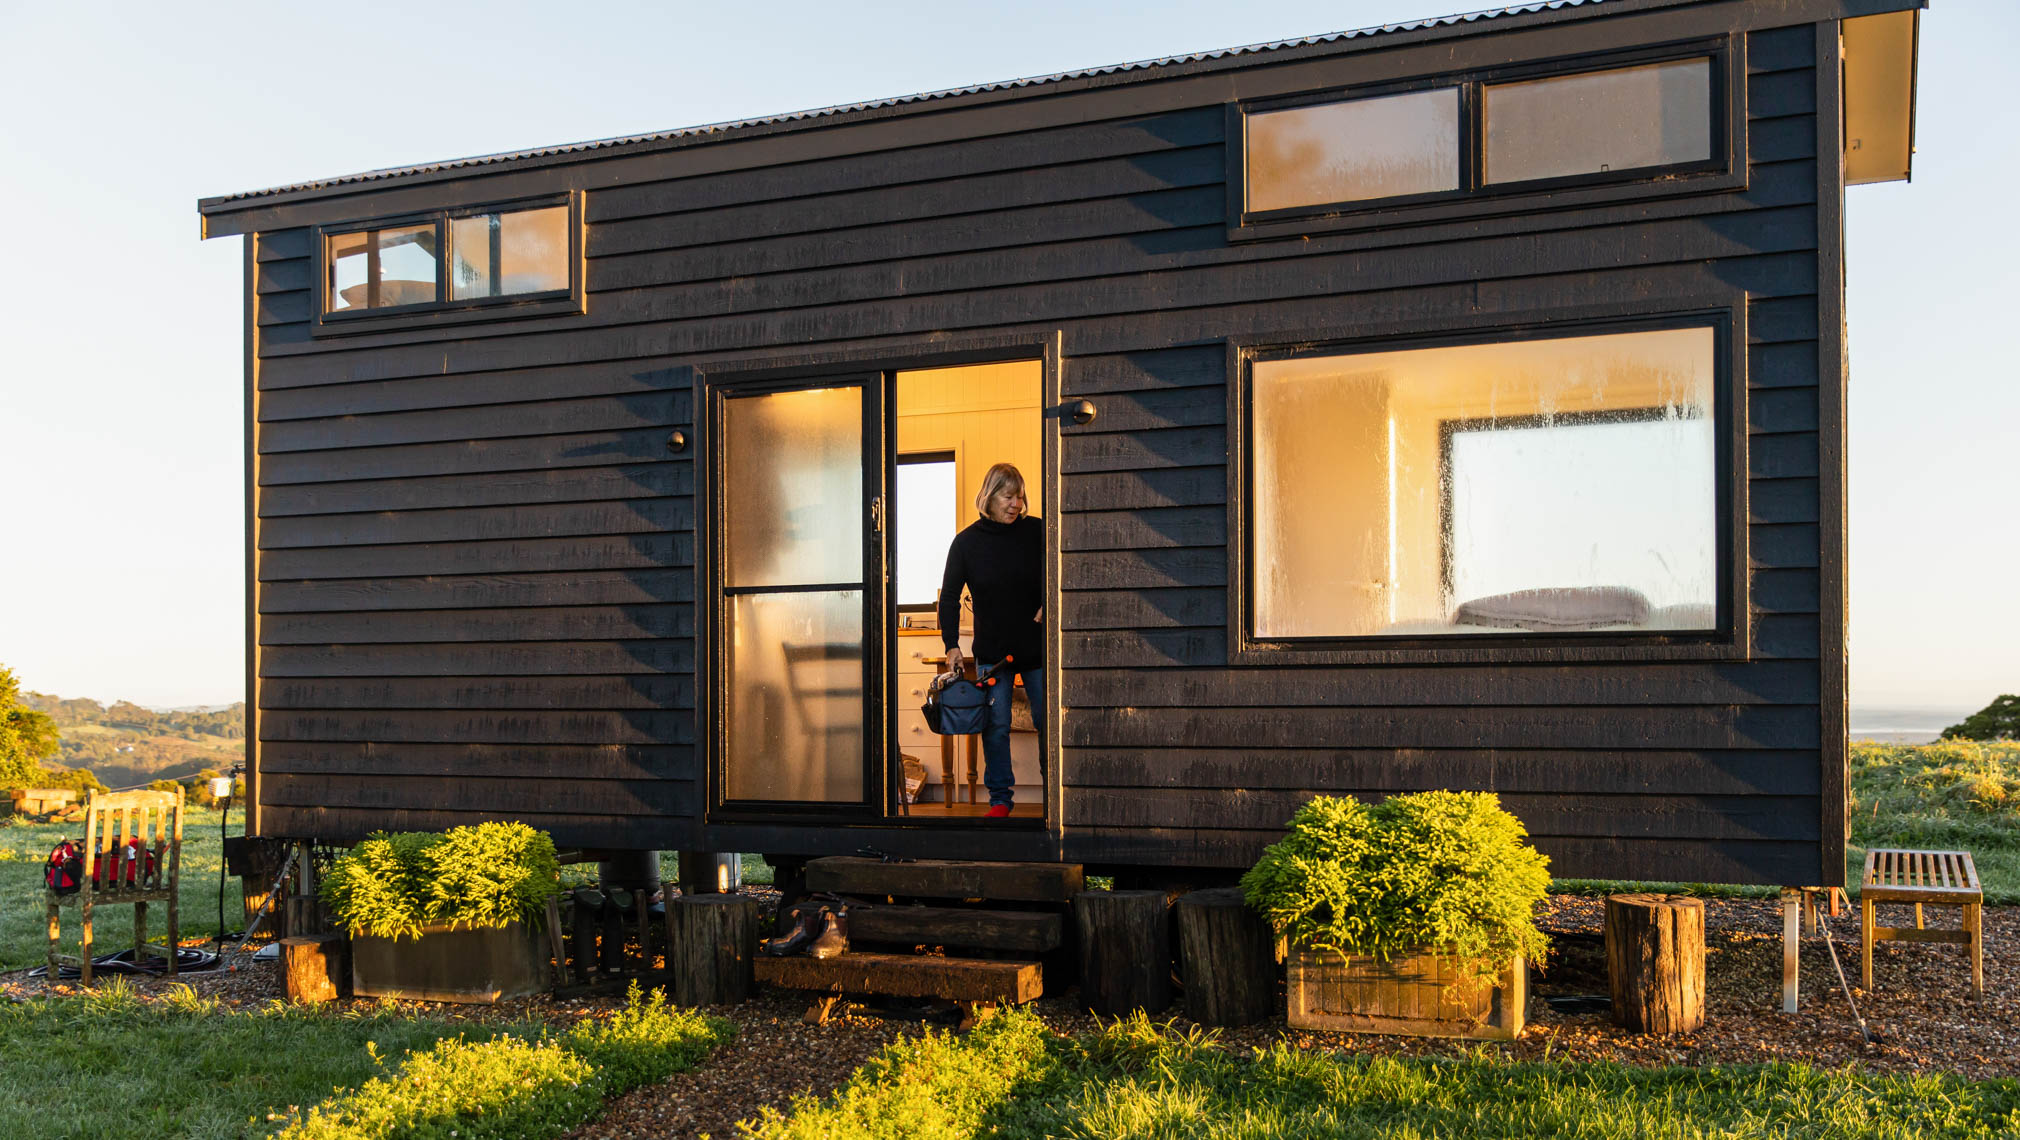
Beyond immediate income, an ADU serves as a cornerstone of estate planning. It provides a flexible housing solution for aging parents (saving on assisted living costs) or adult children (helping them save for their own homes). In financial terms, this “cost avoidance” is just as valuable as “income generation,” keeping more wealth within the family unit over decades.
In conclusion, an ADU is far more than an extra room; it is a sophisticated financial instrument. By converting underutilized land into a high-demand rental asset, homeowners can effectively launch a high-margin business from their own property. Whether the goal is to achieve early retirement, hedge against inflation, or build a legacy for the next generation, the ADU stands as one of the most accessible and effective wealth-building tools in the modern financial toolkit.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.