
The daily movements of mortgage rates are far more than just numbers on a screen; they are a critical barometer for the housing market, a key driver of household financial decisions, and a reflection of broader economic health. For prospective homebuyers, homeowners considering refinancing, and even investors, understanding these daily shifts is paramount. Today, like every other day, the mortgage market presented a dynamic picture, influenced by a confluence of economic indicators and market sentiment. While the headline figures often capture the immediate attention, the real insight lies in understanding the underlying forces at play and what these movements ultimately mean for your wallet.
A Snapshot of Today’s Mortgage Market
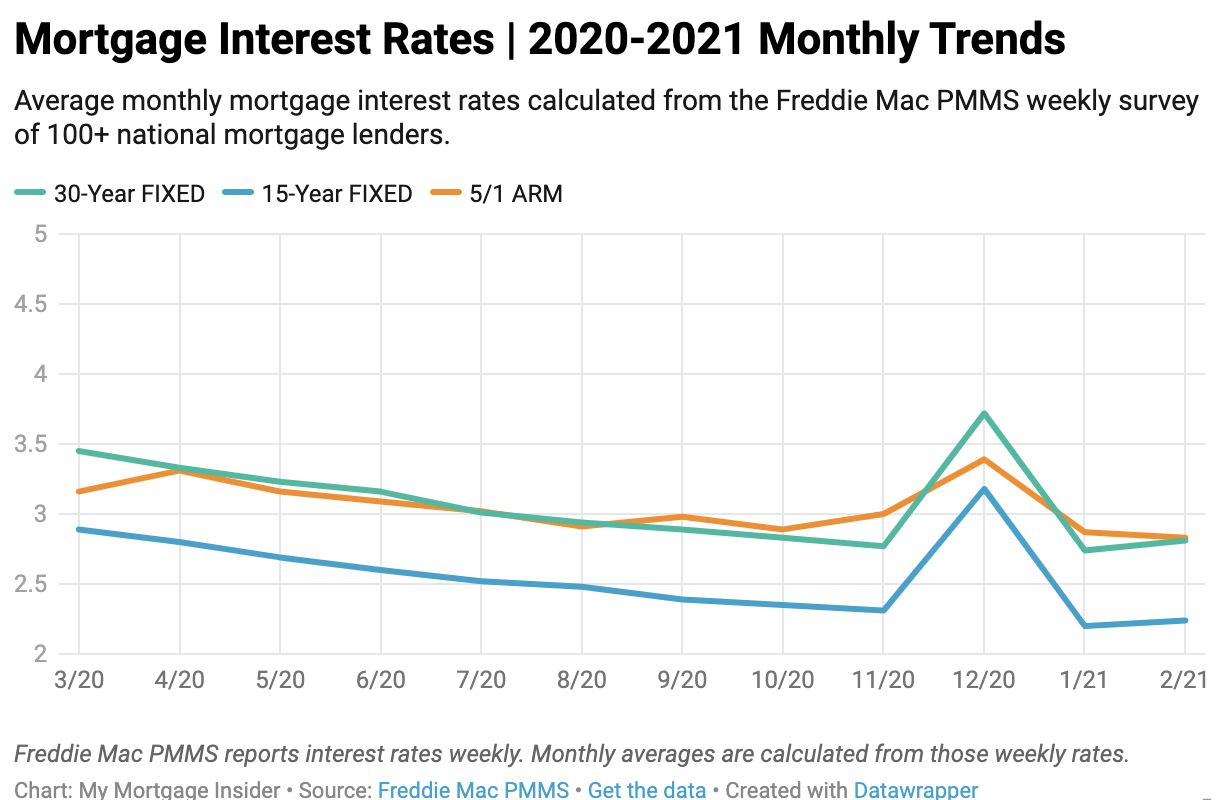
Today’s mortgage market saw a nuanced set of movements, with rates for various loan types experiencing slight adjustments rather than dramatic shifts. The overall sentiment remains one of cautious observation, as lenders and borrowers alike gauge the economy’s direction.
The Bellwether: 30-Year Fixed Rates
The 30-year fixed-rate mortgage, the most popular choice for homebuyers, remained relatively stable today, exhibiting minor fluctuations within a tight range. This stability suggests that while there are underlying pressures, the market isn’t reacting to any immediate, significant news that would prompt a sharp upward or downward trend. Lenders adjusted their offerings slightly based on their individual cost of capital and competitive positioning, but the broad average hovered consistently. This relative calm provides a moment of reprieve for those who have been observing the market for weeks, allowing for more deliberate decision-making without the intense pressure of rapidly escalating or falling rates. It hints at a market that has largely priced in current expectations for inflation and monetary policy, awaiting the next significant data release to dictate a new trajectory.
Shorter Terms and Adjustable Rates
For shorter-term fixed-rate mortgages, such as the 15-year fixed, movements largely mirrored those of their 30-year counterpart but often with a slightly greater sensitivity to bond market shifts. These rates also saw minor adjustments, maintaining their position as a more affordable option for borrowers capable of higher monthly payments. Adjustable-rate mortgages (ARMs), particularly the popular 5/1 and 7/1 ARMs, followed a similar pattern. Their initial fixed rates tend to be lower than comparable fixed-rate products, making them attractive to specific borrower profiles. Today’s stability in ARMs indicates that short-term market expectations, which heavily influence these products, remained consistent. For borrowers considering ARMs, today’s rates offered a continuation of recent trends, maintaining their relative attractiveness compared to longer-term fixed options, especially for those who anticipate selling or refinancing before the adjustment period kicks in.
The Nuance of Daily Fluctuations
It’s crucial to understand that “what did mortgage rates do today” isn’t a single, uniform answer. Rates vary significantly from lender to lender based on their overheads, risk assessment, and profit margins. Furthermore, individual borrower profiles—credit score, debt-to-income ratio, loan-to-value ratio, and even the property type and location—play a substantial role in the actual rate offered. Today’s reported average movements reflect a broad market trend, but the precise rate you qualify for could be different. This nuance underscores the importance of obtaining personalized quotes rather than relying solely on generalized daily averages. The small shifts observed today, while seemingly minor, can aggregate over time or indicate the beginning of a larger trend, making diligent monitoring essential for savvy financial planning.
Unpacking the Economic Catalysts Behind Rate Movements
Mortgage rates do not move in a vacuum. They are intricately linked to a complex web of economic indicators, central bank policies, and global financial market dynamics. Understanding these underlying drivers provides invaluable context to daily rate changes.
Inflationary Pressures and the Federal Reserve’s Stance
One of the most significant forces influencing mortgage rates is inflation. When inflation rises, the purchasing power of money erodes, prompting investors to demand higher returns on their investments, including mortgage-backed securities (MBS). Mortgage rates typically track these MBS yields. The Federal Reserve, tasked with maintaining price stability, uses its monetary policy tools, primarily the federal funds rate, to combat inflation. While the federal funds rate doesn’t directly dictate mortgage rates, its influence is profound. Today’s mortgage rate movements largely reflect the market’s ongoing assessment of the Fed’s future actions regarding interest rate hikes or cuts, and its overall strategy to tame inflation. Any statement from a Fed official or new data point suggesting a change in their inflation outlook can immediately ripple through the mortgage market.
The Role of the Bond Market: A Proxy for Mortgages
Mortgage rates are closely tied to the yields on U.S. Treasury bonds, particularly the 10-year Treasury note. This is because mortgage-backed securities (MBS) compete with Treasuries for investor attention. When Treasury yields rise, MBS must offer higher yields to remain competitive, which translates to higher mortgage rates. Conversely, falling Treasury yields can lead to lower mortgage rates. Today’s mortgage rate behavior was significantly influenced by the movements in the 10-year Treasury yield, which itself responds to a multitude of factors including economic growth prospects, geopolitical events, and investor demand for safe-haven assets. A slight uptick or downturn in Treasury yields today likely played a direct role in the marginal shifts observed in mortgage rates, illustrating the bond market’s function as a real-time barometer.
Broader Economic Indicators: Jobs, GDP, and Consumer Confidence
Beyond inflation and central bank actions, the broader health of the economy—as measured by indicators like employment figures, Gross Domestic Product (GDP) growth, and consumer confidence—also impacts mortgage rates. A strong economy, characterized by robust job growth and increasing GDP, generally signals higher inflation potential and a greater likelihood of the Fed tightening monetary policy, which can push rates up. Conversely, signs of economic weakness can lead to lower rates as investors seek safe havens and the Fed adopts a more accommodative stance. Today’s rate movements implicitly factored in the latest economic data releases, such as unemployment claims or manufacturing indices. A surprisingly strong jobs report or a dip in consumer sentiment, for instance, could have contributed to the market’s overall direction, underscoring how intricately tied the housing finance market is to the macroeconomic landscape.
What Today’s Movements Mean for Borrowers
Understanding the daily ebb and flow of mortgage rates is not merely an academic exercise; it has tangible implications for anyone looking to enter the housing market or optimize their existing mortgage.

Implications for Prospective Homebuyers
For prospective homebuyers, today’s relatively stable mortgage rates offered a window of opportunity without the urgency of rapidly rising costs or the temptation of plummeting rates. Stability allows for more deliberate research, comparison shopping among lenders, and careful budget planning. While rates didn’t drop significantly to create a “buyer’s market” solely based on affordability, they also didn’t surge, preventing further erosion of purchasing power. This environment encourages buyers to focus on other market dynamics, such as inventory levels and home prices, rather than being solely preoccupied with day-to-day rate changes. It underscores the importance of getting pre-approved to lock in a rate for a period, safeguarding against potential future increases while you house hunt.
Refinancing Opportunities (or Missed Opportunities)
Homeowners contemplating a refinance found today’s rates presenting a continuation of the existing landscape. For those whose current mortgage rate is significantly higher than today’s offerings, a refinance could still yield substantial long-term savings, even with only minor daily changes. However, for those already at historically low rates, today’s movements likely didn’t open up new, compelling opportunities. The decision to refinance involves a careful calculation of closing costs against potential savings over the life of the loan. Today’s stability means that the calculus from yesterday likely remains valid, providing time for a thorough cost-benefit analysis without the pressure of a rapidly closing window. Homeowners should consult with a financial advisor to determine if today’s rates align with their financial goals and break-even point.
The Psychology of Rate Shopping
The daily fluctuations in mortgage rates can create a “fear of missing out” (FOMO) or a “waiting for the bottom” mentality. Today’s marginal movements, however, remind borrowers that timing the market perfectly is often impossible and potentially counterproductive. Instead of chasing the absolute lowest point, a more pragmatic approach involves locking in a rate when it aligns with your budget and financial comfort zone. Obsessing over a few basis points gained or lost can lead to paralysis by analysis. Today’s market reinforces the wisdom of locking when you’re ready and when the rate is favorable for your specific situation, rather than endlessly waiting for a hypothetical optimal moment that may never materialize or could be fleeting.
Navigating the Mortgage Landscape: Strategies for Tomorrow
Armed with an understanding of today’s mortgage market, borrowers can adopt proactive strategies to make informed decisions for the future.
Understanding Your Personal Financial Position
Before engaging with any lender or making a decision based on daily rate movements, a thorough assessment of your personal financial health is crucial. This includes evaluating your credit score, debt-to-income ratio, cash reserves for down payments and closing costs, and long-term financial goals. Lenders will base your offered rate heavily on these factors, often more so than the small daily shifts in the broader market. Today’s stable rates provide an excellent opportunity to get your financial house in order, knowing that immediate market volatility isn’t pressuring you into hasty decisions. A strong financial profile can often secure a better rate even if the overall market is trending slightly higher.
Working with Lenders and Rate Locks
Engaging with multiple lenders to obtain personalized quotes is a fundamental strategy that becomes even more important in a market with daily fluctuations. Today’s rates, though broadly stable, can still vary significantly between institutions. Once you identify a favorable rate, consider a rate lock. A rate lock agreement guarantees a specific interest rate for a defined period (e.g., 30, 45, or 60 days) while your loan application is processed. This protects you from potential rate increases between the time of application and closing, offering peace of mind. Understand the terms of the rate lock, including any associated fees and the window during which it’s valid.
Long-Term Outlook and Expert Perspectives
While “what did mortgage rates do today” provides an immediate snapshot, making long-term financial decisions requires considering the broader outlook. Experts generally anticipate that mortgage rates will remain sensitive to inflation data, the Federal Reserve’s monetary policy, and global economic stability. Today’s stability shouldn’t be mistaken for a permanent plateau. Economic forecasts are continuously updated, and staying informed about these broader trends—rather than reacting to every micro-movement—is key. Subscribing to financial news, following reputable economists, and consulting with financial advisors can help you contextualize daily changes within a larger, more impactful narrative.
Beyond Today: The Persistent Influence of Mortgage Rates
The daily reading of mortgage rates, while immediate, also contributes to a larger, more enduring impact on the economy and individual wealth.
The Broader Housing Market Impact
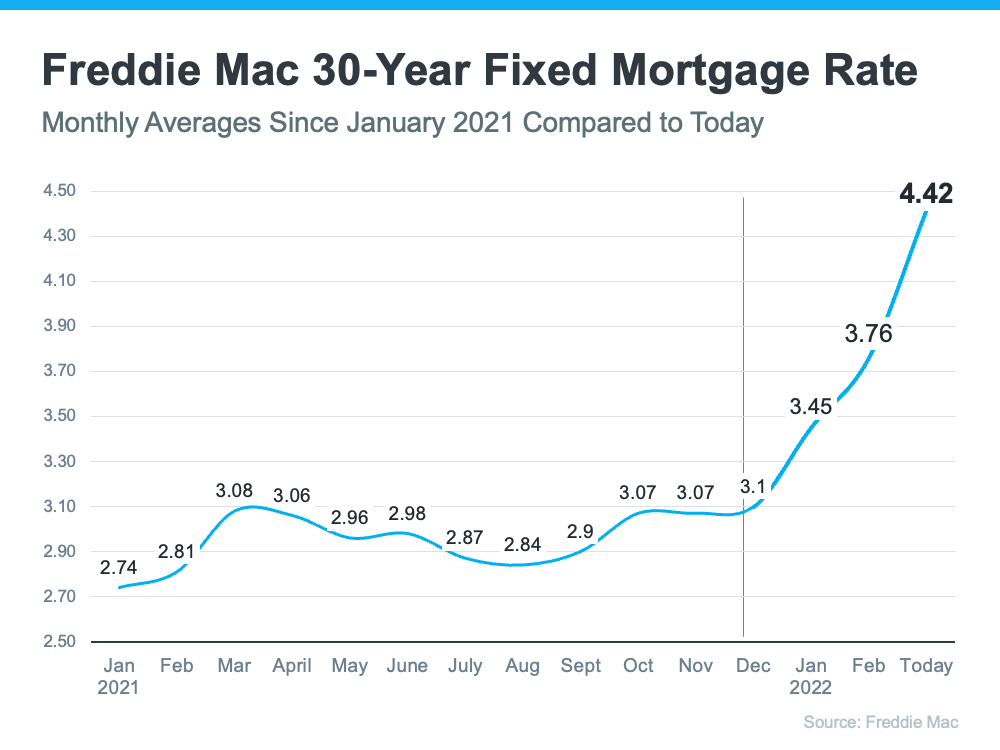
Mortgage rates are a primary determinant of housing affordability. When rates are high, the cost of borrowing increases, making homeownership less accessible for many and often cooling demand. Conversely, lower rates stimulate demand and can fuel home price appreciation. Today’s moderate movements indicate a market that isn’t experiencing extreme pressure on either front. This allows for a more gradual evolution of home prices and inventory, contrasting with periods of rapid market shifts driven by dramatic rate changes. The stability seen today, if it persists, can contribute to a more balanced, albeit still challenging, housing market, providing a clearer path for both buyers and sellers to plan.
Economic Ripple Effects
Beyond housing, mortgage rate movements have ripple effects throughout the broader economy. Changes in mortgage rates affect consumer spending power; lower rates can free up disposable income for other goods and services, while higher rates can tighten household budgets. They also influence investor sentiment in real estate and related industries. A stable rate environment, as observed today, tends to foster a sense of predictability, which can support economic planning and investment decisions across various sectors. The cumulative impact of daily, sometimes minor, rate adjustments can significantly shape economic trajectories over months and years, making their observation a critical part of financial literacy.
In conclusion, “what did mortgage rates do today” reveals a market characterized by relative stability and nuanced movements rather than dramatic shifts. While the immediate implications for individual borrowers depend heavily on their unique financial situation and goals, the underlying economic forces—inflation, Federal Reserve policy, and the bond market—continue to exert their influence. For anyone navigating the complexities of homeownership or investment, a proactive approach that blends daily awareness with a broader understanding of economic trends remains the most insightful and effective strategy.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.