
Understanding the Financial Implications of Cancellation
Canceling a credit card, even one from a reputable issuer like Chase, is a significant financial decision that extends beyond simply cutting up the plastic. It impacts your credit score, future borrowing capacity, and overall financial health. Before initiating the process, a thorough understanding of these implications is crucial to avoid unintended negative consequences.
Assessing Your Reasons for Closing the Account
Various financial motivations drive individuals to consider canceling a credit card. A common reason is minimizing annual fees. If a card’s benefits (rewards, travel perks, insurance) no longer outweigh its yearly cost, particularly for a card you rarely use, cancellation can be a wise financial move. Another compelling reason is debt management. For some, reducing the number of open credit lines simplifies financial oversight and reduces the temptation to incur more debt. An underutilized card might also be a candidate for cancellation; while an idle card doesn’t directly harm your credit, it ties up a portion of your available credit, which could be better managed elsewhere, or it might pose a security risk if not monitored. Finally, shifting financial priorities, such as consolidating rewards programs with another issuer or simplifying your banking relationships, often prompts card cancellations. Each reason should be weighed against the potential impact on your credit profile.
The Impact on Your Credit Score
The decision to close a credit card can have both immediate and long-term effects on your credit score, primarily by influencing key factors:
-
Credit Utilization Ratio: This ratio measures the amount of credit you’re using compared to your total available credit. Closing a card reduces your total available credit. If you carry balances on other cards, closing a card with a high credit limit can drastically increase your utilization ratio, which is a major negative factor for your score. It’s highly advisable to pay down other credit card balances before closing an account to mitigate this impact.
-
Average Age of Accounts: Credit scoring models favor a longer credit history. Closing an old account, particularly your oldest, can reduce your average age of accounts, potentially causing a dip in your score. Newer accounts have less impact if closed, but an established, long-standing account with a positive payment history is a valuable asset to your credit profile.
-
Number of Open Accounts: While less impactful than utilization or age, having too many open credit lines can sometimes be seen as a higher risk. However, closing an account indiscriminately can also be detrimental.
-
Short-term vs. Long-term Effects: Any initial dip in your credit score due to an increased utilization ratio or reduced average account age is often temporary, especially if you continue to manage your remaining credit responsibly. However, the long-term benefit of a higher average account age from an old, open card is lost permanently upon cancellation.
Your Pre-Cancellation Financial Checklist
Before you contact Chase to close your credit card account, several essential financial steps must be completed to prevent complications, safeguard your rewards, and ensure a smooth transition. Overlooking these details can lead to financial losses, service interruptions, or unexpected charges.
Settling All Outstanding Balances
This is the most critical step. Full payment is crucial for a successful cancellation. Chase will generally not close an account with a remaining balance, and even if they agree to, interest will continue to accrue until it’s paid off, potentially leading to collection efforts. Ensure all recent transactions have posted to your account, and then pay the entire outstanding balance to zero. Double-check for any pending charges that might appear after your payment. Additionally, review any autopay arrangements you may have set up directly with Chase or through third-party billers using this card to prevent future unexpected charges.
Redeeming or Transferring Rewards
If your Chase credit card accumulates rewards points, such as Chase Ultimate Rewards, it’s imperative to redeem or transfer them before closing the account. Points are typically forfeited upon cancellation. Explore all redemption options available through your Chase online portal: cash back, travel bookings through the Chase portal, gift cards, or transferring points to Chase’s loyalty program partners (e.g., airlines, hotels). If you have other Chase cards that earn Ultimate Rewards, you might be able to transfer your points to one of those accounts to preserve their value, provided the receiving card allows point pooling. This can be a valuable strategy to maintain the flexibility and high redemption value of Ultimate Rewards.
Notifying Recurring Billers and Subscriptions
Credit cards are often linked to various recurring payments, from essential utilities to streaming services. Before canceling, make a comprehensive list of all services, subscriptions, and memberships that charge this particular Chase card. This includes services like Netflix, Spotify, gym memberships, mobile phone bills, internet providers, insurance premiums, and even ride-sharing apps. Proactively update payment information with a new credit or debit card for all these billers to avoid any service interruptions or late payment fees. Failing to do so can result in suspended services or missed payments, which can also affect your credit history for non-credit accounts.
Exploring Alternatives to Full Cancellation
Full cancellation isn’t always the best financial move. Chase, like many major issuers, offers alternatives that can mitigate the negative impact on your credit score while still addressing your concerns:
-
Product Change (Downgrade): You may be able to switch your current Chase card to a different card within their portfolio, often to a version with no annual fee. This is known as a product change. The primary benefit is that your account number and credit history with Chase remain intact, preserving the average age of that account and avoiding a hard inquiry. It’s an excellent option if you want to avoid annual fees but still maintain a long-standing credit relationship.
-
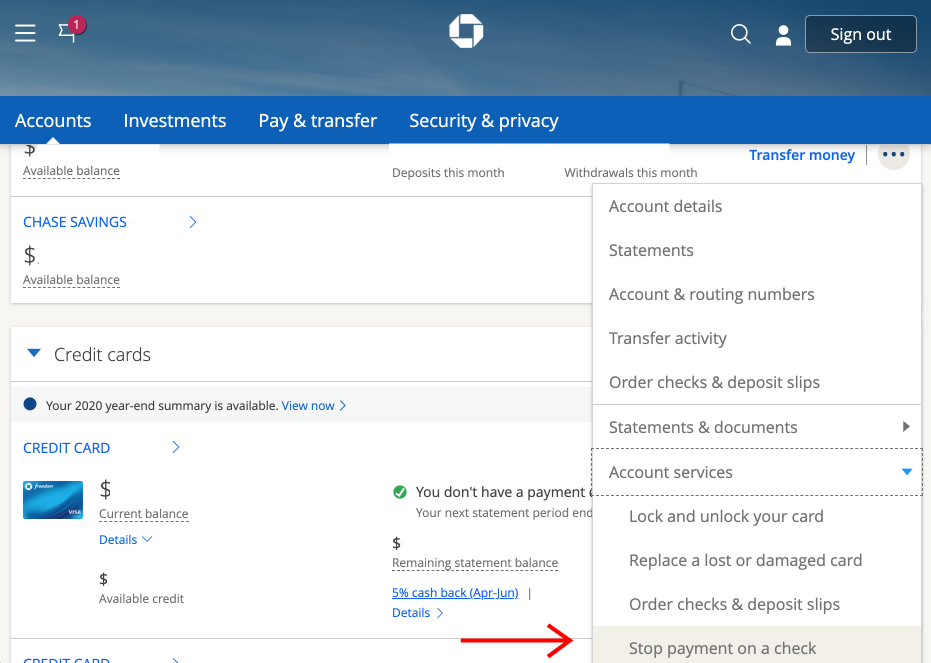
Temporary Freeze/Lock: If your concern is simply overspending or security, Chase allows you to temporarily freeze or lock your card through their mobile app or online banking. This prevents new purchases while keeping the account open and active, thus having no impact on your credit score.
-
Negotiating Annual Fees: If your primary concern is an annual fee, call Chase’s customer service and inquire about retention offers. For valuable customers, Chase sometimes offers statement credits, bonus points, or other incentives to encourage you to keep the card open for another year. This can be a win-win, allowing you to retain the card’s benefits and credit history while offsetting the fee.
The Step-by-Step Cancellation Process with Chase
Once you’ve completed your pre-cancellation checklist and are firm in your decision, you’re ready to contact Chase. The process is straightforward, but knowing what to expect and how to communicate effectively can make it smoother.
Gathering Necessary Information
Before you dial, have your Chase credit card account number readily available. You’ll also need to be prepared to answer security questions to verify your identity, which might include your date of birth, the last four digits of your Social Security Number, or details about recent transactions. Ensuring you have this information at hand will speed up the verification process.
Choosing Your Contact Method
For credit card cancellations, a phone call is highly recommended due to its directness and the ability to immediately address any questions or issues.
-
Phone Call (Recommended):
-
Chase Customer Service Number: Locate the customer service number on the back of your card or via Chase’s official website. For general credit card inquiries, a common number is 1-800-432-3117.
-
What to Expect: Be prepared for potential waiting times. When you connect, you’ll likely speak with a customer service representative initially. Clearly state your intention to cancel your credit card. Often, they will transfer you to a “retention specialist” whose role is to understand your reasons and attempt to keep you as a customer.
-
Key Talking Points: Clearly and politely state that you wish to close your credit card account. You don’t need to provide extensive detail about your reasons if you don’t want to, but a brief explanation (e.g., “I’m consolidating my cards,” or “I no longer need this card due to the annual fee”) can be helpful. Reiterate that your balance is zero and that all rewards have been redeemed.
-
Request Confirmation: Before ending the call, explicitly ask for a confirmation number for the cancellation. Additionally, request that a written confirmation of the account closure be sent to you via email or postal mail. This document is your proof of cancellation and will confirm that the account is being reported as “closed by customer” to credit bureaus.
-
-
Secure Message (Online Banking): While Chase offers a secure messaging system through its online banking portal, it’s generally less efficient for cancellations. It can take longer to receive a response, and you won’t have the immediate back-and-forth for negotiation or direct confirmation. However, it does provide a written record of your request.
-
In-Branch Visit (Less Common for Cancellation): While you can visit a Chase branch for various banking needs, branch staff often have limited authority to directly close credit card accounts. They may be able to assist with general inquiries or payments but will typically direct you to call the customer service line for actual cancellation.
Handling Retention Offers
During your phone call, especially if transferred to a retention specialist, Chase may present you with retention offers. These are incentives designed to encourage you to keep your account open. Offers can include:
-
A waiver or reduction of your annual fee for the next year.
-
Bonus Ultimate Rewards points after meeting a certain spending threshold.
-
A statement credit.
-
A temporary reduction in your interest rate (if you carry a balance, which you shouldn’t be).
Evaluate the offer carefully. Does it genuinely meet your financial goals? Is the value of the offer enough to justify keeping the card and its potential impact on your credit score? If the offer doesn’t align with your objectives, politely decline and reaffirm your decision to cancel the card.
Final Confirmation
After the call, monitor your email and postal mail for the written confirmation from Chase. This document should clearly state that your account has been closed at your request and that the balance was zero. It serves as vital proof if any discrepancies arise later. Within one to two billing cycles, check your credit report (from a major bureau like Experian, Equifax, or Transunion) to ensure the Chase account is accurately reported as “closed by consumer” with a zero balance. This verification is crucial for maintaining the integrity of your credit history.
Post-Cancellation Financial Management
Canceling a credit card is a point in time, but its financial implications can extend well into the future. Proper management of your finances after cancellation is essential to ensure your credit health remains robust and to integrate this change into your broader financial strategy.
Managing Your Credit Report
After receiving confirmation from Chase, the next critical step is to monitor your credit report. Verify the account status with all three major credit bureaus (Experian, Equifax, TransUnion) within a few weeks to a month. The report should accurately reflect the account as “closed by consumer” with a zero balance. If it shows “closed by issuer” or indicates an outstanding balance, immediately contact Chase to rectify the error, as this could negatively impact your credit score. While there might be a temporary impact on your credit score due to changes in utilization or average age of accounts, understanding these factors helps you interpret any fluctuations. Remember that a closed account with a positive payment history can remain on your credit report for up to 10 years, continuing to contribute to your credit age positively during that period.
Safely Disposing of the Physical Card
Once the account is officially closed and you’ve verified its status, it’s time to physically dispose of the card securely. Simply cutting the card in half is often insufficient. Ensure you shred or cut through the magnetic stripe and the EMV chip multiple times. This prevents unauthorized access to your account details, even though the card is inactive. Distributing the pieces into different trash bins can add an extra layer of security. Even a canceled card can contain sensitive information if not properly destroyed.
Reassessing Your Financial Strategy
The act of canceling a credit card provides an opportune moment to reassess your overall financial strategy. If the card was frequently used, adjust your budgeting to reflect its absence. Consider how this change impacts your monthly cash flow and spending habits. Use this as an opportunity to review your remaining credit accounts, ensuring they align with your financial goals and that you’re maximizing their benefits while minimizing fees. It’s a chance to build a stronger financial foundation by consciously managing your credit and debt.
The Possibility of Reopening or Reapplying
Generally, once a Chase credit card account is fully closed at your request, it’s not possible to simply reopen it. You would need to apply for a new card. If you decide to reapply for a similar Chase card in the future, it will be treated as a new application, requiring a new credit check (hard inquiry), and you’ll be subject to current terms and conditions. It’s often advisable to wait at least six months to a year after closing an account before applying for new credit to allow your credit score to stabilize and prevent multiple hard inquiries in a short period, which can negatively impact your score.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.