
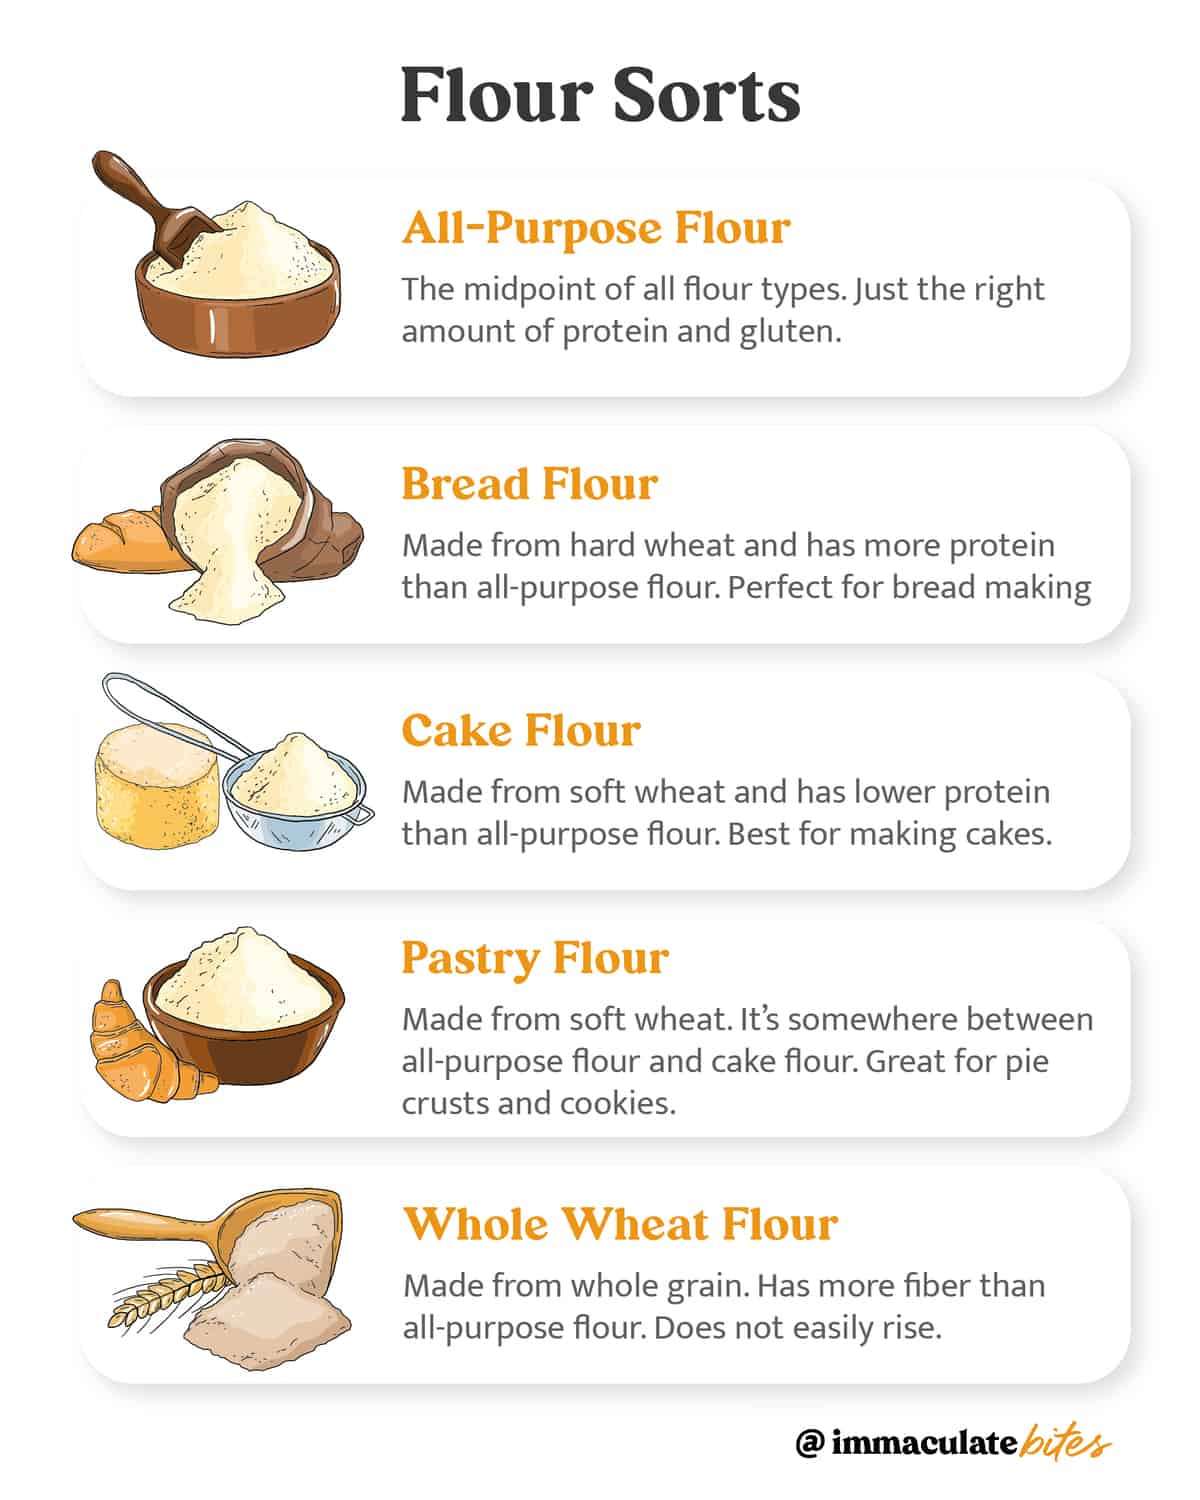
For decades, the “flour” of the financial world has been a predictable set of ingredients: a steady 9-to-5 job, a high-yield savings account, and perhaps a modest portfolio of blue-chip stocks. These were the staples that built the middle class and fueled the retirement dreams of millions. However, as global inflation erodes the purchasing power of traditional currency and automation shifts the landscape of the labor market, the fundamental building blocks of personal and business finance are changing. When we ask “what can replace flour,” we are really asking what new foundational assets can provide the stability and growth necessary to sustain a modern financial life.
In today’s volatile market, relying solely on traditional “staple” income is no longer a viable strategy for long-term wealth. The ingredients of financial success are being reformulated, shifting away from stagnant commodities toward dynamic, scalable, and decentralized assets. Understanding this shift is the first step in moving from a survivalist financial mindset to one of true abundance and resilience.
Redefining the Basic Ingredients of Wealth Generation
In a traditional sense, flour is a commodity—ubiquitous, low-margin, and easily substituted. In the world of money, this represents the standard hourly wage or the low-interest savings account. While these elements provide a base, they rarely lead to exponential growth. To build a robust financial future, one must identify “high-protein” substitutes that offer better leverage and resistance to economic decay.
The Shift from Labor-Intensive to Capital-Efficient Assets
The most significant replacement for traditional “flour” (manual or time-bound labor) is capital efficiency. Historically, the average person traded their time for a paycheck. Today, the wealthiest individuals focus on assets that decouple time from income. This includes dividend-paying stocks, automated business systems, and scalable digital products.
Unlike a traditional job where your income is capped by the number of hours you can physically work, capital-efficient assets allow for “infinite scalability.” For example, creating a digital course or a software-as-a-service (SaaS) platform requires a high upfront investment of time (the “kneading” process), but once established, the marginal cost of selling to one additional customer is near zero. This shift from “trading hours” to “owning systems” is the primary way modern entrepreneurs are replacing the thin margins of traditional employment.
Why Traditional “Safe” Investments Are Losing Their Rise
For nearly half a century, the 60/40 portfolio (60% stocks, 40% bonds) was the gold standard for financial stability. However, in an era of fluctuating interest rates and unprecedented government spending, bonds no longer provide the “yeast” they once did. They often fail to outpace inflation, meaning that “safe” money is effectively losing value every year.
Investors are now looking toward alternative assets to replace the bond portion of their portfolios. This includes private equity, venture capital, and even physical commodities like gold or timber. By diversifying into assets that have a low correlation with the traditional stock market, individuals can create a more resilient financial “dough” that can withstand various economic temperatures.
Digital Real Estate: The New Ground for Financial Growth
If physical land was the “wheat field” of the 19th and 20th centuries, digital real estate is the modern equivalent. The internet has created a new category of assets that behave much like physical property but with lower overhead and higher potential for appreciation.
Content Ecosystems as Sustainable Cash Flow
One of the most potent replacements for traditional income streams is the development of a content ecosystem. This includes niche websites, YouTube channels, and high-value newsletters. These platforms act as “digital storefronts” that generate revenue through advertising, affiliate marketing, and direct sales.
The beauty of digital real estate lies in its compounding nature. A well-written article or a well-produced video can generate income for years after its initial creation. In this context, “flour” is replaced by “attention.” If you can capture and hold a specific audience’s attention, you have a commodity that is far more valuable than a stagnant bank balance. This is the essence of the “Creator Economy,” where the fundamental ingredient of wealth is no longer physical labor but intellectual property.
Decentralized Finance (DeFi) vs. Traditional Banking
Another revolutionary substitute for traditional financial structures is the rise of Decentralized Finance (DeFi). For generations, we relied on banks to be the intermediaries of our money—taking our deposits (flour) and lending them out at a higher rate while giving us a pittance in return.
DeFi protocols allow individuals to become the “bank.” Through liquidity pooling and staking, investors can earn yields that significantly outperform traditional savings accounts. While this “new ingredient” comes with its own set of risks and volatilities, it represents a fundamental shift in how capital is deployed. By removing the middleman, individuals can capture a larger share of the value their capital creates, effectively replacing the low-yield “flour” of traditional banking with the high-octane “yeast” of blockchain-based finance.
Intellectual Property and the Automation of Revenue
In the quest to find what can replace the basic components of our financial lives, we must look at the power of the mind. Intellectual property (IP) has become the most valuable asset class in the global economy. It is the ultimate substitute for physical commodities because it is unique, protectable, and infinitely reproducible.
Licensing and Royalties in the Creator Economy
The move from “selling a product” to “licensing an idea” is a hallmark of sophisticated financial planning. Whether it is a patent for a mechanical device, a trademark for a brand, or a copyright for a book, IP allows for the generation of royalties. Royalties are a form of “evergreen” income—they keep coming in as long as the idea remains relevant.
In the modern landscape, even small-scale creators can tap into this. Licensing stock photography, selling templates on digital marketplaces, or white-labeling software are all ways to replace the “commodity” of labor with the “asset” of intellectual property. This transitions the individual from a participant in the economy to an owner of the economy’s underlying logic.
AI-Enhanced Scalability: Doing More with Less
Artificial Intelligence is perhaps the most disruptive “replacement” we have seen in centuries. AI serves as a catalyst that allows a single individual to perform the work that previously required an entire department. In financial terms, AI reduces the “cost of goods sold” for service-based businesses to near zero.
By leveraging AI tools for market analysis, content generation, and customer service, businesses can maintain high margins even in competitive environments. This “synthetic flour” allows for the creation of wealth without the traditional overhead of large payrolls. For the savvy investor or entrepreneur, the ability to integrate AI into their workflow is no longer an optional upgrade; it is the new baseline for staying competitive in a world where efficiency is the primary currency.
Diversifying Beyond the Commodity Mindset
To truly answer what can replace flour in a financial context, we must address the mindset of the investor. Many people are stuck in a “commodity mindset,” where they view their income as a fixed, limited resource that must be carefully rationed. To achieve true financial freedom, one must adopt a “value-based mindset.”
Moving from Hourly Wages to Value-Based Pricing
For the professional or freelancer, the most direct replacement for the “flour” of an hourly wage is value-based pricing. When you charge by the hour, you are selling a commodity (time). When you charge based on the value you provide to the client, you are selling a result.
This shift allows for exponential increases in income without a corresponding increase in workload. If you can solve a million-dollar problem in ten minutes, you should be paid for the million-dollar solution, not the ten minutes of labor. This is the ultimate “flour substitute” for the modern worker—the realization that the market pays for outcomes, not efforts.
Building Resilient Portfolios in Volatile Markets
Finally, replacing “flour” in a portfolio means moving toward “antifragility.” In his work, Nassim Taleb describes antifragility as something that gains from disorder. Traditional financial staples are often fragile; they break when the market crashes or inflation spikes.
A modern, resilient portfolio replaces these fragile elements with a mix of “barbell” strategies: holding extremely safe assets (like cash or short-term treasuries) on one end, and high-upside, speculative assets (like startups or crypto) on the other. By avoiding the “middle ground” of mediocre, low-growth assets, investors can protect their downside while leaving the door open for life-changing gains.
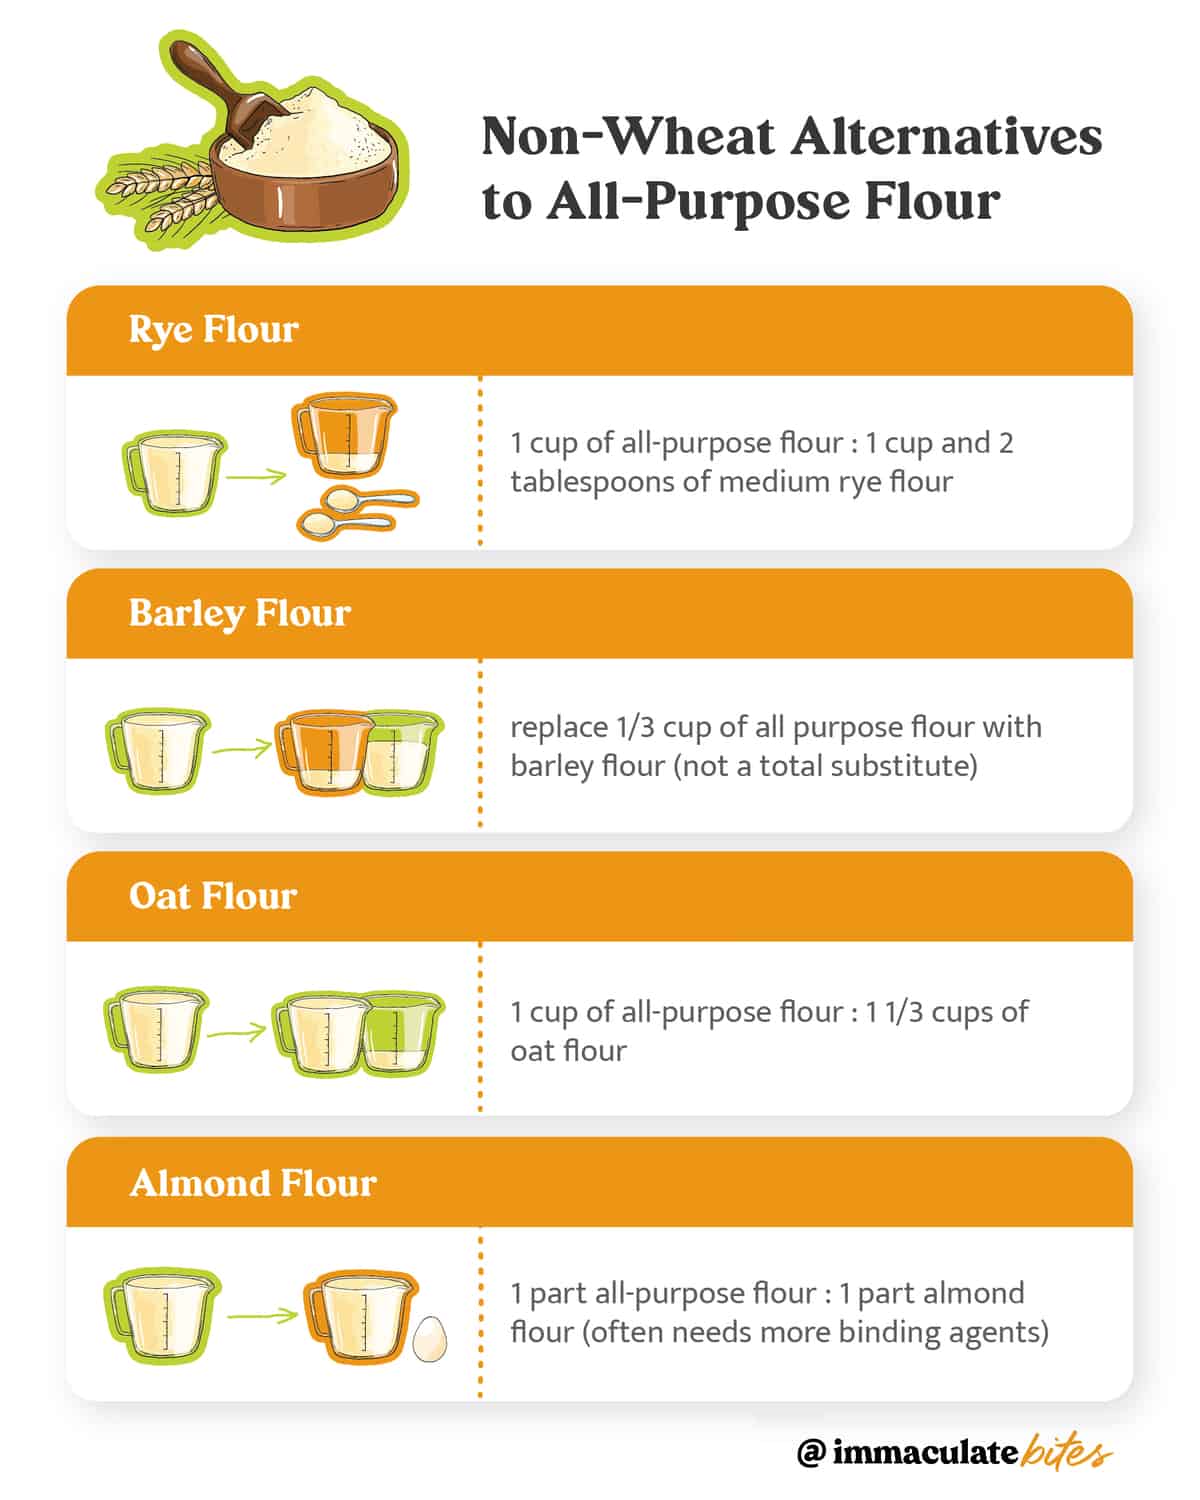
The search for what can replace flour leads us to a single conclusion: the foundations of wealth have moved from the physical to the digital, and from the general to the specific. By embracing capital efficiency, digital assets, intellectual property, and value-based pricing, we can bake a financial future that is far more nourishing than one built on the bland staples of the past. The “new flour” is not a single product, but a sophisticated blend of technology, strategy, and ownership that thrives in the modern age.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.