
The Genesis of a Digital Wallet
The story of Venmo, a ubiquitous name in peer-to-peer digital payments, begins not with a sprawling tech giant but with a simple, relatable problem faced by two college friends. In a world increasingly dominated by digital transactions, the act of splitting a dinner bill, paying a roommate for rent, or contributing to a group gift often still involved the awkwardness of cash or the delay of checks. The solution lay in leveraging the nascent power of mobile technology, an insight that would eventually revolutionize how millions interact with their money.
A Problem and a Vision: The Founders’ Insight
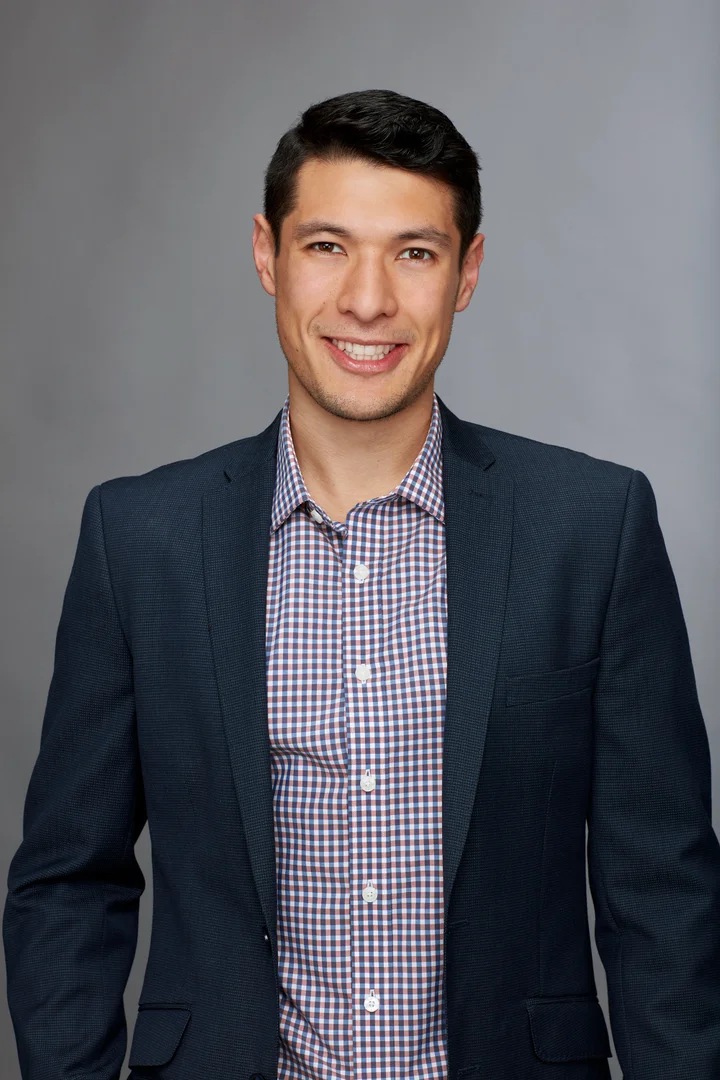
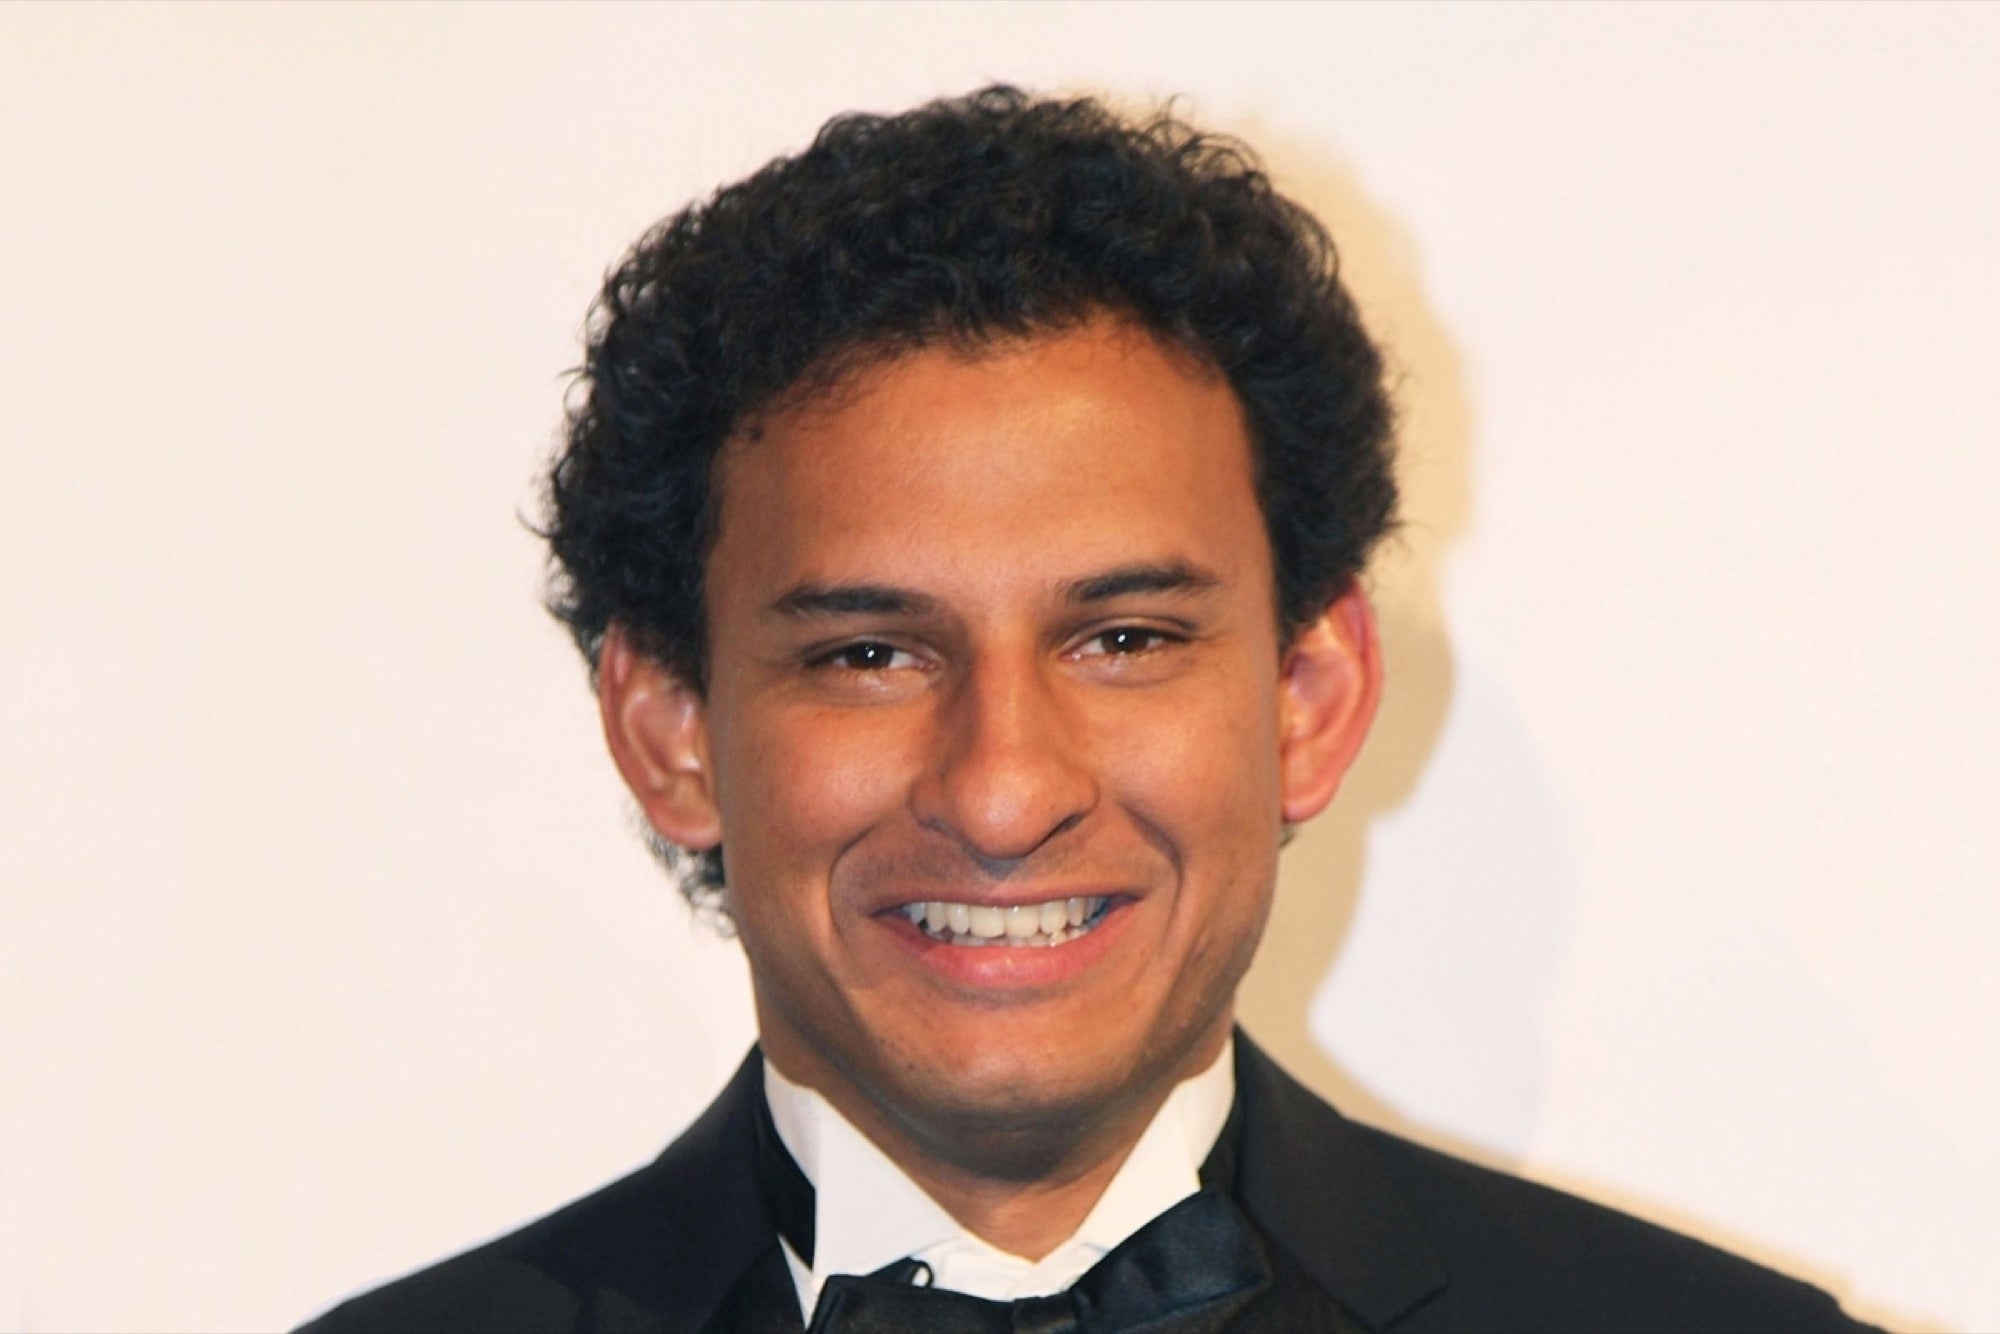
Venmo was born from the minds of Andrew Kortina and Iqram Magdon-Ismail, who met as freshmen at the University of Pennsylvania. Their initial entrepreneurial foray involved creating a ticketing and directory service, but a pivotal moment in 2009 shifted their focus. Magdon-Ismail, visiting Kortina, forgot his wallet. Kortina paid for everything, and an idea sparked: there had to be an easier, more immediate way to settle up than cash or a trip to an ATM. They envisioned a mobile application that could facilitate instant money transfers between friends, free from the traditional banking friction.
Their early prototype wasn’t even a payment app in the modern sense; it was a text message-based system for sending money using authorized SMS codes. This barebones approach highlighted their core understanding: the value wasn’t just in moving money, but in doing so conveniently and instantly through the devices people already carried. They recognized the potential of mobile phones to not only connect people socially but also to act as personal financial terminals, blurring the lines between communication and commerce. This foundational vision – to make payments seamless and almost invisible – became the bedrock upon which Venmo would be built.
From Concept to Code: Early Development
The evolution from a text-based experiment to a full-fledged mobile application required significant technical ingenuity and iteration. Kortina and Magdon-Ismail, both software developers, embarked on the challenging journey of coding the platform themselves. Their focus was on creating a user experience that was intuitive, reliable, and fundamentally mobile-first. This meant grappling with complex backend integrations with banking systems, ensuring robust security protocols for sensitive financial data, and designing a front-end interface that felt natural on a smartphone.
The initial versions of Venmo were developed with a strong emphasis on speed and accessibility. They understood that for a payment app to gain traction, it needed to remove as many barriers as possible. This included simplifying the sign-up process, making friend discovery easy, and, crucially, offering transfers without explicit fees (at least for standard transactions). The technological hurdles involved creating a reliable infrastructure that could handle real-time transactions, prevent fraud, and scale with anticipated user growth, all while delivering on the promise of instant, peer-to-peer financial interaction. Their dedication to robust software engineering in these early stages laid the groundwork for Venmo’s subsequent widespread adoption.
Engineering Simplicity: The Technology Behind Venmo
At its core, Venmo’s success is a testament to its elegant engineering, designed to abstract away the complexities of financial transactions into a simple, social interaction. The technical architecture was built to support instant transfers, foster a community aspect, and maintain high levels of security and reliability—all within the confines of a mobile device.
Building for Peer-to-Peer Convenience
The primary technological challenge for Venmo was to create a system that could reliably and instantly move money between individuals without the overhead and delays associated with traditional banking networks. This involved establishing secure connections with users’ bank accounts and debit cards, managing a digital ledger of balances, and orchestrating the actual transfer of funds. When a user “Venmos” another, the system doesn’t necessarily perform an immediate bank-to-bank wire transfer. Instead, it often updates internal balances instantaneously, giving the perception of immediate transfer, while the actual movement of funds between bank accounts may occur in the background via Automated Clearing House (ACH) transfers, which typically take longer.
To achieve this seamless experience, Venmo developed a sophisticated backend that includes:
-
API Integrations: Connecting securely to various bank and payment processor APIs to initiate and confirm transactions.
-
Database Management: Handling vast amounts of transaction data, user profiles, and balances with high availability and integrity.
-
Real-time Processing: Algorithms and infrastructure capable of processing a high volume of transactions with minimal latency, crucial for the “instant” feel.
-
Fraud Detection Systems: Employing machine learning and rule-based systems to identify and prevent fraudulent activities in real-time, a paramount concern in financial technology.
The focus was not just on moving money but on doing so with minimal friction, making the underlying technology practically invisible to the end-user. This commitment to user convenience through robust engineering became a defining characteristic of the platform.
The Mobile-First Imperative
From its inception, Venmo was conceived as a mobile application, a strategic decision that heavily influenced its technological development. This meant prioritizing design and functionality for smartphones, recognizing that a significant portion of its target demographic would conduct most of their digital activities on these devices.
Key aspects of its mobile-first engineering included:
-
Optimized User Interface (UI) and User Experience (UX): Designing touch-friendly interfaces that are intuitive and easy to navigate on smaller screens, simplifying complex financial interactions into a few taps.
-
Native App Development: Investing in native iOS and Android applications to leverage device-specific features (like push notifications for transaction alerts or biometric authentication for security) and ensure optimal performance.
-
Leveraging Device Capabilities: Utilizing phone contacts for easy friend discovery and integration, simplifying the process of finding and paying individuals without needing to remember account numbers.
-
Battery and Data Efficiency: Developing efficient code to minimize battery drain and data usage, critical for an app intended for frequent, on-the-go use.
The mobile-first strategy was not just about making a smartphone version of a website; it was about reimagining payments as an intrinsic mobile experience. This required a fundamental shift in technical thinking, putting the mobile device at the center of the financial transaction ecosystem and designing the entire technical stack around its capabilities and limitations.
Growth, Acquisition, and Integration
Venmo’s journey from a niche payment solution to a mainstream verb was punctuated by rapid user growth, strategic technological scaling, and a significant acquisition that integrated it into one of the world’s largest payment ecosystems. These phases were critical for solidifying its technical foundations and expanding its reach.
Scaling the Platform and User Experience
As Venmo gained popularity, the technical team faced the demanding challenge of scaling its infrastructure to accommodate millions of new users and billions of dollars in transactions. This required continuous innovation in backend architecture, database optimization, and cloud computing strategies. Scaling wasn’t just about adding more servers; it was about refactoring code, implementing more efficient algorithms, and ensuring that the user experience—speed, reliability, and security—did not degrade under increased load.
Key scaling efforts included:
-
Distributed Systems: Moving towards microservices architecture to break down the monolithic application into smaller, independently deployable services, improving resilience and scalability.
-
Cloud Infrastructure: Leveraging cloud providers to dynamically allocate resources based on demand, ensuring high availability and elasticity.
-
Database Sharding and Replication: Implementing strategies to distribute data across multiple databases to handle larger datasets and query volumes, enhancing performance and fault tolerance.
-
Enhanced Monitoring and Alerting: Deploying sophisticated monitoring tools to detect and respond to performance bottlenecks or security threats in real-time.
Simultaneously, the user experience continually evolved. Features like group payments, business profiles, and even cryptocurrency trading were introduced, each requiring significant backend development and careful integration into the existing app without complicating the core payment functionality. The user interface was periodically refreshed to maintain a modern aesthetic and adapt to new mobile OS guidelines, ensuring a consistent and intuitive experience.
Under the PayPal Umbrella: Synergies and Evolution
In 2012, Venmo was acquired by Braintree, a mobile payment platform, for $26.2 million. Just a year later, in 2013, PayPal acquired Braintree for $800 million. This acquisition marked a pivotal moment for Venmo, bringing it under the wing of an established global leader in digital payments. For Venmo, this meant access to PayPal’s vast financial infrastructure, regulatory expertise, and advanced security technologies.
The integration with PayPal was a delicate technical balancing act. While Venmo retained its distinct brand and social-first approach, it began to leverage PayPal’s robust backend systems for transaction processing, fraud prevention, and compliance. This integration allowed Venmo to scale more rapidly and securely than it might have independently. PayPal’s investment enabled Venmo to:
-
Enhance Security and Compliance: Adopting PayPal’s industry-leading security protocols and benefiting from their extensive experience with financial regulations globally.
-
Expand Payment Options: Utilizing PayPal’s relationships with banks and credit card networks to offer a wider array of funding sources and cash-out options.
-
Accelerate Feature Development: Accessing a larger pool of engineering talent and resources to expedite the development and deployment of new features, such as credit card issuance or merchant payments.
Crucially, PayPal allowed Venmo to maintain its unique identity and tech stack where it made sense, ensuring that the acquisition didn’t dilute the very aspects that made Venmo popular. This strategic integration allowed Venmo to evolve from a popular app to a cornerstone of the modern digital payment landscape, all while continuing to innovate on its core technology.
Venmo’s Enduring Tech Legacy
From its humble beginnings as a solution to a simple problem, Venmo has cemented its place as a significant player in the financial technology sector. Its creation and subsequent evolution represent a powerful case study in how thoughtful application development and strategic technological growth can redefine user expectations for financial services.
Shaping the Future of Social Payments
Venmo didn’t just facilitate payments; it socialized them. By integrating a feed of anonymized transactions, complete with emojis and short descriptions, it turned a typically private financial activity into a semi-public, engaging experience. This “social layer” was a technological innovation that differentiated it from traditional banking apps. It recognized that mobile users were accustomed to social feeds and brought that paradigm to finance.
The engineering behind this social feed involved:
-
Robust Privacy Controls: Allowing users to manage the visibility of their transactions, a critical feature for financial privacy.
-
Real-time Feed Generation: Constantly updating the feed with new transactions while efficiently managing data load and presentation.
-
Emoji and Text Processing: Handling and displaying diverse character sets and short-form text in a user-friendly manner.
This blend of social media and finance, initially seen as a novelty, fundamentally changed user perceptions of payment apps. It demonstrated that financial tools didn’t have to be sterile and purely transactional; they could be part of a broader digital lifestyle. Venmo paved the way for other apps to consider the social dimension of money, influencing how technology companies design user experiences around financial interactions.
Continued Innovation and Security Challenges
The tech journey of Venmo is far from over. In a rapidly evolving digital landscape, continuous innovation is key to maintaining relevance and competitiveness. Recent technological developments for Venmo include:
-
Cryptocurrency Integration: Allowing users to buy, hold, and sell select cryptocurrencies directly within the app, leveraging blockchain technology and secure digital asset management.
-
“Pay with Venmo” for Merchants: Expanding beyond peer-to-peer to enable users to pay businesses, requiring sophisticated API development and integration with merchant point-of-sale (POS) systems.
-
Enhanced Financial Tools: Introducing features like direct deposit, a Venmo Debit Card, and credit card, all necessitating complex banking system integrations and real-time ledger management.
Alongside innovation, maintaining and enhancing security remains a paramount technological challenge. As cyber threats evolve, Venmo’s engineering teams are continuously working on:
-
Advanced Encryption: Protecting user data both in transit and at rest with state-of-the-art cryptographic techniques.
-
Multi-Factor Authentication (MFA): Implementing robust MFA options to secure user accounts against unauthorized access.
-
Proactive Fraud Detection: Continuously improving machine learning models to detect suspicious transaction patterns and prevent fraud before it impacts users.
-
Regular Security Audits and Penetration Testing: Employing white-hat hackers and security experts to identify and patch vulnerabilities proactively.
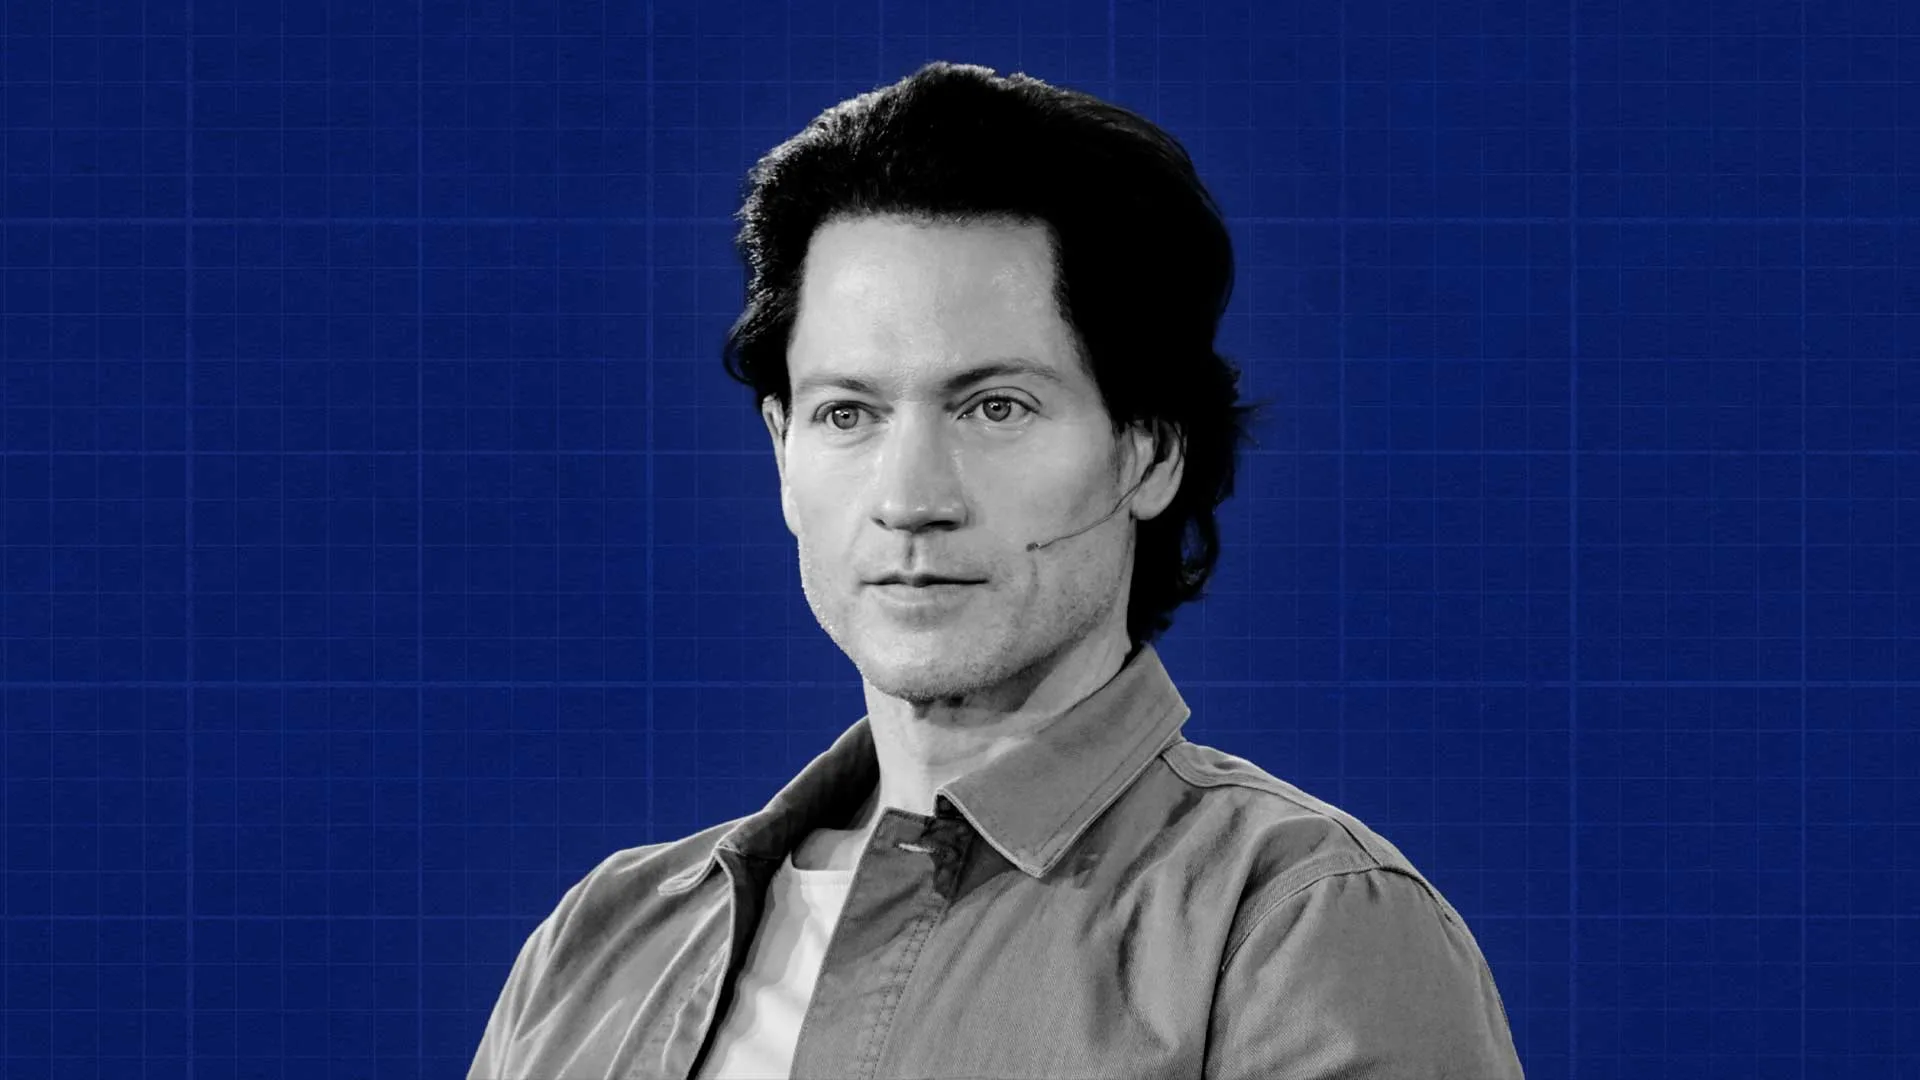
The creation of Venmo by Andrew Kortina and Iqram Magdon-Ismail was more than just launching an app; it was an act of technological foresight that reshaped how millions interact with money. Their initial vision, coupled with years of dedicated software engineering, strategic scaling, and continuous innovation, has ensured Venmo’s enduring legacy as a pioneer in digital payment technology.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.