
Securing a vehicle is one of the most significant financial commitments the average consumer will make, second only to the purchase of a home. Because a car is a depreciating asset, the method by which you finance it can have a profound impact on your long-term financial health. Choosing the wrong lender or a sub-optimal interest rate can result in thousands of dollars in unnecessary interest payments, potentially keeping you in a cycle of debt.
Understanding where to finance a car requires a deep dive into the various tiers of the lending ecosystem. From traditional brick-and-mortar institutions to the burgeoning world of financial technology, each path offers distinct advantages and inherent risks. To maximize your net worth and maintain healthy cash flow, you must evaluate these options through the lens of interest rates, loan terms, and total cost of ownership.
Traditional Banking Institutions and Credit Unions
For many, the first point of contact for an auto loan is a traditional financial institution. This category includes large national banks, local community banks, and member-owned credit unions. These institutions are often preferred by borrowers who value stability and have established financial histories.
The Advantage of Credit Unions
Credit unions are non-profit organizations owned by their members. Because they do not have to answer to shareholders, they are often able to return profits to their members in the form of lower interest rates and reduced fees. In the landscape of personal finance, credit unions are frequently cited as the most cost-effective place to finance a car.
Borrowers often find that credit unions offer more personalized service and a greater willingness to work with individuals who may have unique financial circumstances. Furthermore, credit unions often provide “gap insurance” and extended warranties at a fraction of the price charged by dealerships, making them an excellent choice for the budget-conscious consumer.
Commercial and National Banks
Large commercial banks offer the benefit of convenience and sophisticated digital tools. If you already hold a mortgage, credit card, or savings account with a major bank, you may qualify for “relationship pricing.” This can involve a small discount on your APR (Annual Percentage Rate) simply because you are an existing customer.
National banks are also highly efficient. Their automated underwriting systems can often provide a loan decision within minutes. However, their lending criteria tend to be more rigid than those of credit unions. Borrowers with excellent credit scores (typically 720 and above) will find these institutions highly competitive, while those with lower scores may find better terms elsewhere.
Dealership Financing and Captive Lenders
The most common place to finance a car is at the dealership itself. This is known as “indirect lending,” where the dealer acts as an intermediary between you and a financial institution. While convenient, this path requires a high degree of financial literacy to navigate effectively.
Captive Lenders: The Power of Manufacturer Incentives
Captive lenders are the financial arms of the car manufacturers themselves—think Ford Credit, Toyota Financial Services, or GM Financial. These entities exist primarily to help the manufacturer sell cars. Because of this, they often offer aggressive promotional rates that traditional banks cannot match, such as 0% or 0.9% APR for well-qualified buyers.
When a manufacturer offers 0% financing, it is essentially a marketing expense for them. From a wealth-management perspective, taking a 0% loan is almost always superior to paying cash, as it allows you to keep your capital invested in assets that earn a return while utilizing the manufacturer’s money for free. However, these deals are usually reserved for the highest credit tiers and may require you to forgo a cash-back rebate.
The Risks of “Buy Here Pay Here” Lots
On the opposite end of the dealership spectrum are “Buy Here Pay Here” (BHPH) establishments. These dealers serve the subprime market—borrowers with poor credit or no credit history. While they provide access to transportation for those who might otherwise be stranded, the financial cost is staggering.
BHPH loans often carry interest rates nearing the legal limit, sometimes exceeding 20% or 30%. Furthermore, these loans are often structured with weekly or bi-weekly payments that coincide with paychecks. From a personal finance standpoint, these loans are often considered “predatory” because they trap the borrower in a cycle of high-interest debt on a vehicle that may be worth significantly less than the loan balance.
Online Lenders and Fintech Platforms
The digital revolution has fundamentally altered how consumers access capital. Online lenders and financial technology (Fintech) platforms have introduced a level of transparency and competition that was previously unavailable.
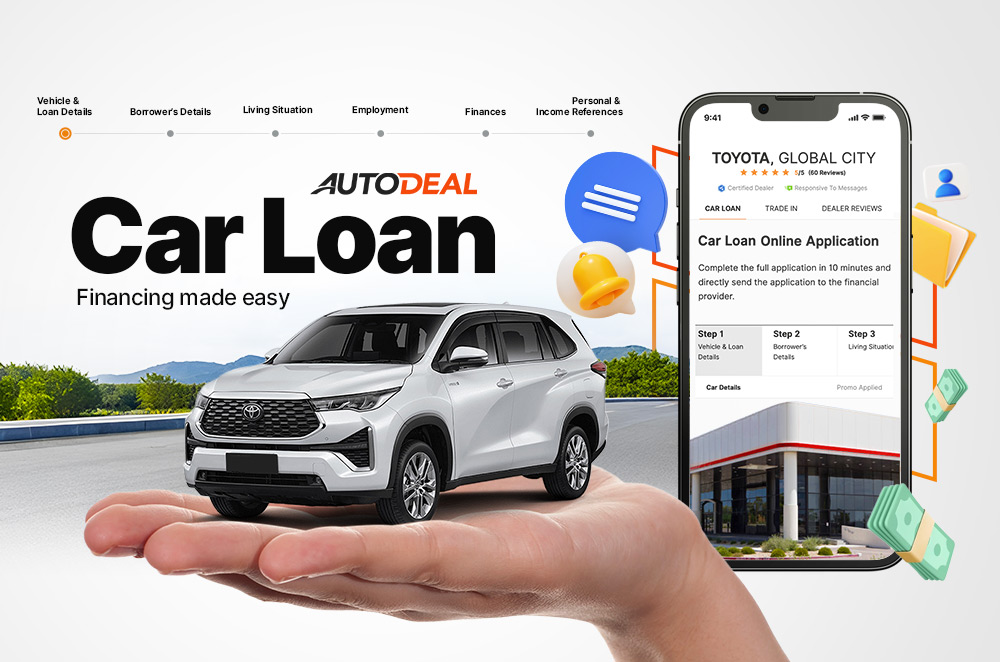
Direct Online Lenders
Specialized online lenders focus exclusively on auto financing and refinancing. Because they do not maintain physical branches, their overhead is significantly lower than that of traditional banks. They often pass these savings on to the consumer through lower rates.
Online lenders are particularly useful for those who want to secure “pre-approval” before stepping foot on a dealership lot. Having a pre-approval letter in hand shifts the power dynamic; it turns you into a “cash buyer” in the eyes of the salesperson, preventing the dealership from marking up the interest rate to increase their own profit margins.
Loan Aggregators and Comparison Tools
In the modern economy, data is power. Loan aggregators allow you to submit a single application that is then shopped around to dozens of different lenders. This creates a competitive environment where lenders must bid for your business.
Using these tools is a critical step in the “due diligence” phase of car buying. By comparing five or ten offers simultaneously, you can quickly identify the market rate for your specific credit profile. This prevents you from overpaying for credit and ensures that your debt-to-income ratio remains within healthy limits.
Strategies for Securing the Best Rates
Knowing where to look is only half the battle; knowing how to position your finances is what ultimately secures the best deal. Financing a car is a negotiation, and like any negotiation, the party with the most information and the best leverage wins.
The Role of Credit Scores and Reports
Your credit score is the single most important factor in determining the cost of your car loan. A difference of 100 points on your FICO score can translate into thousands of dollars in interest over the life of a five-year loan. Before seeking financing, it is imperative to review your credit report for errors and pay down high-interest revolving debt to lower your credit utilization ratio.
If your credit is in the “fair” or “poor” range, it may be financially prudent to delay the purchase by six months to a year while you work on credit repair. Moving from a 12% interest rate to a 5% interest rate on a $30,000 loan saves approximately $5,000 in interest—a significant boost to your personal savings rate.
Understanding the Total Cost of Ownership
A common mistake in car financing is focusing solely on the monthly payment. Shrewd financial planners focus on the “Total Cost of Ownership” (TCO) and the total interest paid over the life of the loan.
Lenders often attempt to lower monthly payments by extending the loan term to 72 or 84 months. While this makes the car seem affordable on a month-to-month basis, it significantly increases the total interest paid and increases the risk of becoming “upside down” on the loan (owing more than the car is worth). Aim for the shortest term you can afford—ideally 48 to 60 months—to ensure you are building equity in the asset as quickly as possible.
Evaluating the Fine Print: Beyond the Interest Rate
When choosing where to finance, the interest rate is the headline, but the fine print contains the details that can protect or erode your wealth. A professional approach to financing involves scrutinizing the loan agreement for several key factors.
Prepayment Penalties and Fees
Some lenders include prepayment penalties in their contracts. If you receive a year-end bonus or a tax refund and wish to pay down your car loan early, a prepayment penalty would charge you a fee for doing so. From a wealth-building perspective, you should always seek loans with no prepayment penalties. This gives you the flexibility to eliminate debt faster as your income grows.
Additionally, be wary of “documentation fees” or “origination fees” that some online lenders and dealerships tack onto the loan balance. These fees are essentially hidden interest. When comparing loans, always look at the APR, not just the interest rate, as the APR includes these additional costs.

The Importance of Pre-Approval
Regardless of where you ultimately decide to finance, the act of getting pre-approved is a vital financial tactic. Pre-approval involves a hard credit inquiry, but it provides you with a firm offer of credit for a specific amount at a specific rate.
With a pre-approval in your pocket, you can walk into a dealership and say, “I have financing at 4.5% from my credit union. Can you beat it?” This forces the dealership’s finance manager to work on your behalf to find a better rate from their network of lenders. If they can’t beat it, you already have your funding secured. This strategy ensures you never pay more for credit than the market dictates.
In conclusion, the question of where to finance a car is a question of mathematical optimization. By leveraging the competitive rates of credit unions, the promotional incentives of captive lenders, and the transparency of online Fintech platforms, you can minimize the cost of your debt. In the world of personal finance, the money saved on interest is money that can be redirected toward investments, retirement accounts, and long-term wealth creation. Approaching car financing with this level of rigor transforms a simple consumer purchase into a strategic financial decision.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.