
The anticipation that builds as the clock nears 10:59 p.m. Eastern Time on drawing nights is a phenomenon that transcends mere curiosity; it is a cultural fixture of the American financial landscape. While the quest for tonight’s winning numbers is the immediate priority for millions of ticket holders across 45 states, the District of Columbia, Puerto Rico, and the U.S. Virgin Islands, the Powerball represents more than a game of chance. It is a complex financial instrument that, when navigated correctly, can transform from a simple $2 wager into a life-altering estate. Understanding the mechanics of the draw, the odds of the payout, and the immediate financial protocols required upon winning is essential for any participant engaged in this high-stakes pursuit of personal finance.
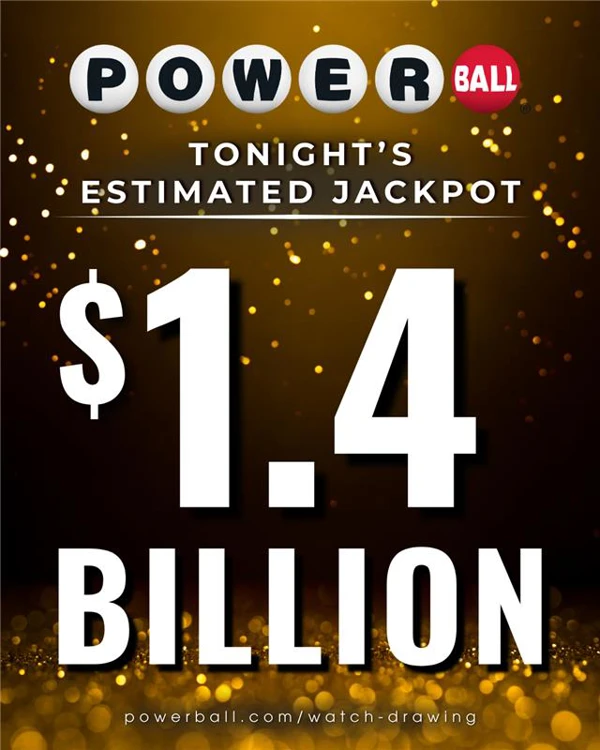
The Financial Landscape of the Powerball: Beyond the Drawing
To effectively engage with the Powerball, one must first understand the structural framework of the game. Drawings are held every Monday, Wednesday, and Saturday. Participants select five numbers from a pool of 1 to 69 (the white balls) and one number from a pool of 1 to 26 (the red Powerball). While the primary focus is often the grand jackpot, the secondary prize tiers offer varying degrees of return on investment (ROI) that are frequently overlooked by the casual player.
The Mechanics of the Prize Tiers
The Powerball is structured into nine distinct prize levels. While the odds of hitting the jackpot are a staggering 1 in 292.2 million, the odds of winning any prize are a much more approachable 1 in 24.87. From a personal finance perspective, the “Power Play” option—an additional $1 per play—serves as a multiplier for non-jackpot prizes. For an investor in the game, this feature can significantly increase the yield on lower-tier wins, potentially turning a $50,000 prize into $100,000 or more, depending on the multiplier drawn.
Understanding the Odds and Probability
The mathematical reality of the Powerball is a study in extreme probability. To put the 1 in 292.2 million odds into perspective, one is statistically more likely to be struck by lightning, become a professional athlete, or even be elected to high office. However, from a business finance perspective, the Powerball operates on the principle of pooled resources. The massive jackpots are a result of “roll-overs,” where no ticket matches all six numbers, causing the prize pool to grow exponentially. This growth often triggers a “frenzy” effect, where increased ticket sales further accelerate the jackpot’s rise, creating a unique cycle of liquidity within the lottery system.
The Critical First Steps: A Financial Roadmap for the Newly Wealthy
If your numbers match those drawn tonight, the transition from a standard income earner to an ultra-high-net-worth individual (UHNWI) happens in an instant. This sudden wealth requires a disciplined financial protocol to ensure that the windfall is protected and managed for long-term growth rather than being depleted by immediate emotional spending or poor fiscal oversight.
Securing the Asset
The physical ticket is a “bearer instrument,” meaning that, in many jurisdictions, whoever holds the ticket is the legal owner of the prize. The first step for any winner is to sign the back of the ticket and secure it in a safe-deposit box or a high-security home safe. Before coming forward, it is often advisable to make digital and physical copies of the ticket to document the claim.
Assembling a Fiduciary Team
The most common mistake lottery winners make is attempting to manage the windfall without professional guidance. A winner should immediately assemble a “wealth council” consisting of three key professionals:
- A Tax Attorney: To navigate the complex state and federal tax codes.
- A Certified Public Accountant (CPA): To manage immediate tax filings and liquidity.
- A Fee-Only Fiduciary Financial Advisor: Unlike commission-based brokers, a fiduciary is legally obligated to act in the client’s best interest, which is critical when managing hundreds of millions of dollars.
Protecting Anonymity and Privacy
In the age of digital information, privacy is a valuable financial asset. Only a handful of states allow lottery winners to remain completely anonymous. In other jurisdictions, winners may be able to claim the prize through a “Blind Trust” or a Limited Liability Company (LLC). This legal maneuver can shield the winner’s identity from the public, preventing the influx of unsolicited requests for money and protecting the individual from potential security risks.
Evaluating the Payout: Lump Sum vs. Annuity Through a Financial Lens

Perhaps the most significant financial decision a Powerball winner faces is whether to take the prize as a one-time lump sum or as a 30-payment annuity. This is not merely a choice of preference; it is a sophisticated calculation involving the time value of money, projected inflation, and investment risk appetite.
The Case for the Cash Option (Lump Sum)
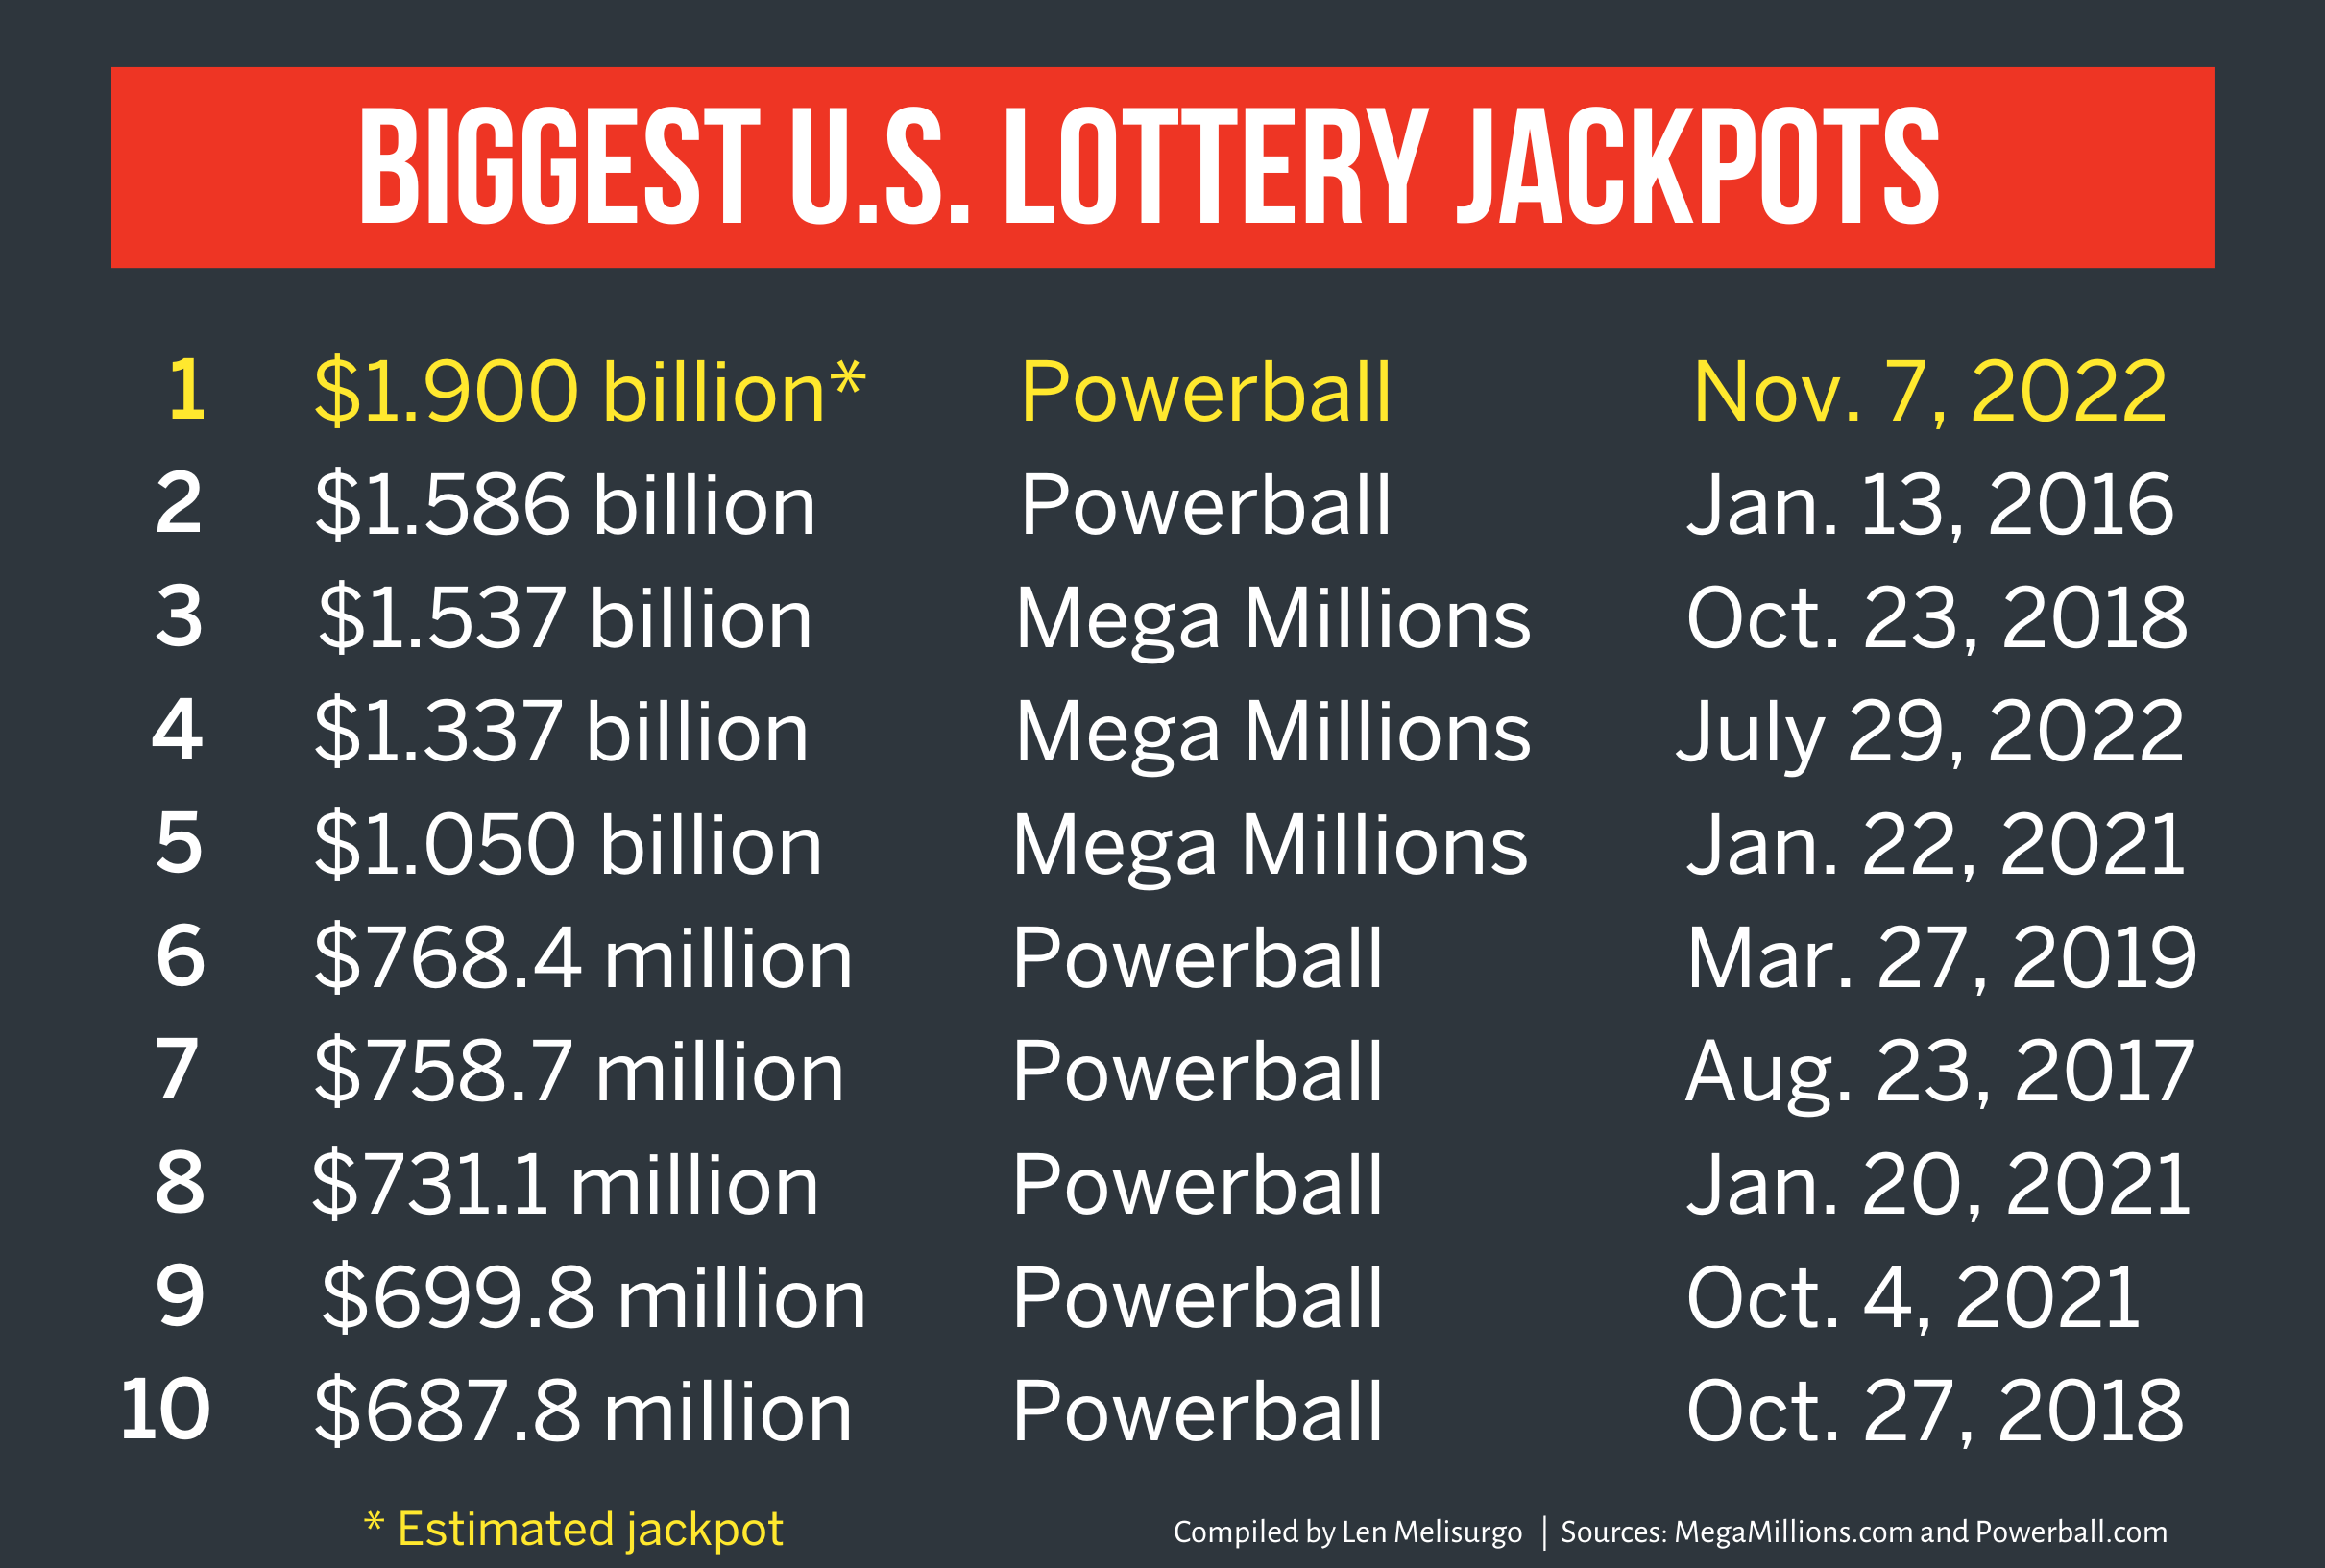
The lump sum, or “cash value,” represents the actual cash currently in the Powerball prize pool. While this amount is significantly lower than the advertised jackpot (which is based on the annuity’s total payout over 30 years), it offers the winner immediate control over the capital. From an investment standpoint, the lump sum is often preferred by those who believe they can generate a higher rate of return through diversified portfolios than the internal rate of return offered by the annuity. If invested in a mix of equities, real estate, and fixed-income assets, the lump sum can potentially outgrow the annuity over a 30-year horizon.
The Case for the 30-Year Annuity
The annuity option provides one immediate payment followed by 29 annual payments that increase by 5% each year. This structure offers a unique form of “forced discipline” and serves as a hedge against the “lottery curse”—the well-documented phenomenon of winners losing their fortunes within a few years. For individuals who are concerned about their ability to manage a massive influx of capital or who wish to guarantee a lifestyle of extreme luxury for three decades regardless of market volatility, the annuity is a powerful tool for financial security.
Tax Obligations and the Reality of Net Earnings
It is a common misconception that the advertised Powerball jackpot is the amount the winner takes home. In reality, the “winning numbers” are just the beginning of a significant tax event. Both federal and state governments view lottery winnings as ordinary income, and the tax implications are substantial.
Federal Withholding and the 37% Bracket
The IRS requires an immediate 24% federal withholding on all lottery prizes over $5,000. However, because a jackpot win easily places the individual in the highest federal income tax bracket (currently 37%), the winner will likely owe an additional 13% when they file their annual tax return. This means that more than a third of the prize is earmarked for the federal government before a single dollar is spent on investments or lifestyle upgrades.
State-Level Tax Considerations
State taxes vary wildly. Winners in states like Florida, Texas, Nevada, and Washington enjoy the benefit of no state income tax on lottery winnings. Conversely, winners in states like New York or New Jersey may face an additional 8% to 10% in state taxes. When calculating the “true” winning numbers, one must subtract these liabilities to determine the actual liquid capital available for wealth management.
Sustainable Wealth Management: Strategies for Long-Term Growth
Once the taxes are paid and the payout method is selected, the focus shifts to wealth preservation. The goal is to transition the lottery win into a sustainable financial legacy. This involves a shift from a “lottery mindset” to an “endowment mindset.”
The Endowment Model of Investing
Large institutional funds, such as those of Ivy League universities, use an endowment model that focuses on extreme diversification and a long-term horizon. A Powerball winner should look beyond simple stocks and bonds, incorporating alternative investments such as private equity, venture capital, and commercial real estate. By diversifying across asset classes, the winner can protect their principal against market downturns while generating sufficient cash flow to fund their lifestyle.
Philanthropy and Estate Planning
For many winners, the ultimate financial goal is to provide for future generations and support charitable causes. Establishing a Private Foundation or a Donor-Advised Fund (DAF) can provide significant tax benefits while allowing the winner to direct their wealth toward meaningful social impact. Additionally, sophisticated estate planning—including the use of Irrevocable Life Insurance Trusts (ILITs) and Generation-Skipping Trusts—is essential to mitigate the impact of federal estate taxes, which can be as high as 40% on estates exceeding certain thresholds.
Ultimately, while the search for tonight’s winning numbers is driven by the hope of a financial breakthrough, the true victory lies in the disciplined management of the resulting wealth. By treating a lottery win not as a windfall to be spent, but as a capital base to be invested, a winner can ensure that their “lucky numbers” provide financial freedom for a lifetime and beyond.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.