
The pursuit of the Powerball jackpot is a cultural phenomenon that transcends simple gambling; it represents the ultimate financial “black swan” event. While millions of players across the country scour official results for those five white balls and the red Powerball, the realization of a winning ticket is only the beginning of a complex financial journey. For those asking what the winning numbers were for tonight, the answer provides more than just a momentary thrill—it serves as the catalyst for a total transformation of one’s personal finance landscape.
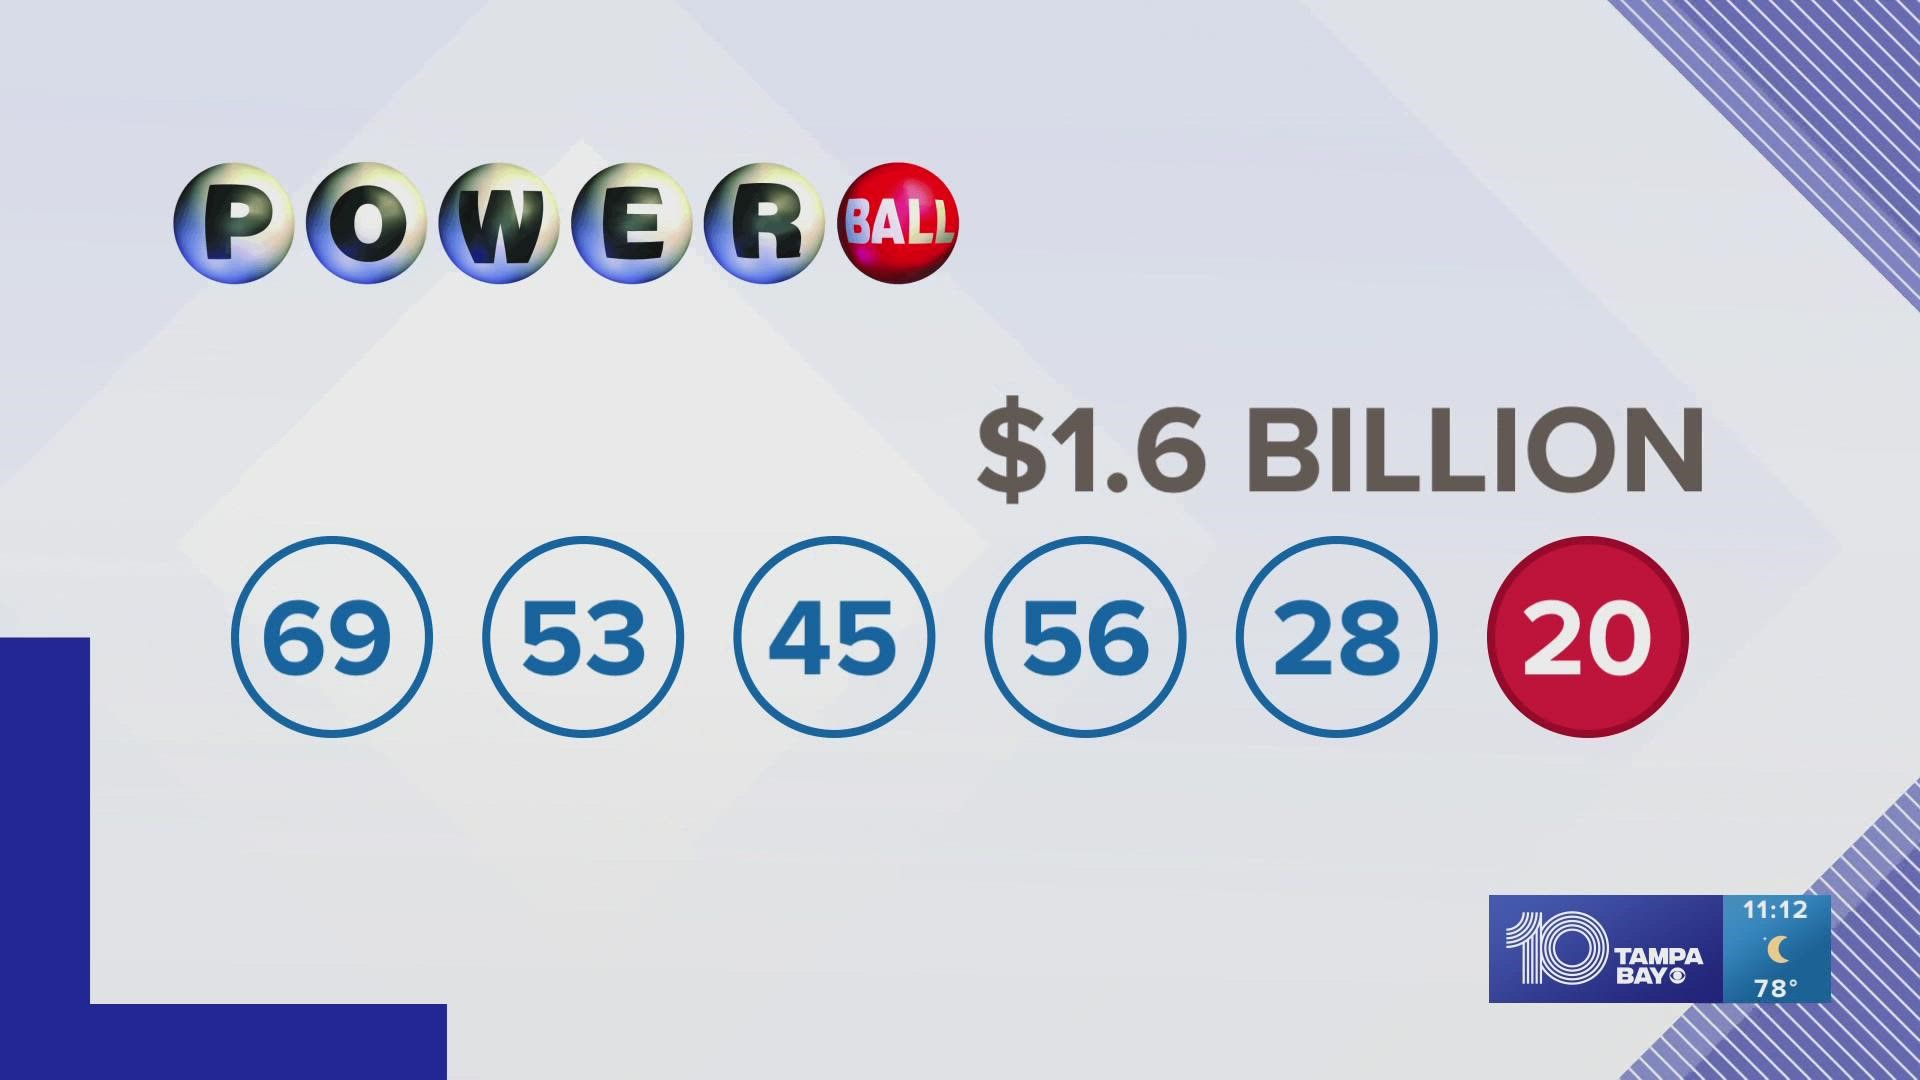
Understanding the numbers is the first step, but managing the resulting wealth requires a level of financial literacy that most individuals are rarely prepared for. A jackpot win is not just a “payday”; it is the acquisition of a multi-generational asset that demands rigorous strategy, tax planning, and a disciplined approach to wealth preservation.
The Immediate Response: Beyond the Winning Numbers
When the winning numbers are announced, the instinctual reaction is often one of immediate celebration. However, from a professional financial perspective, the period immediately following a win is the most critical for long-term stability. The “winning numbers” are merely the key to a door that leads to a vast, complex financial ecosystem.
Securing the Physical and Digital Asset
The moment a player confirms their numbers match the draw, the ticket transitions from a piece of thermal paper to a bearer instrument worth hundreds of millions of dollars. Financial experts recommend immediate physical security—placing the ticket in a safe deposit box—and, crucially, seeking legal counsel before even signing the back. In some jurisdictions, signing the ticket can limit the ability to claim the prize through a blind trust or an LLC, which are essential tools for maintaining privacy.
The Power of Silence and Professional Assembly
Before the winning numbers are even publicized by major news outlets, the winner should begin assembling a “wealth team.” This team typically includes a tax attorney, a certified public accountant (CPA) with experience in high-net-worth individuals, and a fee-only financial advisor. The objective during this “quiet period” is to prepare for the liquidity event before the public or extended family members become aware of the change in financial status. This is the foundation of personal brand protection and long-term asset security.
The Pivotal Choice: Lump Sum vs. Annuity
Perhaps the most significant financial decision a Powerball winner faces is the choice between the lump-sum cash option and the 30-payment annuity. This is a classic exercise in the time value of money, requiring a deep dive into projected market returns, inflation, and tax brackets.
The Case for the Lump Sum
The cash option provides immediate liquidity. For those with a sophisticated understanding of investing or access to high-tier wealth management, the lump sum is often the preferred route. By taking the money upfront, the winner can immediately diversify into various asset classes—equities, real estate, private equity, and municipal bonds. The primary advantage here is control. In a high-inflation environment, having the capital available to hedge against devaluing currency is a powerful tool. However, it requires a high degree of discipline to avoid the “lottery curse” of overspending in the first twenty-four months.
The Case for the Annuity
The annuity option, which consists of 30 graduated payments over 29 years, offers a built-in safety net. Each payment is 5% larger than the last, providing a hedge against lifestyle creep and ensuring that even if the winner makes poor financial decisions in the early years, they will have a “reset” button every twelve months. From a tax perspective, the annuity can also be beneficial if future tax laws become more favorable, though it leaves the winner vulnerable to the risk of rising tax rates over the next three decades.
Navigating the Tax Landscape of Sudden Wealth

The “winning numbers” represent the gross prize, but the net reality is significantly different. In the United States, lottery winnings are treated as ordinary income by the IRS, and the tax implications are immediate and substantial.
Federal Withholdings and the Top Bracket
The moment a prize is claimed, the lottery jurisdiction is required to withhold 24% for federal taxes. However, since the top federal tax bracket is currently 37%, winners will likely owe an additional 13% when they file their annual returns. On a $500 million jackpot, that 13% gap represents a $65 million liability that must be accounted for in the first year’s financial planning. Failing to set aside these funds can lead to catastrophic financial failure.
State and Local Tax Variances
Geographic location plays a massive role in the final “take-home” amount. States like Florida, Texas, and Nevada do not tax lottery winnings at the state level, allowing winners to retain a larger portion of their windfall. Conversely, winners in New York or New Jersey may face state tax rates exceeding 8% or 10%, in addition to potential city taxes. Professional tax planning involves analyzing these liabilities and identifying legal strategies—such as charitable lead trusts or donor-advised funds—to mitigate the total tax burden while fulfilling philanthropic goals.
Strategic Asset Allocation and Wealth Preservation
Once the taxes are paid and the initial excitement has subsided, the focus must shift to wealth preservation. Moving from a mindset of “winning” to a mindset of “investing” is what separates those who build legacies from those who return to their original financial state within a decade.
Diversification Beyond the Traditional
A massive windfall allows for entry into investment vehicles that are often closed to the general public. While a core portfolio should consist of low-cost index funds and high-grade bonds to ensure base stability, a Powerball-sized fortune should also be diversified into:
- Private Equity and Venture Capital: For long-term growth and exposure to emerging technologies.
- Commercial Real Estate: For passive income streams and tax depreciation benefits.
- Hard Assets: Including precious metals or high-value collectibles, which serve as a store of value during period of geopolitical instability.
The Role of an Investment Policy Statement (IPS)
A professional financial advisor will help the winner draft an Investment Policy Statement. This document outlines the goals, risk tolerance, and liquidity requirements of the portfolio. It acts as a constitution for the winner’s wealth, preventing impulsive emotional decisions during market volatility. By adhering to an IPS, the winner ensures that the “winning numbers” tonight translate into financial security for the next century.
The Psychology of Sudden Wealth and Social Capital
Money is as much a psychological phenomenon as it is a mathematical one. The “winning numbers” for Powerball tonight can create a “Sudden Wealth Syndrome,” characterized by anxiety, isolation, and a loss of identity.
Managing Social Expectations
One of the greatest threats to a large fortune is “leakage” through unvetted loans or gifts to friends and family. Establishing a formal process for charitable requests—often through a family foundation or a professional gatekeeper—allows the winner to maintain personal relationships without the constant pressure of financial solicitation. This is a critical component of “Business Finance” applied to the individual; treating the jackpot as a family office or a business entity provides the necessary distance to make objective decisions.

Identity and Purpose Post-Win
Financial freedom is the ultimate goal of personal finance, but total freedom can lead to a lack of structure. Successful winners often pivot toward philanthropy, entrepreneurship, or a deep pursuit of education. By viewing the windfall as a tool for impact rather than just a source of consumption, winners can navigate the complex social dynamics that follow a public announcement of wealth.
In conclusion, while the search for “what were the winning numbers for Powerball tonight” is driven by the hope of a life-changing event, the reality of that change requires a sophisticated financial infrastructure. From the immediate security of the ticket to the long-term nuances of asset allocation and tax mitigation, managing a lottery win is a full-time endeavor in professional wealth management. The numbers are just the beginning; the strategy determines the legacy.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.