
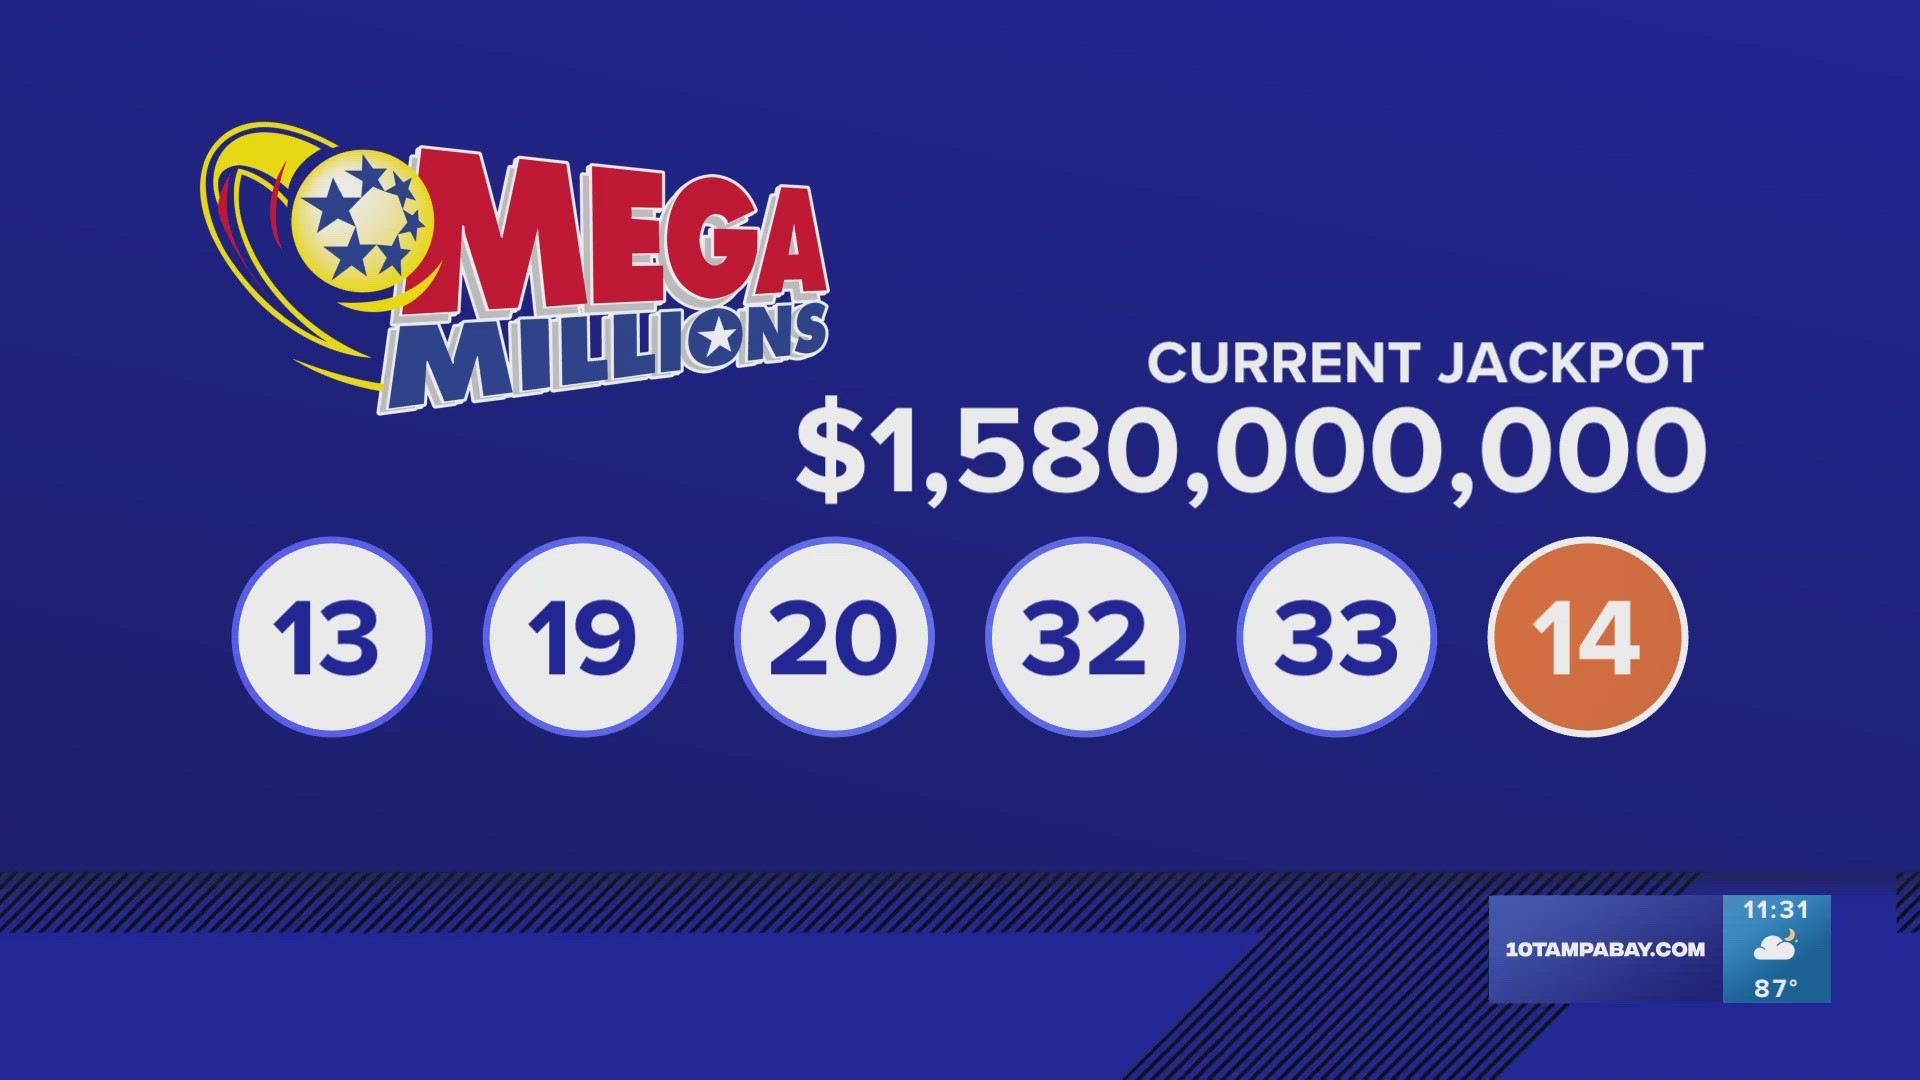
The search for the winning Mega Millions numbers is often driven by a universal human aspiration: the desire for total financial freedom. Whether you are checking your ticket in hopes of a life-altering windfall or simply curious about the latest multimillionaire created by the draw, the numbers represent more than just digits on a screen—they represent a fundamental shift in economic status. However, in the world of personal finance, the “win” is only the beginning. Transforming a stroke of luck into a multi-generational legacy requires a sophisticated understanding of tax law, investment strategy, and wealth preservation.

For those who find their numbers matching the draw, the immediate rush of adrenaline must quickly give way to disciplined financial planning. Managing a sudden influx of capital is a complex endeavor that goes far beyond simple consumption. It involves navigating the “sudden wealth syndrome,” making critical decisions regarding payout structures, and building a professional team to insulate your new assets from unnecessary risk.
The Financial Architecture of a Jackpot: Lump Sum vs. Annuity
When the winning numbers align, the first and most consequential financial decision a winner faces is the choice between the cash option (lump sum) and the annuity payout. This decision is a classic exercise in the time value of money, a core principle of finance that dictates a dollar today is worth more than a dollar tomorrow due to its potential earning capacity.
The Time Value of Money and the Lump Sum
The lump sum is typically the net present value of the advertised jackpot. While the figure is significantly lower than the headline-grabbing number, it provides the winner with immediate liquidity. From a strategic investment perspective, the lump sum is often favored by those who believe they can achieve a higher rate of return through private investments, equity markets, or real estate than the implied interest rate of the lottery’s annuity.
By taking the cash upfront, an investor can immediately diversify their portfolio. In a high-inflation environment, having the capital available to purchase hard assets or participate in market downturns can be a powerful wealth-building tool. However, this path requires immense discipline; the primary risk of the lump sum is “lifestyle creep” and the rapid depletion of principal.
The Annuity: A Hedge Against Behavioral Risk
The Mega Millions annuity is paid out over 30 graduated payments, increasing by 5% each year. From a behavioral finance standpoint, the annuity acts as a safety net. It prevents the winner from losing the entirety of their fortune in a single decade of poor choices. For individuals without a background in capital management, the annuity provides a steady, predictable cash flow that mirrors a high-level executive salary, ensuring financial security for three decades.
Furthermore, the annuity can offer certain tax advantages. By spreading the income over 30 years, the winner may avoid being taxed at the highest marginal rate on the entire sum in a single year, though for a jackpot of this size, the top federal bracket is almost always triggered regardless of the choice.
Navigating the Tax Landscape of Sudden Wealth
The moment the winning numbers are verified, the Internal Revenue Service (IRS) becomes your primary financial partner. Understanding the tax implications is vital to calculating the actual “take-home” pay and planning future expenditures.
Federal Withholdings and Marginal Brackets
The lottery office is required to withhold 24% of winnings for federal taxes immediately. However, this is rarely the final bill. Because a Mega Millions win puts the recipient well into the highest federal income tax bracket—currently 37%—the winner will likely owe an additional 13% when filing their annual return. Strategic tax planning, such as maximizing charitable contributions or investing in tax-advantaged vehicles, must begin immediately to mitigate this liability.
State and Local Considerations
State taxes vary wildly and can significantly impact the net gain. Residents in states like Florida, Texas, or Washington enjoy a 0% state tax on winnings, while those in New York or New Jersey may see an additional 8% to 10% deducted. For winners in high-tax jurisdictions, the “advertised” jackpot is often less than half of what eventually hits their bank account after all government entities have taken their share.
Gift Taxes and Family Wealth Transfer
Many winners feel an immediate urge to share their wealth with friends and family. However, the IRS views these as “gifts.” As of current tax law, there is an annual exclusion limit per person. Amounts exceeding this limit count toward the lifetime gift and estate tax exemption. Without a structured plan involving Crummey trusts or family limited partnerships, a winner could inadvertently trigger a 40% gift tax, significantly eroding the amount intended for their loved ones.
Building a Professional Wealth Management Team
A common thread among “lottery curses”—stories of winners who go bankrupt within years—is the absence of professional guidance. A windfall of this magnitude requires a fiduciary team that operates with the winner’s best interests in mind.
The Role of the Fiduciary Financial Advisor
Unlike traditional brokers, a fiduciary is legally obligated to act in the client’s best interest. For a lottery winner, this advisor helps construct a diversified portfolio aimed at capital preservation and long-term growth. The goal is to move the money from a “windfall” category into a “sustainable income” category, ensuring that the principal remains untouched while the interest funds the winner’s lifestyle.
Legal Counsel and Asset Protection
Privacy is the first casualty of winning the Mega Millions. In states where winners cannot remain anonymous, the influx of solicitation and potential litigation is a serious threat. An experienced attorney is necessary to set up legal entities—such as blind trusts or Limited Liability Companies (LLCs)—to hold the winnings. These structures provide a layer of anonymity and protect the assets from predatory lawsuits or unscrupulous claimants.
The Certified Public Accountant (CPA)
A CPA specialized in high-net-worth individuals is essential for navigating the complex filing requirements that follow a major win. From quarterly estimated tax payments to managing the complexities of diverse investment holdings, the CPA ensures that the winner remains compliant with all tax codes while identifying opportunities for tax efficiency.
The Psychological Economy of a Jackpot
While the numbers are a matter of math, the impact of winning is a matter of psychology. “Sudden Wealth Syndrome” is a recognized phenomenon where individuals experience stress, anxiety, and social isolation following a massive financial gain.
Establishing a “Cooling Off” Period
The most successful winners are often those who do nothing for the first several months. By keeping the winning ticket in a secure location (like a bank safety deposit box) and continuing their normal life for a short period, they allow the initial shock to subside. This prevents impulsive purchases—like luxury real estate or high-end vehicles—that carry high maintenance costs and property tax burdens that can drain liquidity.
Defining “Enough”
The key to long-term financial health is defining “enough.” In the context of a Mega Millions win, it is easy to lose perspective on the value of money. Establishing a clear budget that accounts for both “fun money” and long-term capital requirements is essential. Wealth is not just the ability to buy things; it is the ability to sustain a desired lifestyle indefinitely.
Strategic Asset Allocation for Longevity
Once the initial taxes are paid and the professional team is in place, the focus shifts to asset allocation. A jackpot should be viewed as a private endowment.
Diversification Beyond the Public Markets
While stocks and bonds are the bedrock of any portfolio, a jackpot-sized net worth allows for entry into alternative investments. This includes private equity, venture capital, and institutional-grade real estate. These assets often have lower correlation with the public markets, providing a hedge against economic volatility.
Philanthropy and Impact Investing
For many, the ultimate goal of wealth is the ability to effect change. Setting up a private foundation or a Donor-Advised Fund (DAF) allows a winner to support causes they care about while receiving an immediate tax deduction. Beyond the tax benefits, structured philanthropy provides a sense of purpose and a framework for managing the social pressures that come with great wealth.

Education and Intergenerational Planning
The final stage of managing a Mega Millions win is ensuring the wealth lasts for future generations. This involves not just leaving money behind, but educating heirs on financial literacy. Dynasty trusts can be utilized to pass wealth down through generations while protecting the assets from the risks of divorce, bankruptcy, or mismanagement by future descendants.
In conclusion, the winning Mega Millions numbers represent a doorway to a new financial reality. To walk through that door successfully, one must move beyond the excitement of the draw and embrace the rigorous demands of high-level wealth management. By focusing on tax efficiency, legal protection, and strategic investment, a winner can ensure that their “lucky numbers” translate into a permanent foundation of financial security and influence. Regardless of whether you held the winning ticket last night, the principles of disciplined saving, professional advice, and long-term planning remain the true keys to financial freedom.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.