
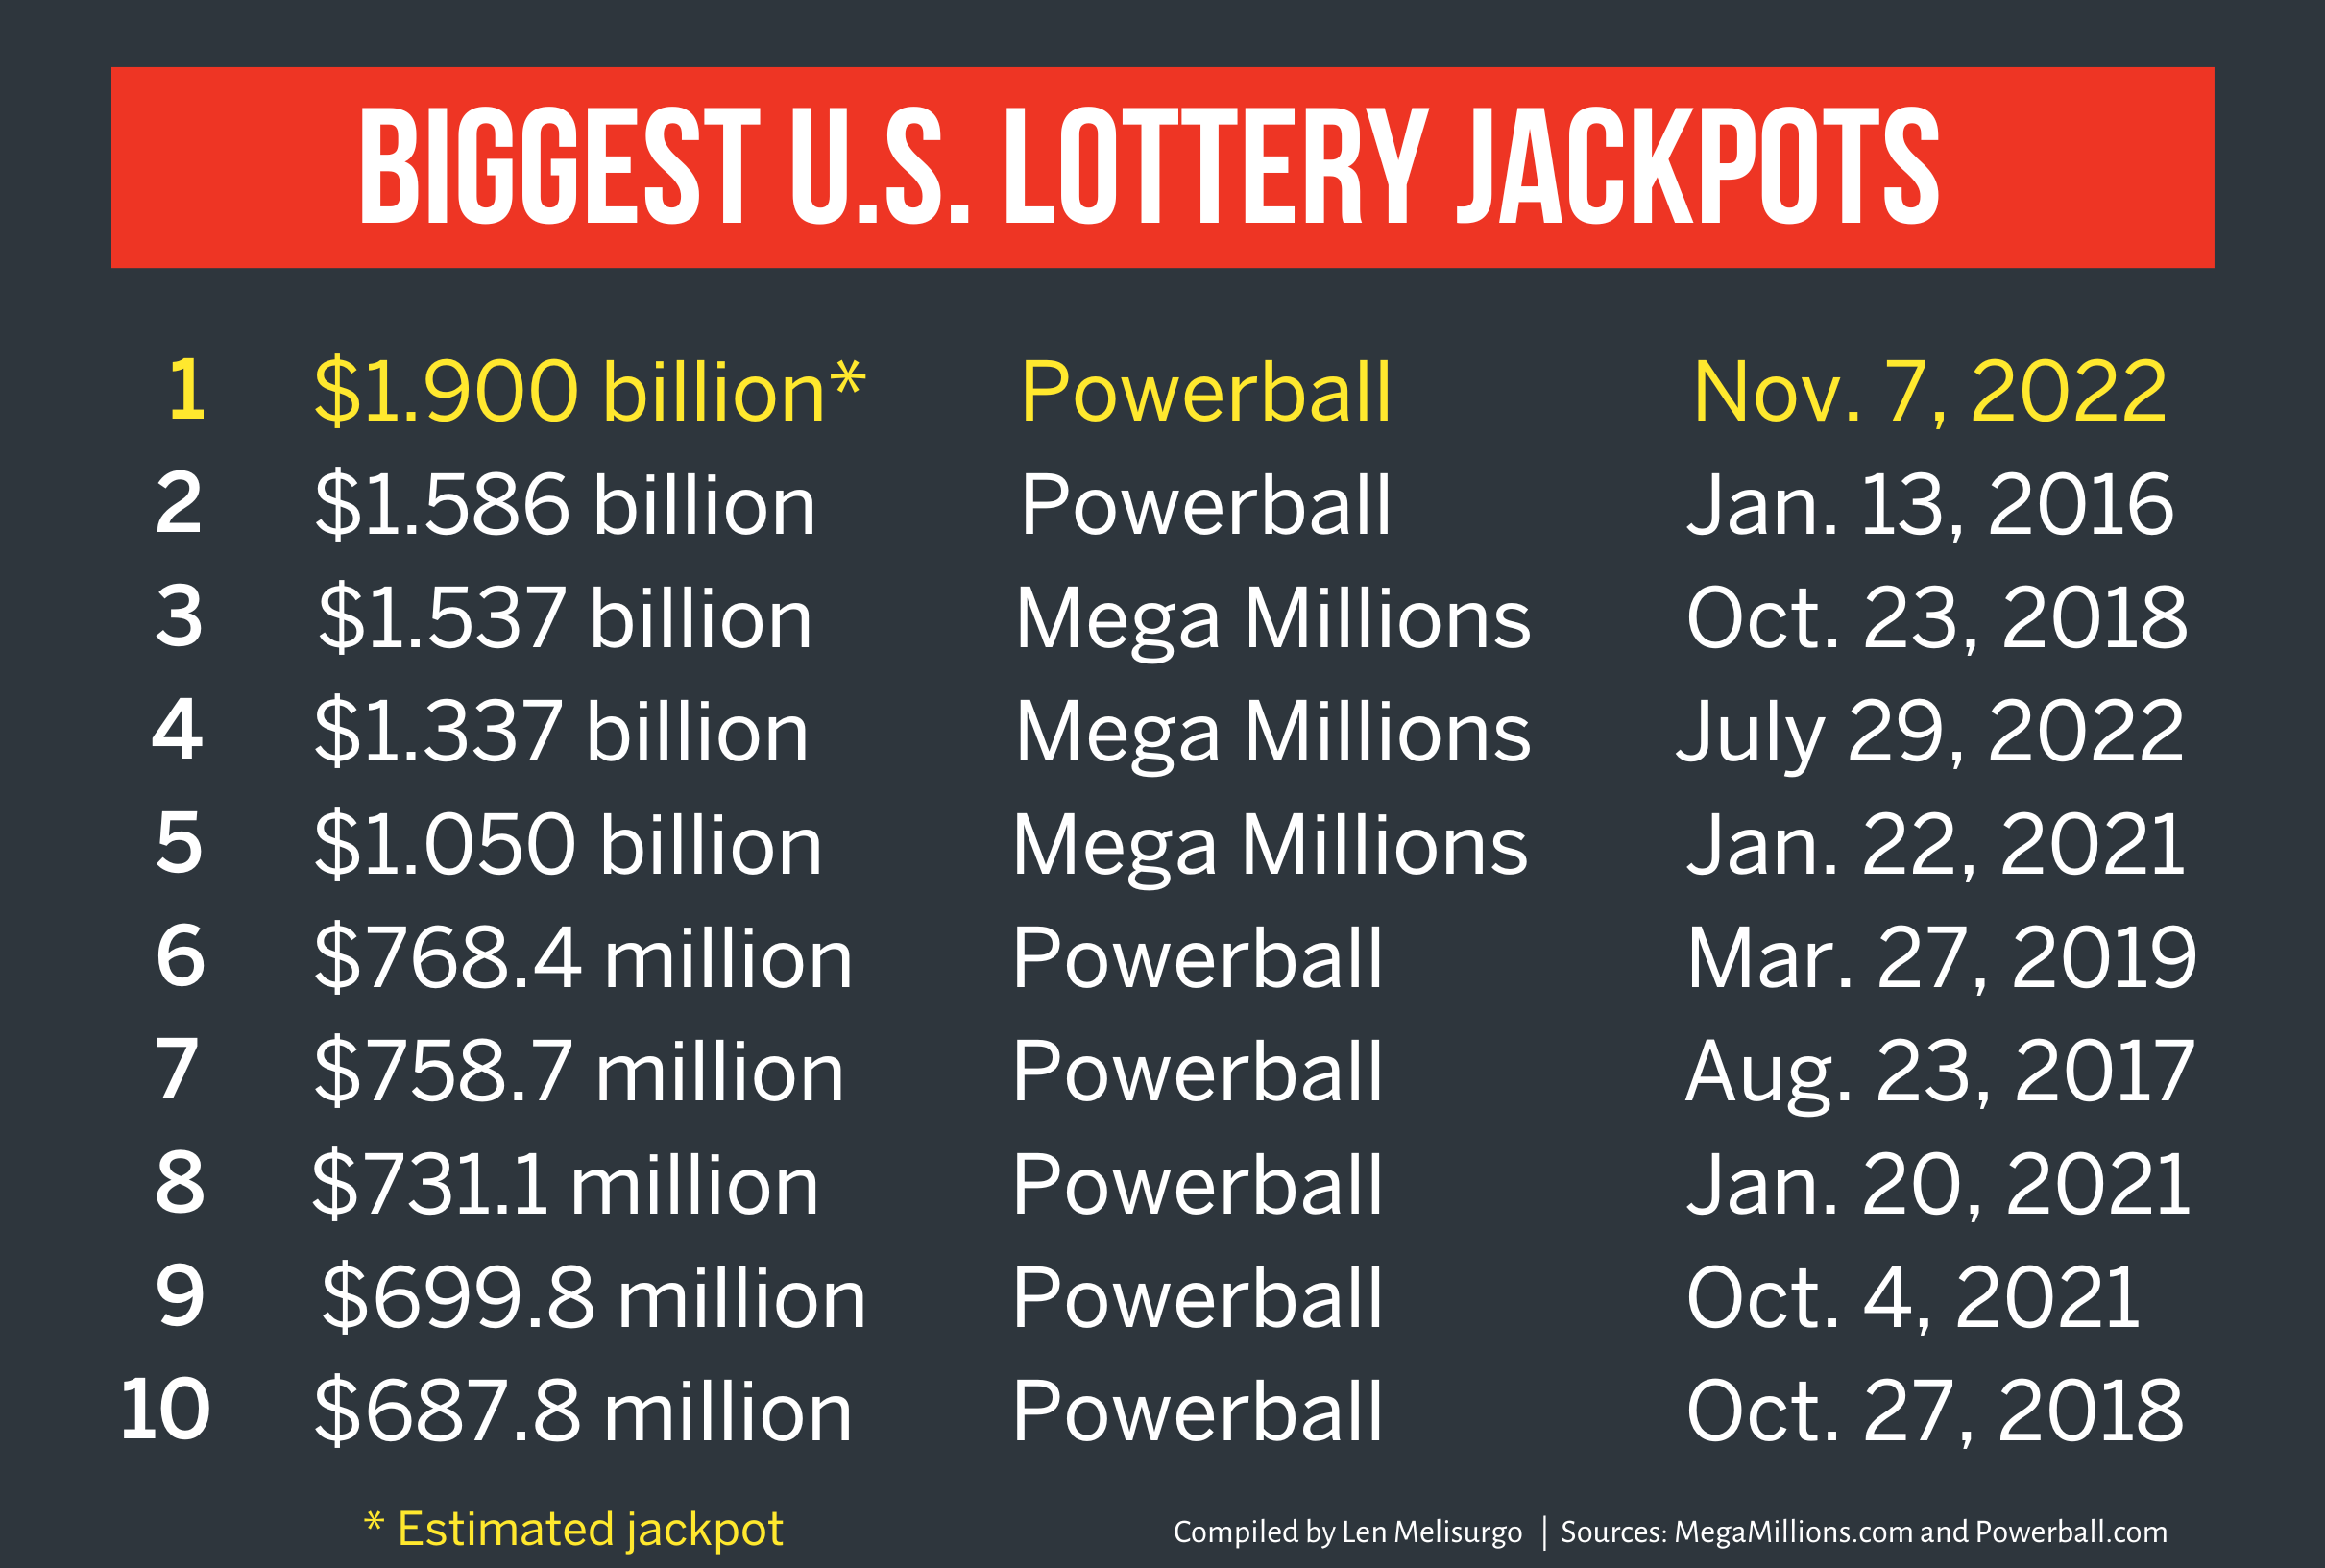
The search for “what was the winning powerball numbers tonight” often represents more than just a passing curiosity; for millions, it is the pursuit of a radical financial transformation. While the odds of hitting the jackpot are approximately 1 in 292.2 million, the financial implications of such a windfall require a level of sophistication and planning that most individuals have never had to exercise. Whether you are checking your ticket for a record-breaking billion-dollar prize or a smaller secondary tier win, the transition from a standard income earner to a high-net-worth individual is a complex journey fraught with legal, tax, and investment hurdles.
The Financial Reality of the Jackpot: Probability and Strategy
Before diving into the mechanics of wealth management, it is essential to understand the financial landscape of the Powerball. Many view the lottery as a “side hustle” or an informal investment strategy, but from a purely mathematical and personal finance perspective, it is a low-probability event that requires a high-impact contingency plan.
Understanding the Odds in a Financial Context
To put the odds into perspective, an individual is more likely to be struck by lightning or become a movie star than to match all six numbers. However, when those numbers do align, the influx of liquidity is so massive that it can disrupt even the most stable financial foundations. For most, the search for tonight’s winning numbers is the start of a “liquidity event”—a term used in finance to describe a significant transition of assets into cash. Unlike selling a business or exercising stock options, a lottery win is instantaneous, leaving the winner with very little time to adjust their financial mindset.
The Cost of Participation vs. Opportunity Cost
Financial advisors often discuss the “opportunity cost” of the lottery. If an individual spends $20 a week on Powerball tickets over 30 years, they will have spent over $30,000. If that same amount were invested in a low-cost S&P 500 index fund with an average 7% annual return, it would grow to nearly $100,000. While the dream of the jackpot is powerful, the disciplined investor understands that the true “winning numbers” are usually found in compound interest and consistent contributions to a diversified portfolio.
You Won—Now What? The Immediate Financial Roadmap
If you find that your ticket matches the numbers announced tonight, the first 48 hours are the most critical for your long-term financial survival. Sudden Wealth Syndrome is a documented psychological condition that leads many winners to bankruptcy within five to seven years. Avoiding this “lottery curse” requires immediate professional intervention.
The Anonymity and Security Protocol
The first step is not to tell the world. In many states, lottery winners can remain anonymous or claim their prize through a legal entity like a blind trust or an LLC. Protecting your identity is a crucial step in wealth preservation. Once your name is public, you become a target for predatory investment schemes, distant relatives seeking handouts, and frivolous lawsuits. Before claiming the prize, secure the physical ticket in a safe deposit box and consult with a legal professional to determine if your jurisdiction allows for anonymous filings.
Assembling Your “Dream Team” of Professionals
Managing tens or hundreds of millions of dollars is a full-time job that requires expertise in multiple disciplines. A winner should immediately interview and hire three key professionals:
- A Tax Attorney: To navigate the complex web of federal and state gift taxes, estate taxes, and income taxes.
- A Certified Public Accountant (CPA): To manage the immediate tax liability of the win and set up a system for ongoing reporting.
- A Fee-Only Financial Advisor: Unlike commission-based brokers, fee-only advisors have a fiduciary duty to act in your best interest. They will help you craft an Investment Policy Statement (IPS) to guide your long-term asset allocation.
Lump Sum vs. Annuity: The Great Financial Debate
Perhaps the most significant financial decision a winner must make is choosing between the one-time cash payment (lump sum) and the 30-year annuity. This is a classic “Time Value of Money” problem that requires a deep dive into inflation, tax rates, and expected market returns.

Analyzing the Present Value of Money
The Powerball jackpot is advertised as the total value of the annuity. The lump-sum option is the “present value” of that money—essentially the amount of cash the lottery has on hand to fund the prize today. Choosing the lump sum gives you immediate access to the capital, allowing for more aggressive investment and the potential for higher returns. However, it also places the entire burden of investment risk on your shoulders. If the market underperforms or you make poor choices, the money could vanish.
Tax Implications and Long-term Growth
The annuity option offers a unique form of “forced discipline.” Because the payments are spread over 30 years, it is virtually impossible to spend the entire fortune in a short period. Furthermore, the annuity payments increase by 5% each year to help combat inflation. From a tax perspective, the lump sum is taxed at the highest bracket in a single year, whereas the annuity allows you to spread the tax liability over three decades. This can be advantageous if you believe tax rates will remain stable or decrease in the future, though many wealthy individuals prefer the lump sum to lock in current tax rates and maintain control over their assets.
Protecting Your Wealth for the Long Term
Winning the lottery is the beginning of a wealth preservation phase, not just a spending phase. The goal shifts from “getting rich” to “staying rich.” This requires a sophisticated approach to asset allocation and risk management.
Diversification and Wealth Preservation
A multi-million dollar portfolio should be diversified across various asset classes to weather economic downturns. This includes:
- Equities: Domestic and international stocks for long-term growth.
- Fixed Income: Municipal bonds (often tax-exempt) and corporate bonds to provide steady income.
- Real Estate: Tangible assets that can provide both appreciation and rental income.
- Alternative Investments: Private equity or hedge funds, which are often available only to “accredited investors” with significant net worth.
The primary objective is to create a “safe withdrawal rate.” If a winner can live on 2% to 3% of their total portfolio value per year, the principal remains untouched, and the wealth can grow indefinitely.
Estate Planning and Generational Wealth
For many winners, the goal is to leave a legacy. This involves complex estate planning to ensure that wealth is passed down to heirs with minimal tax erosion. Tools such as Irrevocable Life Insurance Trusts (ILITs), Charitable Lead Trusts (CLTs), and Family Limited Partnerships (FLPs) are often used by high-net-worth individuals to shield assets from the 40% federal estate tax. By setting up these structures early, a winner can ensure that their “winning numbers” provide for their children and grandchildren for generations to come.
The Psychological Side of Money: Avoiding the “Lottery Curse”
While the math of the Powerball is straightforward, the psychology is not. Money is an emotional tool, and sudden wealth can distort one’s sense of reality and relationships.
Establishing Spending Boundaries
Financial advisors often recommend a “cooling-off period” of six months to a year before making any major life changes, such as quitting a job, buying a mansion, or gifting large sums to friends. During this time, the winner should live on a modest budget while their financial team structures their accounts. Creating a “No” policy is also vital. You will inevitably be approached with “guaranteed” business opportunities and personal pleas. Having a professional intermediary (like your attorney or advisor) handle these requests can preserve your personal relationships while protecting your capital.
Philanthropy and Impact Investing
Many winners find fulfillment by using their wealth for the greater good. Establishing a private foundation or a Donor-Advised Fund (DAF) allows for strategic charitable giving while providing significant tax deductions. Impact investing—putting money into companies that generate social or environmental benefits alongside financial returns—is another way to align your new wealth with your personal values. By focusing on “giving back,” winners can transition from being a consumer of wealth to a steward of capital, providing a sense of purpose that a bank balance alone cannot offer.
The search for the winning Powerball numbers tonight is the start of a potential financial revolution. However, the true “win” is not just matching the numbers, but in the disciplined, strategic management of the assets that follow. By prioritizing professional advice, tax efficiency, and long-term investment strategies, a winner can transform a moment of luck into a lifetime of financial freedom and security.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.