
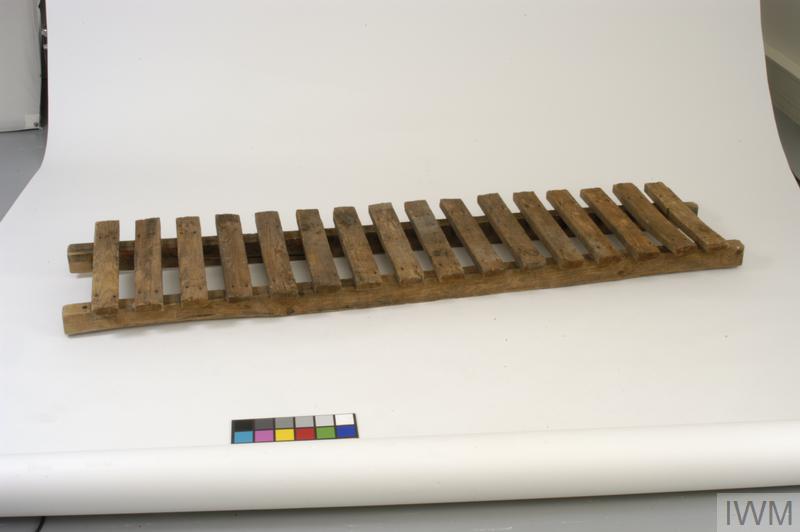
In the context of historical military engineering, duckboards were the essential slatted platforms placed at the bottom of trenches and across marshy terrain. Their purpose was singular: to provide a stable, elevated walkway that kept soldiers out of the mud and water, preventing the physical and systemic decay known as trench foot. In the modern world of personal finance, investing, and business management, the “duckboard” serves as a powerful metaphor for the foundational structures we build to navigate the volatile and often treacherous terrain of the global economy.
The purpose of duckboards in a financial sense is to create a buffer between your capital and the corrosive elements of market volatility, inflation, and unforeseen liability. Without these structural supports, even the most promising investment strategy can sink into the quagmire of insolvency. To achieve long-term wealth, one must understand how to construct these platforms, ensuring that every step taken toward a financial goal is supported by a rigid framework of risk management and liquidity.
The Financial Landscape: Navigating the Muddy Terrain of Economic Volatility
The global economy is rarely a paved road. More often, it resembles the uneven, shifting ground of a high-stakes environment where conditions can change overnight. For the individual investor or the small business owner, the “mud” represents the friction of the marketplace: high interest rates, sudden shifts in consumer demand, and the inevitable cycles of recession.
Identifying the “Trench Foot” of Personal Finance
In the absence of duckboards, soldiers suffered from debilitating conditions. In finance, the equivalent of this systemic decay is “lifestyle creep” combined with high-interest consumer debt. When an individual’s financial life is lived directly in the mud—meaning they have no buffer between their income and their expenses—any economic downturn leads to immediate distress. The purpose of building a financial duckboard is to elevate your lifestyle above your baseline costs, ensuring that even if the “water level” of expenses rises, your core assets remain dry and functional.
The Role of Structural Support in Wealth Accumulation
Wealth is not merely the accumulation of currency; it is the construction of a resilient system. Many beginners make the mistake of stepping directly into “deep water” investments—such as high-leverage options or speculative crypto assets—without first laying the wooden slats of a foundational portfolio. A professional financial strategy recognizes that the purpose of duckboards is to provide a reliable path to the front lines of wealth creation. Before you can engage in aggressive growth, you must ensure that your path back to stability is reinforced.
Liquidity as a Protective Layer: Building Your Primary Walkway
In financial terms, the most immediate “duckboard” is liquidity. Liquidity provides the mobility required to pivot when a specific investment or business venture goes south. Just as duckboards allowed for the rapid movement of troops regardless of the ground conditions, a liquid cash reserve allows an investor to move capital where it is most effective without being forced to sell assets at a loss during a market dip.
The Emergency Fund as an Elevated Walkway
The emergency fund is the quintessential duckboard of personal finance. Most experts recommend a buffer of three to six months of expenses. The purpose here is not growth, but protection. This capital sits in high-yield savings accounts or money market funds—safe, accessible, and elevated above the volatile fluctuations of the stock market. When the “rain” of a medical emergency or job loss hits, the individual with these duckboards in place continues to walk on solid ground, while those without them sink into high-interest debt.
Diversification: Distributing Weight Across Multiple Slat Systems
A single plank of wood will eventually break under concentrated pressure. Duckboards were designed as a series of interconnected slats that distributed the weight of the traveler across a wider surface area. In the niche of investing, this is the principle of diversification. By spreading capital across various asset classes—equities, fixed income, real estate, and commodities—you ensure that the failure of one “plank” does not cause the entire walkway to collapse. The purpose of this structural diversification is to mitigate idiosyncratic risk, ensuring that the investor remains mobile even when specific sectors of the economy are underwater.
Institutional Resilience: Applying Duckboard Principles to Business Finance
For corporations and entrepreneurs, the purpose of duckboards shifts toward operational continuity and cash flow management. A business that operates without a “duckboard” strategy is one that is constantly at the mercy of its most recent invoice. To build a brand or a company that lasts, one must engineer a financial infrastructure that can withstand seasonal droughts and sudden floods of demand.
Working Capital Management
Working capital is the duckboard of the corporate world. It is the difference between current assets and current liabilities. A company with healthy working capital can pay its suppliers, meet its payroll, and invest in R&D even when sales are sluggish. The purpose of maintaining a high current ratio is to provide a safety margin that prevents the business from sinking into the mud of technical insolvency. Effective managers treat their balance sheets like a well-engineered trench system, ensuring that there is always a dry path to the next quarter’s objectives.
Debt as a Stabilizer vs. a Weight
There is a common misconception that all debt is a burden. However, in sophisticated business finance, strategic debt can act as a stabilizer—provided it is used to build the walkway. Low-interest, long-term debt used to acquire appreciating assets or to scale operations acts as the “framework” for the duckboards. The danger arises when the debt becomes the mud itself. When the cost of servicing debt exceeds the utility of the walkway it was meant to support, the structure breaks. The purpose of a sound financial strategy is to balance leverage so that it supports the weight of growth without snapping under the pressure of interest rate hikes.
Maintenance and Durability: Protecting Your Financial Infrastructure from Erosion
Duckboards were not “set and forget” tools; they required constant maintenance to prevent rot. Similarly, financial systems are subject to the erosive forces of time and the economy. To maintain the purpose of your financial duckboards—stability and progress—you must engage in active “maintenance” through tax planning and inflation protection.
Inflation and the Degradation of Idle Assets
If a duckboard is left in standing water for too long, the wood begins to rot. In the world of money, inflation is the standing water. Cash that sits idle for years loses its purchasing power, effectively rotting the very floor you are standing on. To combat this, the “wood” of your financial walkway must be “treated” with inflation-beating assets. This includes Treasury Inflation-Protected Securities (TIPS), real estate, or high-quality equities that have the pricing power to pass costs on to consumers. The purpose of these choices is to ensure that the walkway stays firm over decades, not just months.
Tax-Efficiency as a Sealant
Taxes are the friction that can slow down wealth accumulation. Utilizing tax-advantaged accounts like 401(k)s, IRAs, or HSAs acts as a sealant for your financial duckboards. These structures protect your gains from being eroded by the “weather” of the fiscal environment. By minimizing tax drag, you increase the structural integrity of your path to retirement. A professional investor knows that it is not what you earn, but what you keep, that determines the height of your walkway above the economic mire.
The Psychological Purpose of the Financial Duckboard
Beyond the numbers and the balance sheets, the purpose of duckboards is to provide psychological security. In the chaos of a volatile market, the investor who knows they have a stable, dry path to walk on is the one who remains calm. Panic is the primary cause of financial ruin; it leads to selling at the bottom and buying at the peak.
When you have built your “duckboards”—your emergency fund, your diversified portfolio, and your tax-efficient structures—you gain the clarity of mind to stay the course. You realize that while the ground around you may be muddy and the environment may be harsh, your footing is secure. You are not fighting the terrain; you are rising above it. This perspective is what separates the amateur from the professional. The purpose of these systems is to remove the element of fear from the equation, allowing for cold, calculated decision-making that leads to generational wealth.
In conclusion, whether we are discussing the trenches of history or the digital ledgers of modern finance, the purpose of duckboards remains the same: to provide a stable, reliable foundation in an unstable world. By prioritizing liquidity, diversification, and structural maintenance, you ensure that your financial journey is defined not by the mud you struggle through, but by the solid ground you have had the foresight to build.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.