
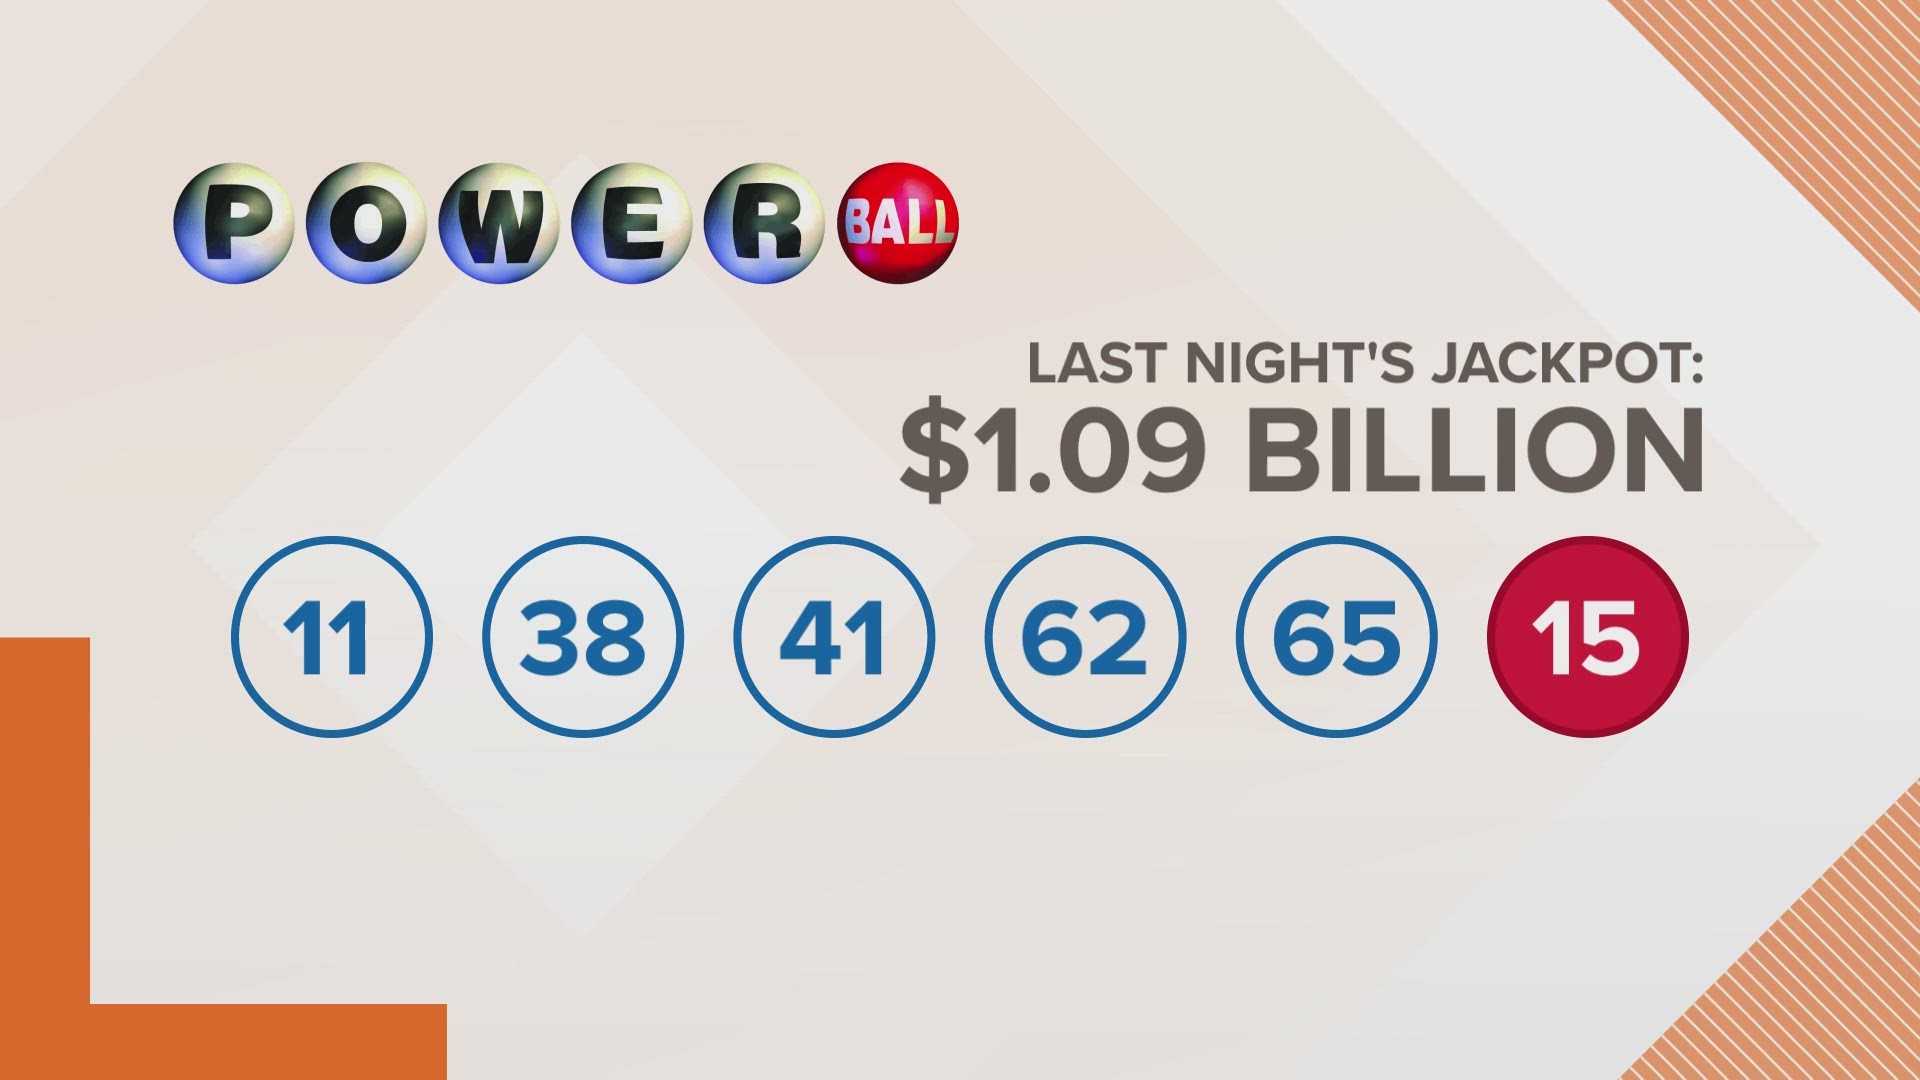
The search for “what was the powerball winning numbers last night” is often driven by a cocktail of hope, adrenaline, and the universal human desire for financial liberation. For millions, the Powerball represents more than just a game of chance; it is a cultural phenomenon that promises a shortcut to the upper echelons of the global elite. However, once the numbers are drawn and the initial excitement subsides, a much more complex financial reality begins to emerge. Whether you are holding a winning ticket or simply evaluating your personal finance strategy, understanding the mechanics of high-stakes windfalls is essential for long-term fiscal health.
The Mathematical Reality of the Jackpot
Before diving into the management of millions, one must first reconcile with the sheer statistical improbability of the win. The odds of matching all five white balls and the red Powerball are approximately 1 in 292.2 million. To put this in perspective, you are statistically more likely to be struck by lightning, become a professional athlete, or even be crushed by a vending machine than you are to hold the winning ticket.
The Cost of the Dream
From a personal finance perspective, the Powerball is often referred to as a “tax on those who are bad at math.” While a $2 ticket seems negligible, the cumulative cost for regular players can be significant. If an individual spends $10 a week on lottery tickets over a 40-year working life, they will have spent over $20,000. If that same $40 per month had been invested in a low-cost S&P 500 index fund with an average 7% annual return, it would have grown to nearly $100,000. This “opportunity cost” is the hidden price of the search for those winning numbers.
Tax Withholding and the Net Payout
When the winning numbers align with your ticket, the first entity to take notice is the Internal Revenue Service (IRS). It is a common misconception that the “advertised” jackpot is the amount the winner takes home. Before the money even reaches your bank account, the federal government mandates a 24% withholding tax on gambling winnings.
However, since the top federal income tax bracket is currently 37%, the winner will likely owe an additional 13% when they file their annual tax return. Furthermore, state taxes vary wildly. If you live in a state like California or Florida, you may face zero state tax on your winnings. Conversely, winners in New York or Maryland could see another 8% to 10% of their prize evaporated by state and local levies.
Lump Sum vs. Annuity: The Critical Financial Choice
The moment a winning ticket is confirmed, the winner faces the most significant financial decision of their life: choosing between the lump sum (cash option) or the annuity. This decision is not merely about preference; it is a complex calculation involving the time value of money, inflation, and investment risk.
The Case for the Lump Sum
The cash option provides the winner with the “present value” of the jackpot immediately. Most winners choose this route because it offers total control. From a wealth management perspective, the lump sum is advantageous if the winner believes they (or their advisors) can generate a return on investment that exceeds the internal rate of return offered by the lottery’s annuity.
By taking the cash now, a winner can diversify their assets across real estate, private equity, and diversified stock portfolios. This provides a hedge against the possibility of future tax hikes, as the money is taxed at current rates rather than whatever rates might exist 20 or 30 years down the line.
The Case for the Annuity
The Powerball annuity is paid out over 30 years, with each annual payment increasing by 5%. This structure is designed to protect winners from themselves. “Sudden Wealth Syndrome” is a documented psychological phenomenon where individuals who acquire large sums of money rapidly lose it all through impulsive spending and poor investments.
The annuity acts as a financial safety net, ensuring that even if the winner makes catastrophic financial mistakes in year one, they will have a fresh infusion of capital in year two. For those who lack disciplined financial habits, the annuity is often the safer, more sustainable path to multi-generational wealth.

Building a Strategic Wealth Management Team
If you find that your numbers matched those drawn last night, your first move should not be to the lottery headquarters, but to a lawyer’s office. Managing a windfall of this magnitude requires a sophisticated team of professionals to navigate the legal and financial minefields that accompany extreme wealth.
The Role of the Tax Attorney
A tax attorney is the first line of defense. They assist in structuring the claim to minimize tax liability and, in states where it is permitted, can help the winner remain anonymous. Many winners choose to claim the prize through a blind trust or a Limited Liability Company (LLC). This prevents the winner’s name from being released to the public, protecting them from the inevitable “long-lost relatives” and predatory “investment opportunities” that follow a public announcement.
The Fee-Only Financial Advisor
The second essential team member is a fee-only fiduciary financial advisor. Unlike advisors who work on commission (and thus have an incentive to sell specific products), a fee-only advisor is paid a flat rate or a percentage of assets under management. Their role is to create a comprehensive wealth strategy that covers:
- Asset Allocation: Balancing the portfolio between low-risk bonds and high-growth equities.
- Estate Planning: Setting up trusts for children and heirs to ensure the wealth lasts for generations.
- Charitable Giving: Establishing a private foundation or a donor-advised fund to manage philanthropic goals while gaining tax benefits.
The Certified Public Accountant (CPA)
A CPA specializing in high-net-worth individuals will handle the ongoing tax compliance. The tax situation for a Powerball winner is infinitely more complex than that of a standard W-2 employee. From quarterly estimated tax payments to complex gift tax filings, a CPA ensures the winner remains in good standing with the IRS.
The Psychological Impact of Sudden Wealth
While the financial aspects of winning the lottery are quantifiable, the psychological impacts are often underestimated. Research shows that lottery winners are not significantly happier than the general population a few years after their win. This is due to “hedonic adaptation,” where the human brain quickly adjusts to new levels of luxury, requiring even greater stimuli to achieve the same level of satisfaction.
Sudden Wealth Syndrome
Many winners experience a period of intense isolation. Relationships can be strained when friends or family members feel entitled to a portion of the winnings. The pressure to “fix” everyone’s problems can lead to resentment and emotional burnout. Financial experts often recommend a “cooling-off period” of six months to a year, during which the winner makes no major lifestyle changes—no new houses, no luxury cars, and no massive gifts—until they have adjusted to their new reality.
Redefining Purpose
The greatest challenge of winning the Powerball is not managing the money, but managing the time. When the necessity of work is removed, many individuals lose their sense of purpose. Successful winners often find fulfillment by treating their wealth as a business to be managed or by dedicating their lives to a cause they are passionate about. Without a structured daily purpose, the “dream” of winning can quickly turn into a nightmare of boredom and excess.
Beyond the Lottery: Sustainable Wealth Creation
Regardless of whether you held the winning numbers last night, the lessons of the Powerball apply to all aspects of personal finance. The lottery is a reminder that true, sustainable wealth is rarely the result of a single event; it is the result of systems, discipline, and the understanding of compound interest.
Consistent Investing vs. Speculation
The most reliable way to build a “jackpot” is through the consistent application of sound financial principles. For the average person, the “winning numbers” are not found on a lottery ticket, but in a 401(k) or an IRA. By automating savings and investing in diversified assets, individuals can build a level of security that provides many of the same benefits as a lottery win—freedom of time, security for family, and the ability to contribute to the community—without the astronomical odds.
The Power of Financial Literacy
Ultimately, the search for “what was the powerball winning numbers last night” reflects a desire for a different life. While only one person may win the jackpot, everyone has the ability to improve their financial standing through literacy. Understanding how taxes work, how inflation impacts purchasing power, and how to protect assets from legal liability are skills that are valuable at any income level.
The Powerball is a game of chance, but wealth management is a game of strategy. By focusing on the latter, you ensure that your financial future is determined by your decisions rather than the bounce of a plastic ball. Whether you are managing $1,000 or $1 billion, the principles of professional finance remain the same: protect your principal, minimize your taxes, and plan for the long term.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.