
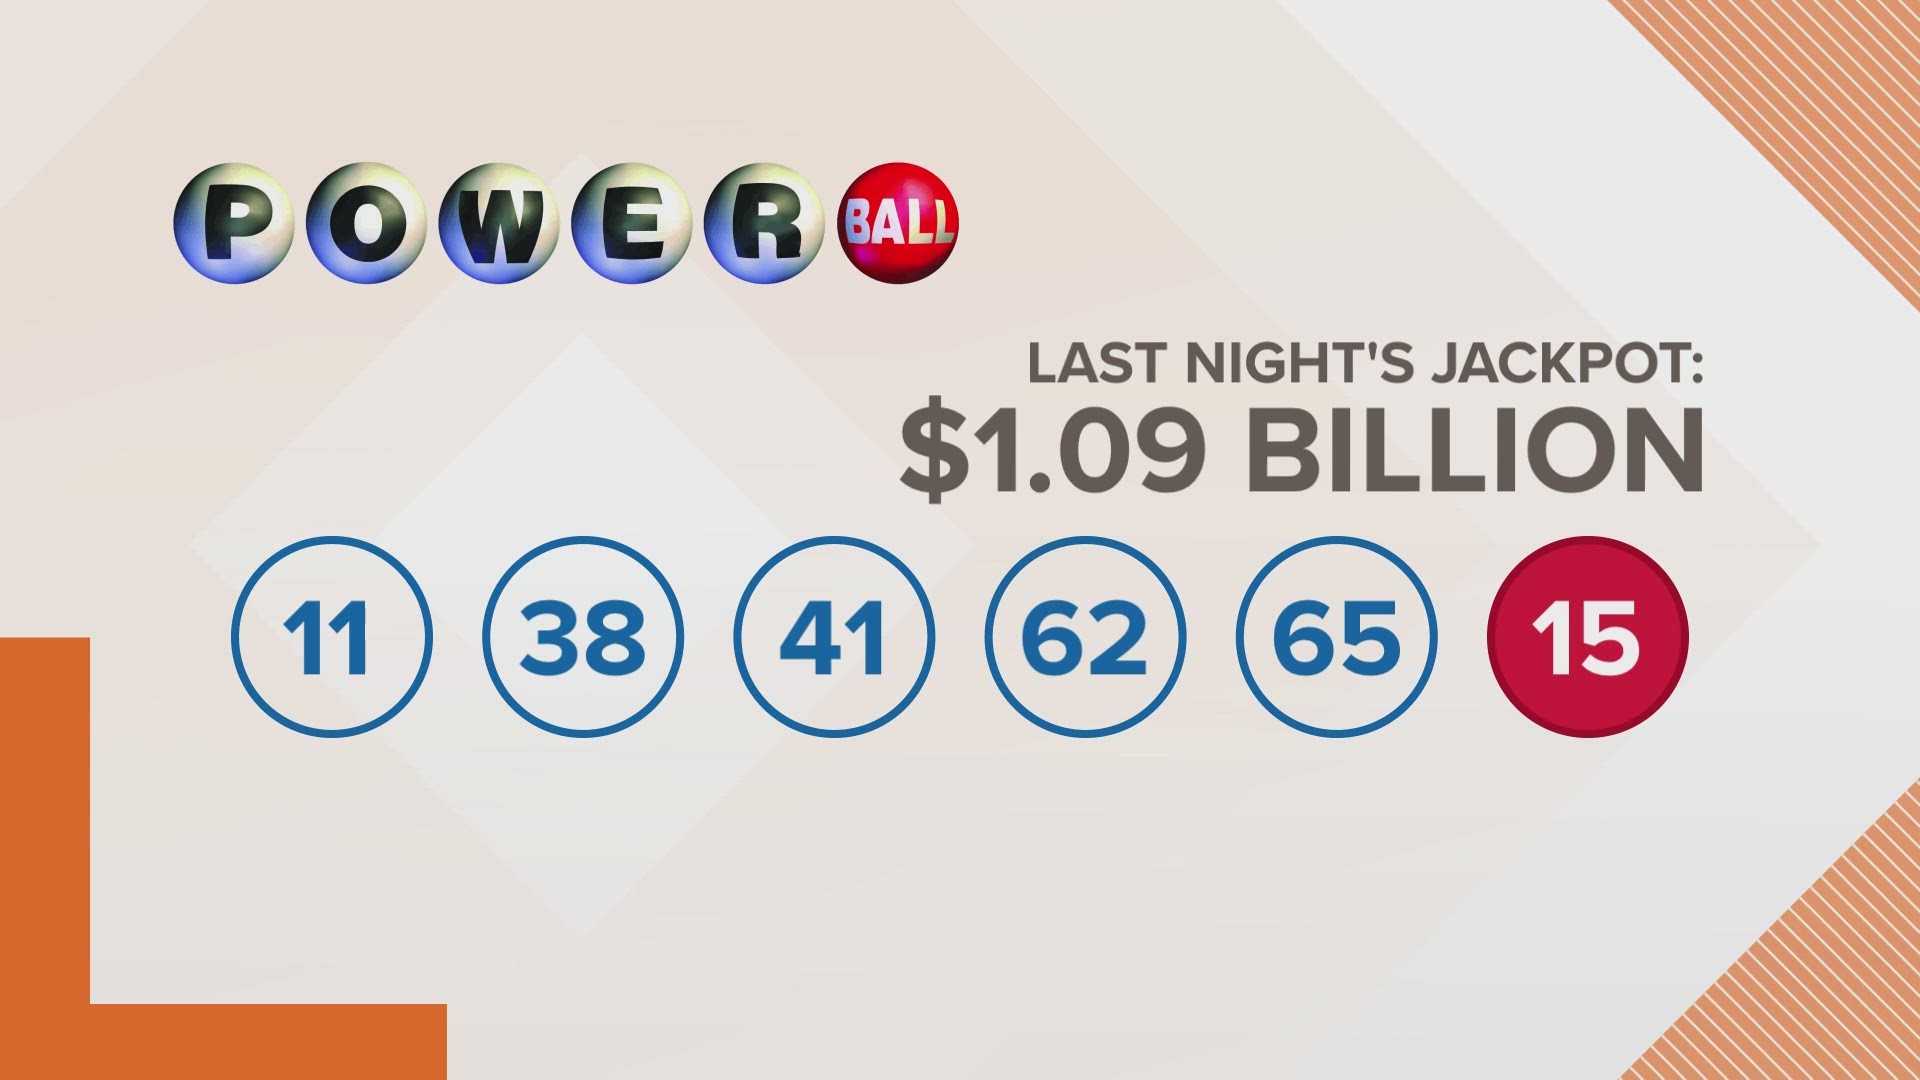
The moment of checking the winning numbers for a major lottery draw like the Powerball is often characterized by a unique blend of adrenaline and escapism. For millions of participants, the search for “what was the powerball numbers for yesterday” represents more than just a curiosity; it is a brief engagement with the “What If” of extreme wealth. However, from a professional financial perspective, the transition from a ticket holder to a jackpot winner is one of the most complex fiscal events an individual can experience.

True financial literacy involves understanding that a massive windfall is not merely a spending opportunity, but a sophisticated management challenge. Whether you are checking the results for a standard drawing or a record-breaking billion-dollar jackpot, the financial implications of those six numbers are profound. This guide explores the strategic, legal, and economic frameworks required to navigate the reality of sudden, life-changing wealth.
Understanding the Financial Mechanics of the Lottery
Before diving into the management of a win, it is essential to understand the lottery through the lens of behavioral finance and probability. The Powerball is governed by strict mathematical odds—1 in 292.2 million for the jackpot—which makes it a statistically poor investment but a culturally significant phenomenon.
The Concept of Expected Value
In the world of professional finance, we often discuss “Expected Value” (EV). To calculate the EV of a Powerball ticket, one must multiply the probability of winning each prize tier by the amount of that prize. Typically, the EV of a $2 ticket is significantly less than $2, making it a “negative-sum game.” However, when jackpots climb into the hundreds of millions or billions, the mathematical EV can technically turn positive. Despite this, the “risk of ruin” remains near 100% because the probability of winning is so infinitesimally small. For the savvy individual, the lottery is treated as a low-cost form of entertainment, never as a core component of a retirement or investment strategy.
Behavioral Finance and the “Hope Premium”
Why do people continue to check yesterday’s numbers with such fervor? Behavioral economists point to the “hope premium.” The small cost of a ticket buys the purchaser the right to dream about financial freedom. While this is psychologically rewarding, it becomes a financial hazard when it replaces consistent, disciplined investing. The search for winning numbers should always be balanced by a robust understanding of traditional wealth-building vehicles like diversified index funds, real estate, and tax-advantaged accounts.
The Immediate Financial Protocol for Potential Winners
If you find that your ticket matches the numbers drawn yesterday, your first instinct may be to celebrate. However, from a wealth management standpoint, the first 48 hours are the most critical for protecting your long-term interests.
Securing the Asset and Anonymity
A winning Powerball ticket is a “bearer instrument,” meaning that whoever holds it and signs it is the legal owner. The first step is to sign the back of the ticket (unless you are in a state that allows for anonymous trusts) and place it in a secure location, such as a high-security safe or a bank safety deposit box.
Anonymity is your greatest financial asset. In the modern digital age, “lottery lawyers” recommend maintaining a “dark” profile. Sudden wealth attracts not only legitimate financial opportunities but also predatory actors and aggressive requests from acquaintances. Depending on your state’s laws, you may be able to claim the prize through a legal entity, such as a Limited Liability Company (LLC) or a Blind Trust, to keep your name out of the public record.
Assembling a “Wealth Council”
Managing a jackpot is not a DIY project. A winner requires a specialized team that typically includes:
- A Tax Attorney: To navigate the immediate federal and state tax liabilities.
- A Certified Public Accountant (CPA): To manage ongoing filings and complex tax structures.
- A Fee-Only Financial Advisor: To create an investment policy statement (IPS) and manage the portfolio without commission-based conflicts of interest.
- An Estate Planning Attorney: To ensure that the wealth is protected for future generations and that your legacy is secure.
Evaluating the Payout Structure: Lump Sum versus Annuity

One of the most significant financial decisions a winner faces after checking the numbers is choosing between the lump sum (cash option) and the annuity. This decision is a classic exercise in the “Time Value of Money.”
The Time Value of Money and Inflation
The Powerball jackpot is advertised as an annuity—30 payments over 29 years that increase by 5% each year. The cash option is the actual amount of money currently in the prize pool.
From an investment perspective, the lump sum is often preferred by those who believe they can generate a higher rate of return through private investments than the internal rate of return (IRR) offered by the lottery commission. However, the lump sum requires extreme discipline. Taking the annuity can act as a “financial safety net,” preventing a winner from losing the entire fortune in a few years through poor choices or bad market timing.
The Tax Burden: Federal and State Implications
Lottery winnings are treated as ordinary income by the IRS. Currently, the top federal tax bracket is 37%. When you claim a large prize, the lottery commission typically withholds 24% automatically, but you will owe the remaining 13% at tax time. Furthermore, state taxes vary wildly. In states like Florida or Texas, there is no state income tax on winnings. In states like New York or New Jersey, the state and local tax bite can take an additional 8% to 12%. Calculating the “net-net” (the amount left after all taxes) is the first step in realistic budgeting.
Long-Term Asset Allocation and Risk Management
Once the taxes are paid and the dust has settled, the goal shifts from “getting rich” to “staying rich.” This is where the principles of institutional-grade investing come into play.
Diversification Beyond the Jackpot
A sudden windfall creates a massive concentration of wealth in cash. The objective is to diversify this into a resilient portfolio.
- Equities: A broad mix of domestic and international stocks to capture global growth.
- Fixed Income: High-quality municipal bonds or Treasuries to provide tax-efficient income and preserve capital.
- Alternative Investments: Real estate, private equity, or venture capital can offer higher returns and lower correlation to the stock market, though they come with higher risk and lower liquidity.
Establishing Trusts and Estate Plans
Wealth of this magnitude requires sophisticated estate planning. Utilizing Revocable and Irrevocable Trusts can help minimize future estate taxes and ensure that the money is distributed according to your wishes. For those interested in philanthropy, establishing a Private Foundation or a Donor-Advised Fund (DAF) can provide significant tax deductions while allowing you to support causes you care about systematically.
The Behavioral Economics of a Windfall: Avoiding Lifestyle Creep
The history of lottery winners is littered with stories of “the lottery curse,” where winners end up bankrupt within a decade. This is rarely due to a lack of money, but rather a lack of financial psychology and discipline.
The Psychology of Risk and Spending
“Lifestyle creep” is the tendency for spending to increase as income increases. With a Powerball win, this creep can become an avalanche. Financial advisors often recommend a “waiting period” of six months to a year before making any major purchases—no mansions, no private jets, and no massive gifts. This allows the emotional volatility of the win to subside and enables the winner to adjust to their new economic reality.
Defining a Sustainable Spending Rate
A crucial metric in personal finance is the Safe Withdrawal Rate (SWR). If you win $100 million after taxes and invest it conservatively, a 3% to 4% withdrawal rate would give you an annual “salary” of $3 million to $4 million without ever touching the principal. By treating the windfall as an endowment rather than a checking account, you ensure that the wealth lasts for your lifetime and beyond.
Conclusion
The search for yesterday’s Powerball numbers is often a moment of fantasy, but the financial reality of winning is a serious business. Success in managing sudden wealth is not about how much you win, but how much you keep and how you grow it. By applying rigorous financial strategies—from tax optimization and legal protection to disciplined asset allocation—a winner can transform a stroke of luck into a lasting financial legacy. For the rest of us, the Powerball serves as a reminder of the importance of sound financial planning and the power of compounding interest, which, while slower than a lottery draw, is far more certain to build wealth over time.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.