
A baptism marks a significant milestone, representing a new beginning and a commitment to a child’s future. While traditional gifts often lean toward ornamental silver, delicate clothing, or keepsakes, the modern financial landscape offers a more impactful alternative. In an era of rising education costs and economic volatility, the most profound gift one can offer is the gift of financial security. By shifting the focus from ephemeral material items to long-term wealth-building vehicles, a benefactor provides a child with a head start that compounds over decades.
Choosing a financial gift requires a strategic approach. It involves understanding tax-advantaged accounts, the power of compound interest, and the various asset classes that can survive the test of time. This guide explores how to navigate the “Money” niche of baptismal gifting, ensuring your contribution serves as a cornerstone for the recipient’s eventual financial independence.
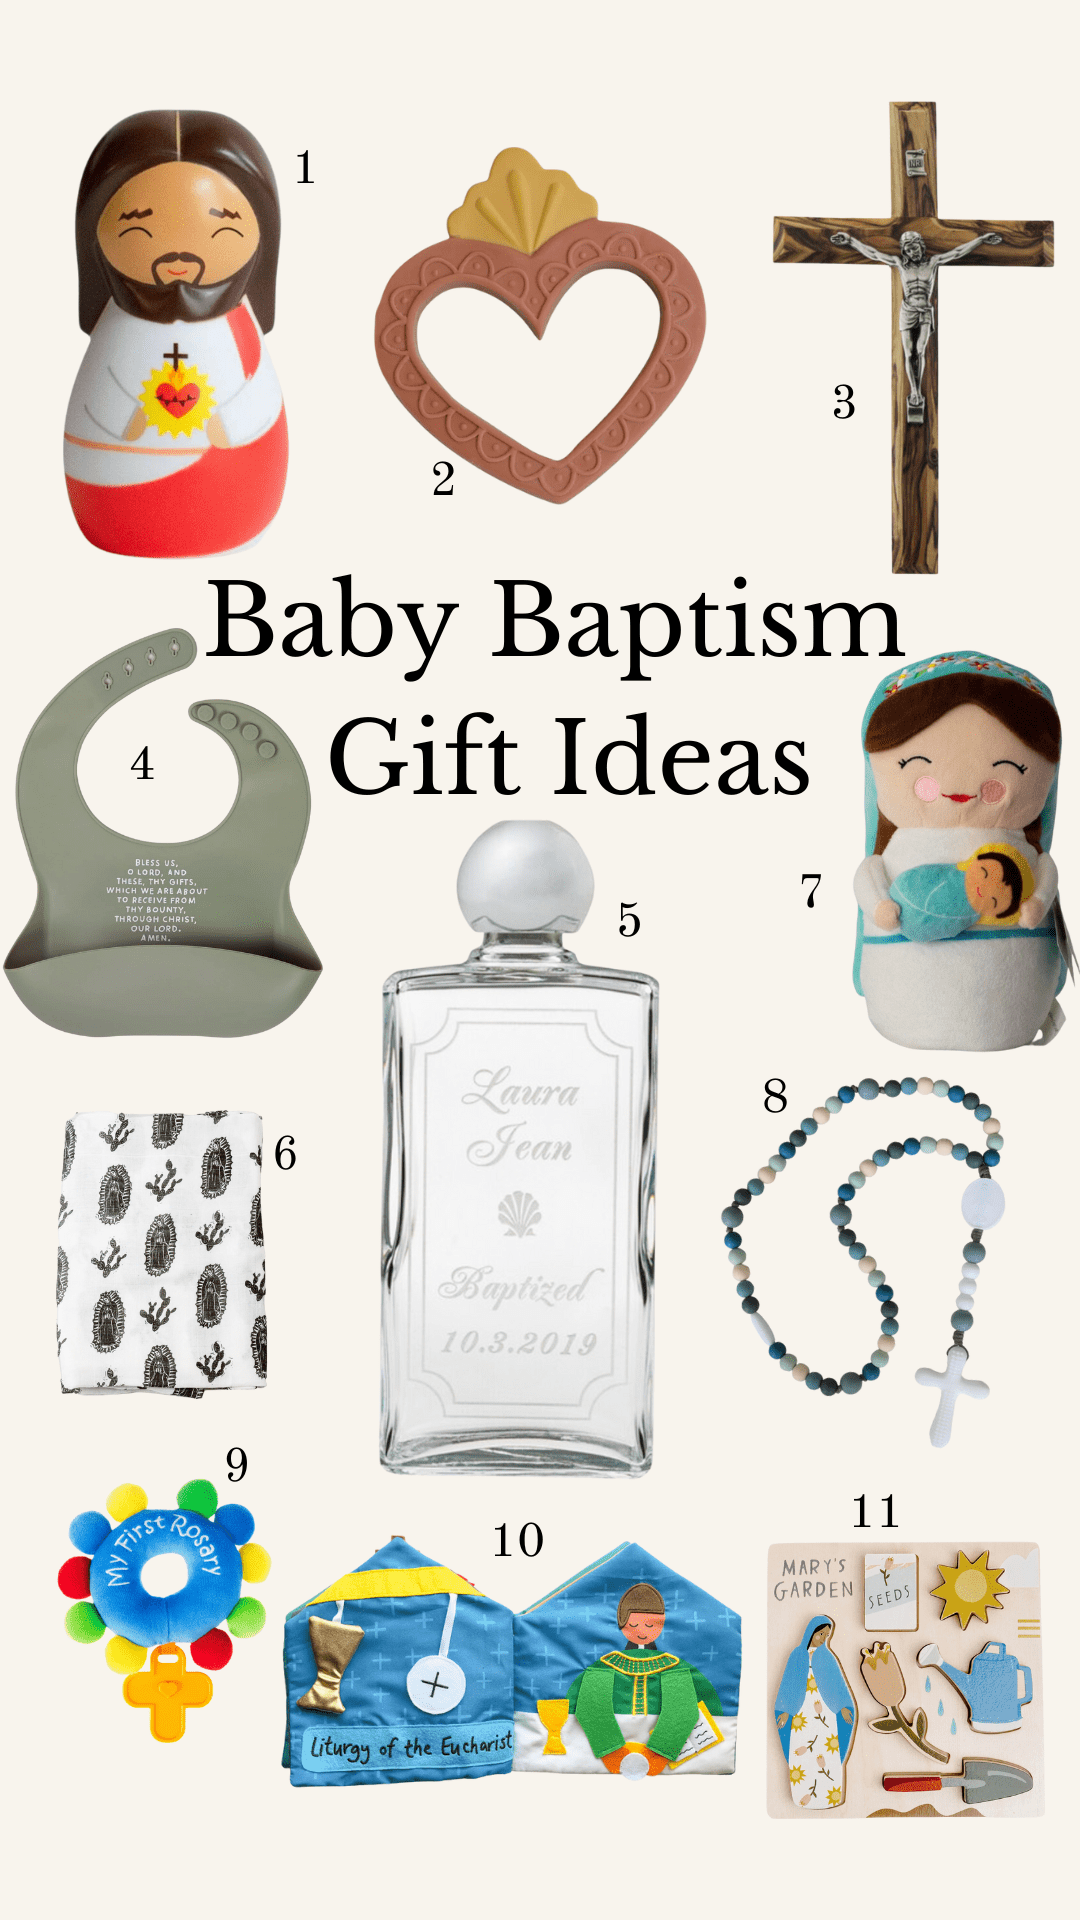
The Power of the Time Horizon: Why Financial Gifts Triumph
The most valuable asset a newborn possesses is not capital, but time. In the world of investing, the time horizon is the ultimate multiplier. A gift given at a baptism has approximately 18 years to grow before it is needed for higher education and nearly 60 years to mature before it reaches a typical retirement age. When we look at baptismal gifts through a financial lens, we are essentially arbitrageurs of time.
Understanding Compound Interest in Early Life
If a donor contributes $2,000 to a diversified equity fund at a child’s baptism and that fund achieves an average annual return of 7%, that initial gift will grow to nearly $7,000 by the time the child turns 18. If left untouched until the child reaches 65, that same $2,000—without any further contributions—balloons to over $115,000. This is the mathematical reality of compound interest. By choosing a financial gift, you are providing a benefit that no physical toy or garment can replicate: the exponential growth of purchasing power.
Shifting from Consumerism to Capital
Traditional gifts are often “depreciating assets.” A silver rattle or a designer outfit loses value the moment it is used or outgrown. In contrast, financial gifts are “appreciating assets.” They represent a shift in philosophy from immediate consumption to delayed gratification and long-term stability. For the donor, this means your capital is being put to work in a way that provides a measurable, lasting impact on the child’s quality of life.
Tax-Advantaged Education Savings: The 529 Plan
One of the most effective ways to gift money for a baptism is through a 529 College Savings Plan. Education remains one of the largest financial hurdles a young adult will face. By contributing to a 529 plan, you are directly mitigating future debt while taking advantage of current tax laws.
The Structural Benefits of the 529
A 529 plan is a state-sponsored investment account that allows for the tax-free growth of contributions. While the contributions themselves are made with after-tax dollars (meaning they are not federally tax-deductible), the earnings on those investments are not subject to federal tax when withdrawn for qualified education expenses. This includes tuition, room and board, books, and even certain K-12 expenses.
Many states also offer state income tax deductions or credits for contributions, making it a dual-benefit gift: it helps the child’s future while providing the donor with immediate tax relief. Furthermore, recent changes in legislation (such as the SECURE 2.0 Act) allow for a portion of unused 529 funds to be rolled over into a Roth IRA for the beneficiary, addressing the common concern of “over-funding” the account if the child does not attend college or receives a full scholarship.
Flexibility and Control
Unlike some other financial gifts, the 529 plan allows the donor (or the parent, depending on who opens the account) to maintain control over the assets. If the child decides not to pursue education, the beneficiary can be changed to another family member. This flexibility makes it a low-risk, high-reward financial strategy for a baptismal gift.
Custodial Accounts: Building an Unrestricted Portfolio
For those who wish to provide a gift that can be used for more than just education—perhaps a first home down payment or the seed capital for a business—custodial accounts are an excellent vehicle. Under the Uniform Gifts to Minors Act (UGMA) or the Uniform Transfers to Minors Act (UTMA), adults can set up accounts for the benefit of a minor.
UGMA vs. UTMA
The primary difference between these two lies in the types of assets they can hold. UGMA accounts are generally limited to bank deposits, stocks, bonds, and mutual funds. UTMA accounts can hold a wider variety of property, including real estate, fine art, or patents. For most baptismal gifts, a UGMA account focused on a low-cost S&P 500 index fund is the gold standard for long-term growth.
The Transfer of Ownership
It is important for donors to understand that gifts to a custodial account are irrevocable. Once the money is deposited, it belongs to the child. The adult acts as the custodian, managing the investments until the child reaches the “age of majority” (typically 18 or 21, depending on the state). At that point, the child gains full control of the funds. This makes the custodial account a powerful tool for teaching financial literacy as the child grows, as they can watch their baptismal gift evolve into a significant portfolio.
Tax Considerations (The “Kiddie Tax”)
Donors should be aware of the “Kiddie Tax” rules. For a minor, a certain amount of unearned income (interest, dividends, and capital gains) is tax-free, and a further amount is taxed at the child’s lower tax rate. However, once the income exceeds a specific threshold, it is taxed at the parents’ marginal tax rate. Strategic donors often coordinate with the parents to ensure the account is managed in a tax-efficient manner.
Investing in Hard Assets: Precious Metals and Bullion
In an era of digital banking and fiat currency fluctuations, some donors prefer the tactile security of physical assets. Gifting gold or silver coins—specifically bullion—is a classic baptismal tradition that aligns perfectly with modern wealth preservation strategies.
Gold as an Inflation Hedge
Gold has historically maintained its purchasing power over centuries. Gifting a 1-ounce gold Eagle or Maple Leaf coin at a baptism is more than a symbolic gesture; it is a hedge against inflation. While paper currency may lose value over the 20 years it takes for a child to reach adulthood, gold acts as a “store of value.” It provides a diversified layer to a child’s future portfolio that is not correlated with the stock market.
The Educational Value of Bullion
A physical gold coin serves as a tangible representation of wealth. As the child grows, the coin becomes a tool for explaining the concepts of scarcity, intrinsic value, and the history of money. Unlike a digital balance in a bank account, a gold coin is a “forever asset” that is rarely sold impulsively, making it an ideal long-term legacy gift.
The Gift of Life Insurance: A Financial Safety Net
While it may seem unconventional for a baptism, a whole life insurance policy for a child is a sophisticated financial instrument. These policies, often referred to as “Headstart” policies, provide several unique advantages that mature alongside the child.
Guaranteed Insurability
By purchasing a policy for an infant, you are locking in their insurability. Regardless of any health issues that may develop later in life, the child will always have coverage. Most of these policies also include options to purchase additional coverage at specific ages without a medical exam.
Cash Value Accumulation
Whole life insurance policies for children accumulate cash value over time. This cash value grows on a tax-deferred basis and can be borrowed against in the future for major life events, such as a wedding or a business venture. The premiums for children are incredibly low, allowing a donor to provide a substantial death benefit and a growing cash asset for a minimal monthly or annual cost.
Strategic Implementation: How to Present the Gift
A financial gift for a baptism can sometimes feel “invisible” compared to a wrapped box. To make the gift impactful, the presentation must bridge the gap between the abstract nature of finance and the emotional weight of the occasion.
Documenting the Vision
When gifting a 529 contribution or a custodial account, provide the parents with a formal letter or a “Investment Certificate.” This document should outline the vision for the gift—whether it’s for their future education, their first home, or their retirement. Including a projection of what the gift could be worth in 20 years adds a layer of excitement and demonstrates the donor’s long-term commitment to the child’s success.
Coordinating with Parents
Before opening any account, it is vital to coordinate with the child’s parents. They may have already established a 529 plan, and it is often more efficient to contribute to an existing plan than to start a new one. Furthermore, if the child is likely to qualify for need-based financial aid in the future, the ownership structure of these assets (whether held by the parent, the child, or a grandparent) can impact their eligibility.

Conclusion: The Legacy of Financial Empowerment
What to give as a gift for a baptism eventually comes down to the legacy one wishes to leave. While the sentimental value of traditional gifts is undeniable, the practical value of financial empowerment is transformative. By choosing to invest in a child’s future through strategic savings vehicles, equities, or hard assets, you are providing them with the most significant advantage possible: the freedom to pursue their dreams without the weight of financial insecurity. In the “Money” niche of gifting, the best present is not something they will play with today, but something that will change their life tomorrow.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.