
The transition into toddlerhood brings a variety of developmental milestones, but it also introduces parents to the economic realities of childhood illnesses. When a one-year-old experiences a common but taxing condition like diarrhea, the immediate focus is naturally on the child’s health. However, beneath the clinical concerns lies a complex landscape of personal finance, insurance navigation, and consumer choices. Understanding what to give a 1-year-old baby for diarrhea is not just a medical question; it is a financial one that involves budgeting for specialized supplies, managing insurance claims, and mitigating the hidden costs of domestic disruption.
For many families, the first year of a child’s life is a period of intense financial adjustment. Pediatric health issues, while common, can create significant volatility in a monthly budget if not managed with a strategic mindset. By viewing these occurrences through a financial lens, parents can make informed decisions that prioritize both their child’s recovery and their family’s long-term fiscal health.
The Direct Expenses of Toddler Recovery
When managing a gastrointestinal issue in a one-year-old, the first line of defense typically involves over-the-counter (OTC) products and dietary modifications. While these items may seem inexpensive in isolation, the cumulative cost of a multi-day illness can be surprising.
Oral Rehydration Solutions and the Retail Cost Burden
The primary recommendation for a one-year-old with diarrhea is often an Oral Rehydration Solution (ORS), such as Pedialyte or store-brand equivalents. From a financial perspective, ORS represents a significant retail markup compared to standard hydration. These solutions are formulated with precise ratios of electrolytes and glucose, and because they are marketed as “essential” medical supplies for infants, they command a premium price point.
A strategic consumer should analyze the price-per-ounce across various brands. Name-brand solutions can cost significantly more than generic alternatives, despite having nearly identical electrolyte profiles. For a family on a tight budget, opting for the store-brand version can result in a 30% to 50% cost saving without compromising the efficacy of the treatment. Furthermore, purchasing powder packets instead of pre-mixed liquid containers can offer long-term savings, as they have a longer shelf life and lower shipping/storage costs, making them an ideal staple for a well-managed household medical kit.
Nutritional Adjustments and Grocery Budget Fluctuations
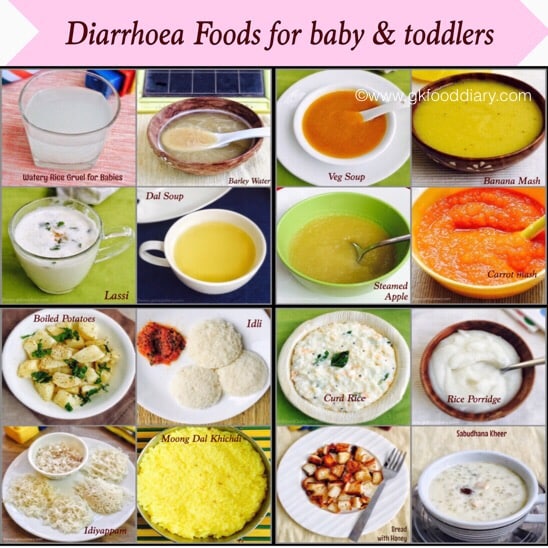
Dietary management is the second pillar of treating diarrhea in toddlers. This often involves a temporary shift toward specific foods like bananas, rice, applesauce, and toast (the BRAT diet) or other easily digestible complex carbohydrates. While these foods are generally affordable, the sudden need for specific items can lead to “convenience spending”—the act of buying small quantities of goods at high-priced neighborhood markets rather than in bulk.
Moreover, if a child requires specialized lactose-free formulas or probiotics during recovery, the grocery bill can spike. Probiotic supplements, in particular, are a high-growth sector in the wellness industry and can be quite expensive. Parents must weigh the cost of these supplements against their clinical necessity, often finding that investing in a high-quality, shelf-stable probiotic is a more cost-effective insurance policy against future digestive disruptions than buying individual refrigerated doses during an emergency.
Navigating the Healthcare System’s Financial Web
When home management is insufficient, the financial stakes of pediatric care escalate. Knowing when and where to seek professional medical advice is a critical component of personal finance for parents.
Urgent Care vs. Pediatrician: A Cost-Benefit Analysis
One of the most significant financial decisions a parent makes during an acute illness is the choice of healthcare venue. A visit to a primary care pediatrician is generally the most cost-effective option, as it typically falls under a standard co-pay structure. However, diarrhea often doesn’t adhere to business hours.
The financial “trap” for many parents is the Emergency Room (ER). For a non-life-threatening case of diarrhea, an ER visit can result in thousands of dollars in facility fees and out-of-network provider charges. An Urgent Care center is a middle-ground alternative, but even these can be costly depending on your insurance tier. Families should research their local options in advance, identifying which clinics are in-network and what their respective co-pays are. Being financially prepared for an after-hours medical need prevents “panic spending” in the high-stress environment of a hospital waiting room.
Optimizing Insurance for Pediatric Gastrointestinal Health

Insurance literacy is a vital skill for managing family wealth. When a child is treated for diarrhea, the billing codes used by the provider can affect the final out-of-pocket cost. Parents should review their Explanation of Benefits (EOB) statements to ensure that the services rendered—such as lab tests for pathogens—are covered under their plan’s “preventative” or “diagnostic” categories.
Furthermore, it is important to understand the deductible structure of your plan. For those on High Deductible Health Plans (HDHPs), every dollar spent on clinic visits for minor illnesses counts toward the deductible, which can be advantageous if you anticipate higher medical expenses later in the year. Conversely, if you are nearing your out-of-pocket maximum, it may be the ideal time to address other minor health concerns that you have been deferring for financial reasons.
The Indirect Financial Impact: Lost Wages and Daycare Fees
The “hidden” costs of a 1-year-old’s illness often far exceed the price of Pedialyte or co-pays. These are the indirect economic consequences of domestic disruption, primarily manifesting in labor productivity and prepaid services.
Opportunity Cost of the Caregiver’s Time
For working parents, a sick child usually means one or both caregivers must take time off work. If the parent does not have access to paid sick leave, this results in a direct loss of income. Even for those with paid leave, the “opportunity cost” is significant. Using a day of PTO to manage a toddler’s illness reduces the time available for actual rest or family vacations, which has a long-term impact on mental health and workplace burnout.
In a professional context, the loss of productivity can also affect performance reviews, bonuses, and career trajectory. From a business finance perspective, this is “unplanned downtime.” Families can mitigate this risk by cross-training both parents in the child’s medical care and alternating shifts, or by having a pre-negotiated arrangement with a secondary caregiver (like a grandparent or a trusted sitter) to minimize the impact on the primary breadwinners’ professional responsibilities.
The Non-Refundable Nature of Early Childhood Education
Most daycares and preschools have strict policies regarding gastrointestinal symptoms; a child must be symptom-free for 24 to 48 hours before returning. Financially, this is a double blow. Parents continue to pay the full tuition for the daycare—which is often the largest monthly expense after housing—despite the child not being able to attend.
There is rarely a “refund” for sick days in the childcare industry. Therefore, a three-day bout of diarrhea can effectively increase the daily cost of childcare by 20% to 30% for that month. When budgeting for childcare, savvy parents should factor in a “sick day buffer,” recognizing that they are likely paying for 10% to 15% more care than they will actually utilize due to common childhood illnesses.
Strategic Financial Preparation for Medical Emergencies
While a single episode of diarrhea is a manageable expense, it serves as a reminder of the need for robust financial planning within a family unit.
Building a Health-Specific Emergency Fund
Most personal finance experts recommend a general emergency fund of three to six months of expenses. However, for families with young children, a sub-category specifically for “Medical Contingencies” is advisable. This fund should ideally cover the maximum out-of-pocket limit of your insurance plan. Having this capital liquid and accessible ensures that when a medical need arises—whether it’s a simple case of dehydration or something more complex—the decision-making process is guided by medical necessity rather than bank account balances.

Leveraging Tax-Advantaged Accounts (HSA/FSA)
One of the most effective ways to pay for the costs associated with a sick 1-year-old is through Health Savings Accounts (HSAs) or Flexible Spending Accounts (FSAs). These accounts allow you to pay for medical expenses, including many OTC rehydration solutions and thermometer upgrades, using pre-tax dollars.
Using an HSA is particularly powerful because the funds roll over year to year and can be invested in the stock market. By paying for current medical expenses out-of-pocket and “reimbursing” yourself from the HSA years later after the funds have grown, you are essentially using a common childhood illness as a catalyst for long-term wealth building. For immediate needs, an FSA offers the benefit of the full annual contribution being available on day one of the plan year, providing a front-loaded financial cushion for early-year illnesses.
In conclusion, managing a 1-year-old’s health requires a dual focus. While the immediate priority is the administration of fluids and the monitoring of symptoms, the professional management of the family’s “business” requires an analytical approach to the costs involved. By understanding the retail market for medical supplies, navigating insurance efficiently, and accounting for the indirect costs of caregiving, parents can ensure that their family remains financially resilient in the face of the inevitable challenges of early childhood.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.