
Estate planning is often perceived as a task for the sunset years of life, yet it remains one of the most critical components of a robust personal finance strategy. A well-drafted will is more than just a legal document; it is a financial roadmap that ensures your accumulated wealth is distributed according to your wishes, minimizing tax liabilities and preventing unnecessary administrative costs for your heirs. Without a clear directive, your estate—regardless of its size—can fall into the hands of state-mandated intestacy laws, often leading to financial inefficiency and family disputes.

To build a comprehensive will that serves as a pillar of financial security, several key elements must be meticulously detailed. From asset allocation to the appointment of fiduciaries, understanding what to include in your will is essential for any individual committed to long-term wealth management and legacy preservation.
The Inventory of Assets: Cataloging Your Financial Legacy
The foundation of any effective will is a clear and exhaustive accounting of your assets. In the context of modern personal finance, this extends far beyond physical property. A comprehensive inventory allows your executor to identify, secure, and manage your wealth without the need for an expensive and time-consuming “treasure hunt.”
Tangible and Real Estate Assets
The most visible components of an estate are often real estate holdings and high-value personal property. Your will should clearly identify residential properties, investment real estate, and vacation homes. Beyond the deeds, consider including specific instructions for “sentimental wealth”—items like jewelry, art collections, or heirlooms—which, while sometimes lower in market value, can cause the most friction during the distribution process. Categorizing these assets early ensures they are treated as part of the total financial picture.
Financial Accounts and Investment Portfolios
A significant portion of modern wealth is held in intangible forms. Your will should account for bank accounts (checking, savings, CDs), brokerage accounts, and retirement vehicles such as IRAs or 401(k)s. While many retirement accounts allow for designated beneficiaries outside of a will, aligning these designations with your overall testamentary strategy is vital for a cohesive financial plan. Be sure to note any private equity interests, business ownership stakes, or partnership agreements, as these often require specialized valuation and transfer protocols.
Digital Assets and Cryptocurrency
In the digital age, a “Money” focused will is incomplete without addressing digital wealth. This includes cryptocurrency holdings (Bitcoin, Ethereum, etc.), digital storefronts, monetized social media accounts, and domain names. Because these assets are often secured by private keys or multi-factor authentication, your will should not only acknowledge their existence but also point toward a separate, secure memorandum that provides the technical means for your executor to access and liquidate or transfer these funds.
Strategic Distribution: Allocating Wealth with Precision
Once the assets are identified, the next step is determining how they should be divided. This is the core of the will’s function as a wealth-transfer tool. Strategic distribution is not merely about who gets what; it is about the timing, conditions, and financial structures used to facilitate the transfer.
Specific Bequests vs. Residuary Estates
Financial clarity is achieved by distinguishing between specific bequests and the residuary estate. A specific bequest involves leaving a set amount of cash or a specific asset to a named individual or organization. The residuary estate, conversely, consists of everything left over after debts, taxes, and specific bequests are satisfied. High-level financial planning often involves distributing the residue based on percentages rather than fixed dollar amounts, which protects the estate’s logic against market fluctuations that might occur between the writing of the will and its execution.
Contingent Beneficiaries and Disaster Clauses
A common oversight in personal finance is failing to plan for the “what if” scenarios. Your will must name contingent beneficiaries—individuals or entities who receive assets if your primary beneficiaries predecease you. Furthermore, a “disaster clause” outlines how assets should be managed if you and your primary heirs pass away in a single event. This prevents assets from flowing into the estates of others in a way that creates double taxation or unintended inheritance.
Providing for Minor Children through Financial Guardianship
If you have dependents, the will serves a dual purpose: appointing a personal guardian and establishing a financial framework for their care. From a financial perspective, this often involves the creation of a testamentary trust. Instead of a minor receiving a lump sum—which they cannot legally manage—the will can dictate that funds be managed by a trustee for the child’s education, health, and maintenance, with the remaining principal distributed at specific age milestones (e.g., 25, 30, and 35).
Appointing Financial Fiduciaries: Executors and Trustees
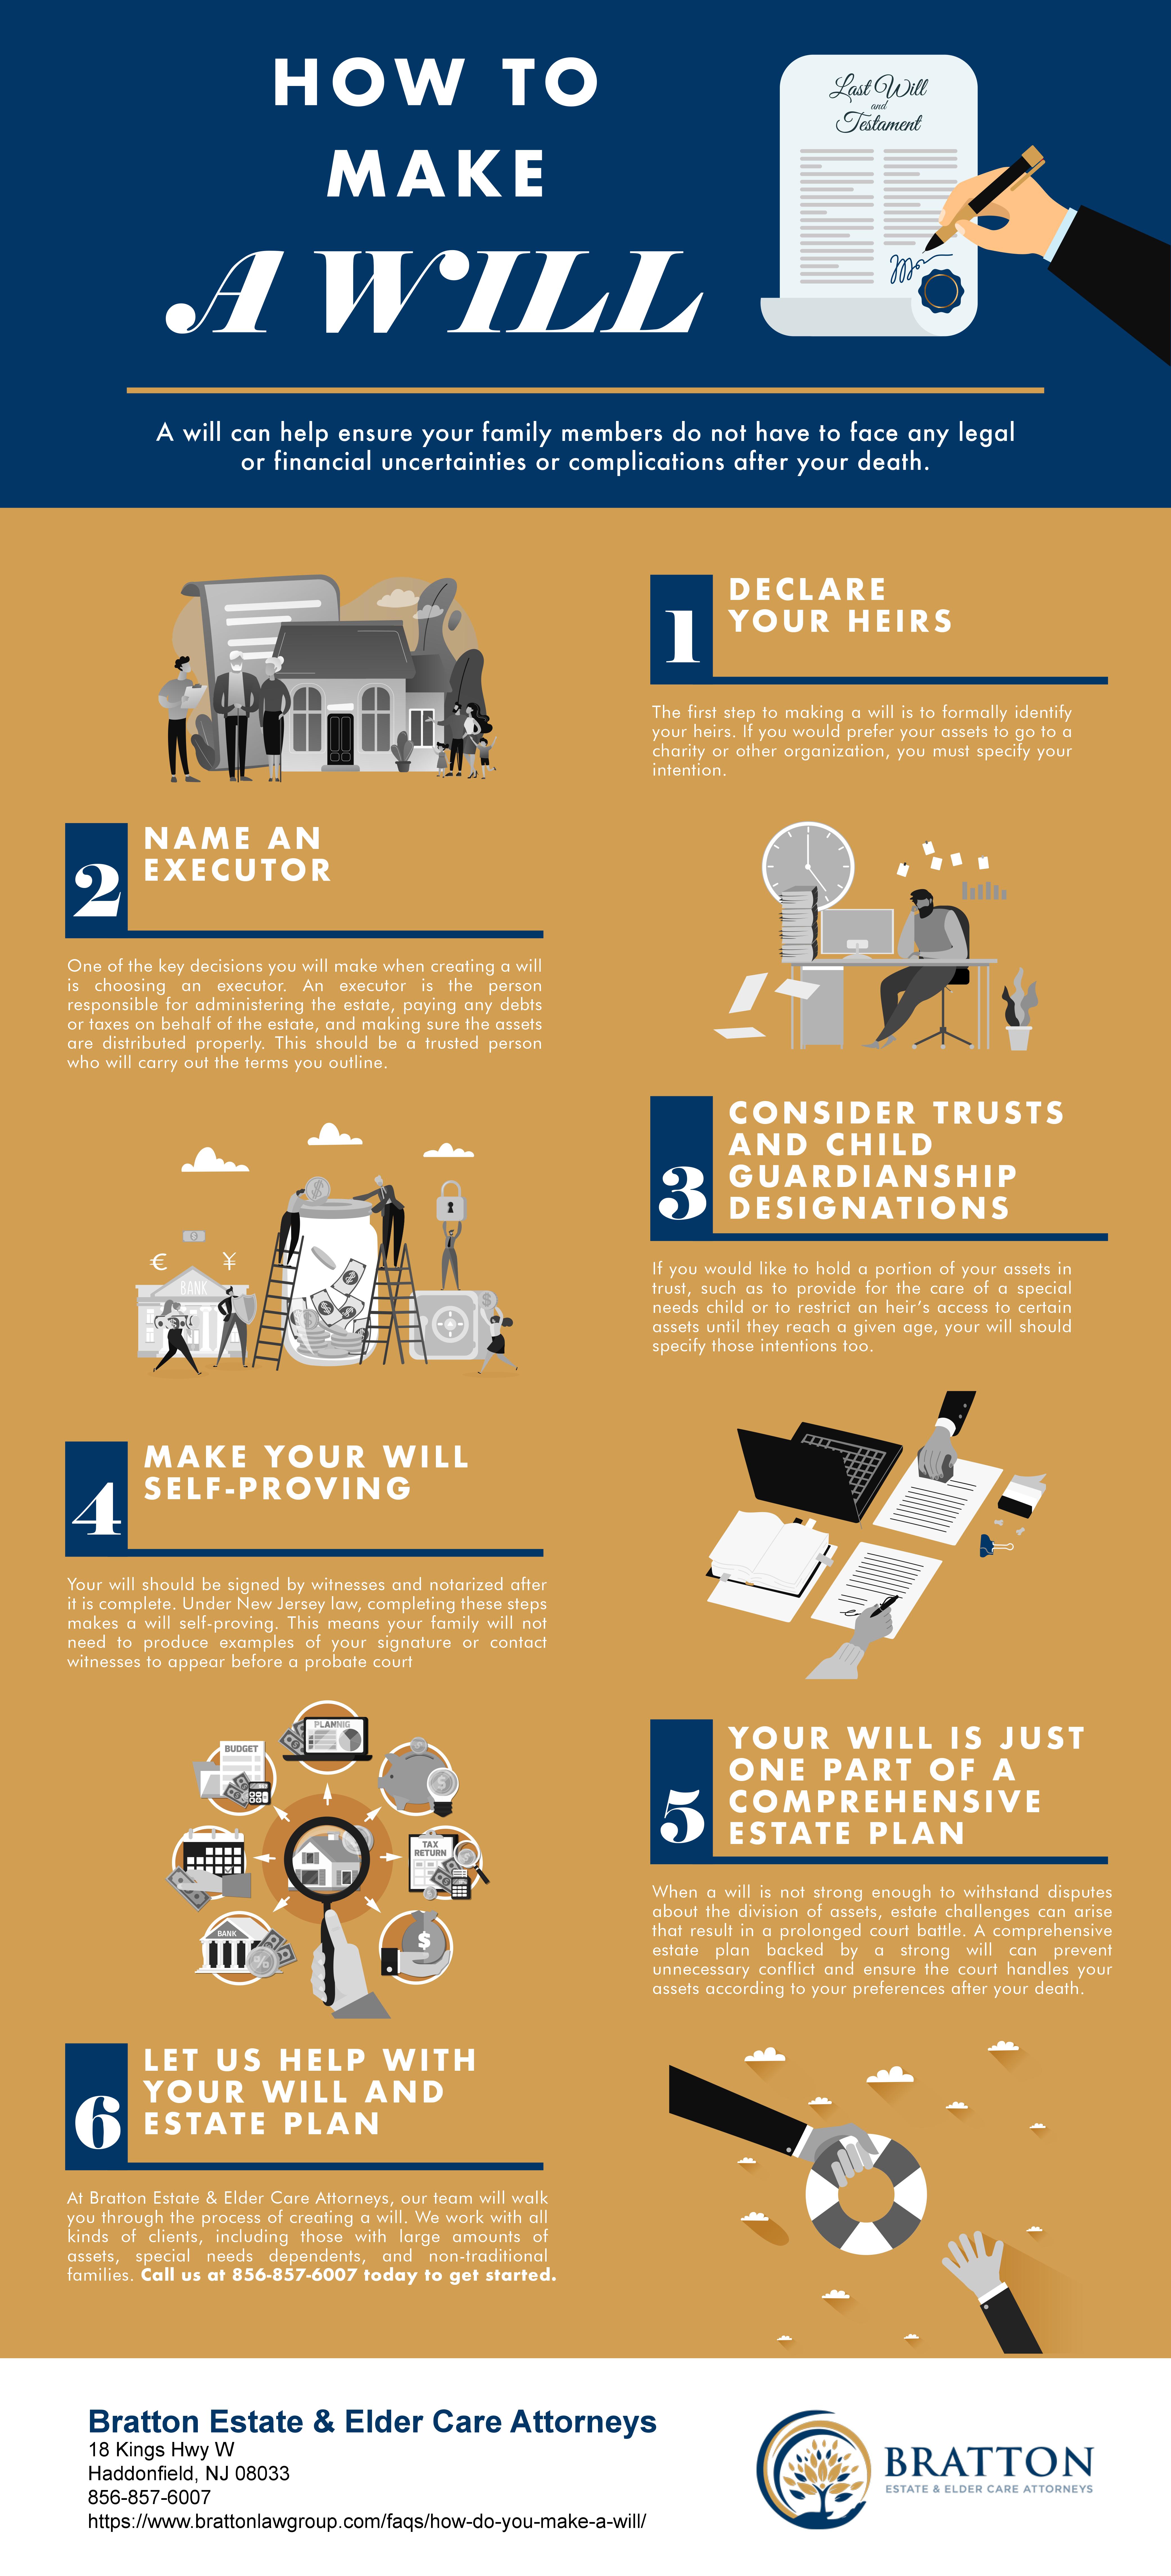
The effectiveness of your financial plan is entirely dependent on the individuals chosen to implement it. Selecting the right fiduciaries is a strategic decision that can save the estate thousands of dollars in management fees and legal hurdles.
The Role of the Executor
The executor is the CEO of your estate. Their financial responsibilities include filing final tax returns, paying off creditors, managing investments during the probate period, and distributing assets. When choosing an executor, look for financial literacy and organizational skills. While it is common to choose a family member, for complex estates involving business interests or diverse investment portfolios, many individuals opt for a professional executor or a trust company to ensure impartial and expert management.
Utilizing Trustees for Wealth Control
If your will creates trusts, you must appoint a trustee. Unlike an executor, whose role is generally short-term, a trustee may manage assets for decades. This individual or institution must understand investment strategies and fiduciary duties. The will should outline the trustee’s powers, including their ability to sell assets, reinvest capital, and make discretionary distributions. This ensures that the wealth you’ve built continues to grow and serve its intended purpose long after the initial probate is closed.
Compensation and Accountability
To prevent disputes and ensure professional oversight, your will should specify how fiduciaries are to be compensated. Whether it is a percentage of the estate or a flat fee, defining this prevents legal battles over “reasonable compensation.” Additionally, you may include requirements for periodic accounting to be provided to the beneficiaries, ensuring transparency in the management of the estate’s funds.
Mitigating Financial Leakage: Taxes, Debts, and Probate
A primary goal of including specific financial instructions in a will is to prevent “leakage”—the erosion of wealth through taxes, legal fees, and mismanagement. Strategic inclusion of certain clauses can significantly optimize the net value passed to heirs.
Debt Liquidation Strategies
Your will should provide clear instructions on how to handle outstanding liabilities, such as mortgages, personal loans, and credit card debt. You can specify whether a particular property should be passed “subject to the mortgage” or if the debt should be paid off using liquid assets from the estate before distribution. This clarity prevents heirs from being burdened by debt they cannot afford to service.
Tax Planning and the Marital Deduction
For high-net-worth individuals, the will is a tool for tax avoidance. In many jurisdictions, assets passed to a spouse are eligible for an unlimited marital deduction, delaying estate taxes until the second spouse passes. Your will can also utilize “credit shelter” or “bypass” trusts to maximize the use of estate tax exemptions. By structuring these provisions within the will, you ensure that the maximum amount of capital remains within the family unit rather than being diverted to the treasury.
Minimizing Probate Costs
Probate is the court-supervised process of authenticating a will and distributing assets. It can be expensive, often costing a percentage of the estate’s total value. While a will must go through probate, including “independent administration” clauses can allow your executor to act with minimal court supervision, drastically reducing legal fees and administrative delays. Furthermore, referencing “Transfer on Death” (TOD) or “Payable on Death” (POD) designations in your broader financial plan ensures that certain accounts bypass the probate process entirely, providing heirs with immediate liquidity.
Finalizing and Protecting the Document: Long-Term Financial Governance
A will is not a “set it and forget it” instrument. To remain a valid and effective part of your financial portfolio, it must be maintained with the same rigor as an investment account or a business balance sheet.
Regular Reviews and Trigger Events
Financial circumstances change. A will written when you had a net worth of $100,000 may not be appropriate when you reach $2,000,000. It is recommended to review your will every three to five years or after significant “trigger events,” such as the birth of a child, a marriage or divorce, the acquisition of significant property, or changes in federal tax law. Keeping the document updated ensures that your financial strategies remain aligned with current economic realities.
Storage and Accessibility
The best-laid financial plans are useless if the document cannot be found. The original signed will should be kept in a secure, fireproof location, such as a safe-deposit box or a professional vault. However, ensure that your executor knows exactly how to access it. In some jurisdictions, a safe-deposit box is sealed upon death, which can create a financial stalemate. Providing your executor with a copy and clear instructions on the location of the original is a final, vital step in the estate planning process.
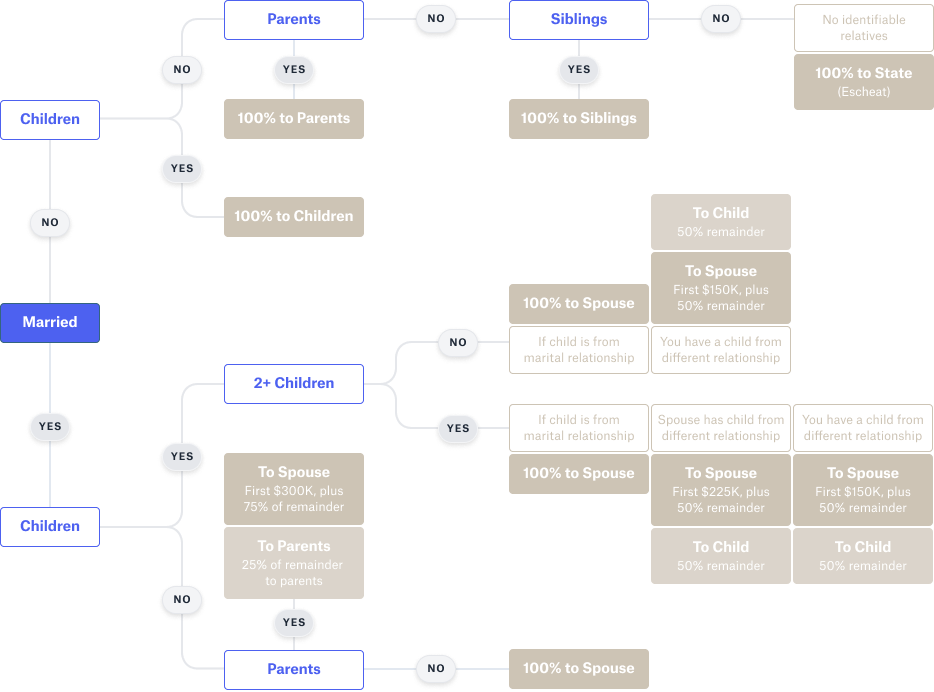
Legal Compliance and Professional Integration
Finally, while many “DIY” templates exist, a will is a legal instrument with profound financial consequences. It should be drafted or at least reviewed by an estate attorney in coordination with your financial advisor or CPA. This integration ensures that the language of the will complies with local laws and that the tax strategies contained within it are viable. A professionally vetted will provides the peace of mind that your wealth—the result of years of disciplined saving and investing—is protected, optimized, and destined for the people and causes you value most.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.