
The Foundation: Understanding Percentage Basics in Personal Finance
The seemingly simple question, “what percentage of 18 is 3,” transcends basic arithmetic; it’s a foundational inquiry that underpins nearly every aspect of personal and business finance. Far from being a mere academic exercise, mastering the concept of percentages is an indispensable skill for navigating financial landscapes, from budgeting and investing to understanding debt and evaluating business opportunities. At its core, a percentage represents a part of a whole, expressed as a fraction of 100. This fundamental relationship allows us to compare disparate figures, track changes over time, and make informed decisions about our money.

Why Percentages Matter Beyond the Classroom
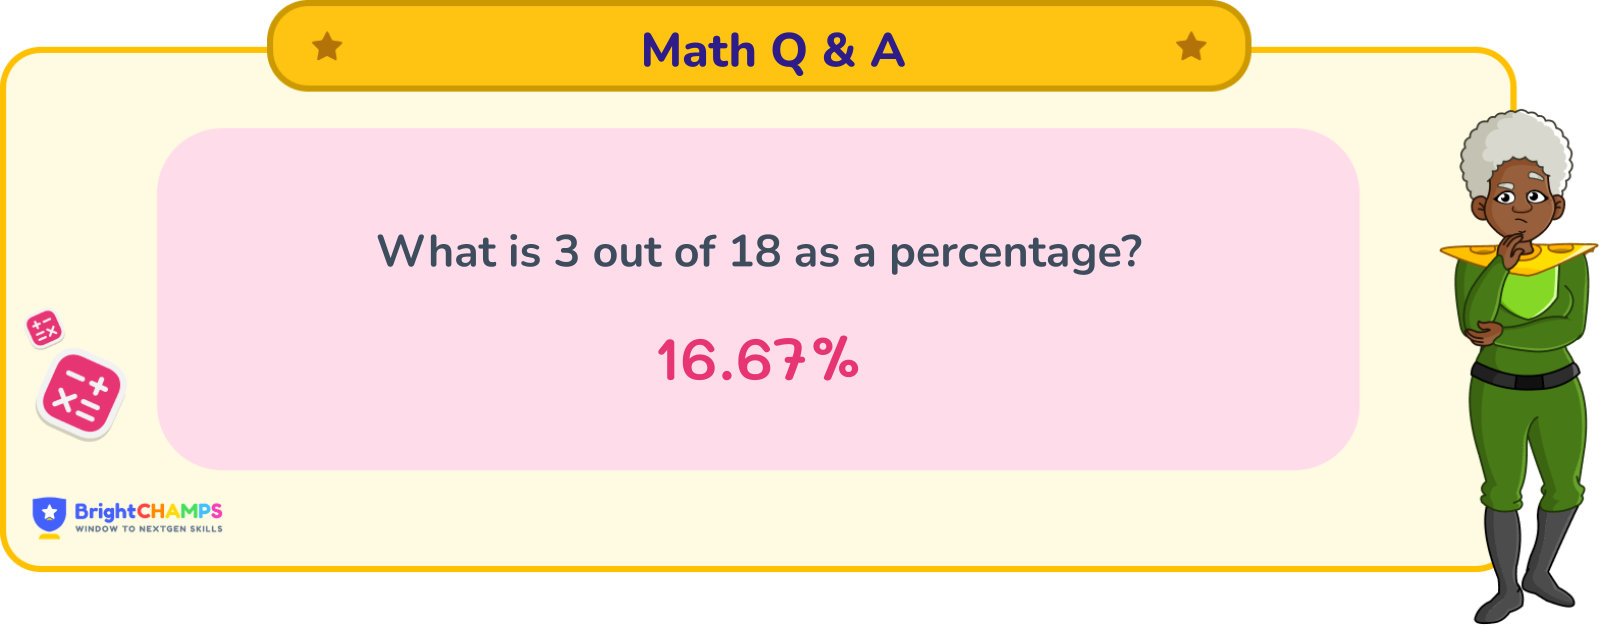
In the realm of finance, percentages provide a universal language. Whether you’re comparing the return on two different investments, understanding the impact of an interest rate on a loan, or allocating your income across various spending categories, percentages offer a standardized metric. They allow for an apples-to-apples comparison, irrespective of the absolute dollar amounts involved. For instance, knowing that 3 is 16.67% of 18 immediately tells you the proportion. This translates directly to financial scenarios: Is a 3% fee on an $18,000 investment significant? Absolutely, it’s $540. Is a $3 discount on an $18 item a good deal? It’s a 16.67% saving. Without this percentage lens, financial figures can be misleading or difficult to contextualize.
The Core Calculation: Deconstructing “Part/Whole * 100”
The formula for calculating a percentage is elegantly straightforward: (Part / Whole) * 100. Applying this to our central question, “what percentage of 18 is 3,” we identify 3 as the ‘part’ and 18 as the ‘whole.’ The calculation is therefore (3 / 18) * 100.
$3 div 18 = 0.16666…$
$0.16666… times 100 = 16.67%$
Thus, 3 is approximately 16.67% of 18. This basic calculation serves as the bedrock for countless financial analyses. For example, if you earned $18,000 last year and paid $3,000 in taxes, you paid 16.67% of your income in taxes. If an investment grew by $3 on an initial $18 principal, your return on investment (ROI) was 16.67%. Understanding this simple ratio and its translation to a percentage is the first critical step towards financial fluency.
Common Pitfalls and How to Avoid Them
Despite its simplicity, misinterpretations of the ‘part’ and ‘whole’ can lead to significant financial miscalculations. A common error is incorrectly identifying which number represents the base or the total. For example, when calculating a percentage increase, the ‘whole’ should be the original amount, not the new, larger figure. Similarly, when assessing a discount, the ‘whole’ is the original price. Another pitfall is neglecting to convert the decimal result of the division back into a percentage by multiplying by 100. Precision is paramount in financial calculations; rounding too early or incorrectly can compound errors, leading to inaccurate budgeting, investment projections, or debt assessments. Always double-check which figure represents the base from which the percentage is derived to ensure accuracy.
Strategic Applications in Personal Finance and Budgeting
Beyond the fundamental calculation, percentages are the backbone of effective personal financial management. They provide a clear, proportional view of where money comes from and, more importantly, where it goes.
Budget Allocation and the 50/30/20 Rule
One of the most popular budgeting frameworks, the 50/30/20 rule, is entirely percentage-based. It dictates that 50% of your after-tax income should go towards needs (housing, utilities, groceries), 30% towards wants (entertainment, dining out, hobbies), and 20% towards savings and debt repayment. Understanding how much of your total income each category represents (e.g., if your income is the ’18’ and a specific expense is the ‘3’) allows for granular control. If your current spending on wants is 40% (rather than 30%), you instantly know you’re over budget in that area. This percentage-driven approach makes financial planning flexible and adaptable, as the percentages remain relevant regardless of income fluctuations.
Tracking Spending Habits
Analyzing spending by percentage reveals powerful insights into financial behavior. Instead of just seeing that you spent $300 on dining out, knowing that it represents 16.67% of your $1,800 monthly discretionary income offers a far more actionable perspective. This percentage-based breakdown helps identify areas where spending might be disproportionate to your values or financial goals. For example, if a seemingly small category like coffee purchases consistently takes up 3% of your entire monthly budget (perhaps $54 out of $1,800), it might prompt a reevaluation. Visualizing spending in percentages on a pie chart or bar graph can make financial data more digestible and motivate changes.
Debt Management and Interest Rates
Interest rates, the cost of borrowing money, are inherently percentage-based. Whether it’s the Annual Percentage Rate (APR) on a credit card, a mortgage rate, or a personal loan, these percentages determine the true cost of debt over time. A 3% interest rate on a loan might seem small, but understanding its cumulative effect on a large principal (the ’18’ in our example, perhaps $180,000 for a mortgage) is crucial. Similarly, when making payments, knowing what percentage of your monthly payment goes towards interest versus principal helps you understand how quickly you’re reducing your debt burden. Strategic debt repayment often involves targeting debts with the highest interest percentages first, a technique known as the “debt avalanche” method, to minimize overall interest paid.
Maximizing Returns and Minimizing Risk in Investing
The world of investing is deeply intertwined with percentages, from calculating potential gains to assessing portfolio diversification and understanding associated costs.
Calculating Investment Returns (ROI)
Return on Investment (ROI) is a critical metric for evaluating the profitability of an investment, expressed as a percentage. It’s calculated by taking the net gain of an investment (the ‘part’) and dividing it by the original cost of the investment (the ‘whole’), then multiplying by 100. If you invested $18,000 and gained $3,000, your ROI would be (3,000 / 18,000) * 100 = 16.67%. This percentage allows investors to compare the performance of different assets or strategies, even if they involved vastly different initial capital. A 16.67% return on $18,000 is directly comparable to a 16.67% return on $180,000, providing clear insight into investment efficiency.
Understanding Portfolio Allocation
Diversification, a cornerstone of prudent investing, is achieved through percentage-based portfolio allocation. Investors strategically assign percentages of their total investment capital to various asset classes (e.g., stocks, bonds, real estate, commodities) to balance risk and potential return. A common strategy might be 60% stocks, 30% bonds, and 10% cash. If your total portfolio is $180,000, allocating 30% to bonds means $54,000 in bonds. These percentages are dynamic and should be adjusted based on an investor’s age, risk tolerance, and financial goals. Regularly rebalancing your portfolio to maintain your desired percentage allocations is key to staying aligned with your long-term strategy.
The Impact of Fees and Commissions
Even seemingly small percentage-based fees can significantly erode investment returns over time. Management fees (e.g., 0.5% to 2% annually) and transaction commissions, while appearing minor, compound over years. Consider an annual 3% fee on an investment portfolio valued at $180,000. That’s $5,400 deducted annually, which, over decades, can amount to a substantial sum that otherwise would have contributed to growth. Understanding these percentages, even if they seem like “a small part of the whole,” is vital for minimizing costs and maximizing net returns. Savvy investors scrutinize all percentage-based charges to ensure they are getting value for their money.
Business Finance and Online Income Streams
From small businesses to large corporations, and for individuals pursuing online income, percentages are instrumental in assessing profitability, structuring deals, and strategizing growth.
Profit Margins and Break-Even Analysis
Businesses live and die by their profit margins, which are always expressed as percentages. Gross profit margin (Gross Profit / Revenue * 100) indicates the profitability of core operations, while net profit margin (Net Profit / Revenue * 100) reveals the ultimate percentage of revenue that becomes profit after all expenses. If a business generates $18,000 in revenue and $3,000 in net profit, its net profit margin is 16.67%. This percentage is crucial for benchmarking against competitors, setting pricing strategies, and attracting investors. Break-even analysis also relies on percentages to determine the sales volume or price point needed to cover all costs, ensuring a business avoids operating at a loss.
Commission Structures and Royalty Rates
Many online income models are built on percentage-based compensation. Affiliate marketers earn a percentage commission on sales they refer. Content creators might receive a percentage of advertising revenue or royalties on digital products. Freelancers may charge a percentage of project costs for certain services. For example, a 16.67% commission on an $18 product sale yields $3. Understanding these percentage structures is essential for negotiating contracts, forecasting income, and evaluating the profitability of various online ventures. It helps individuals determine if the ‘part’ (their commission) is a fair and sustainable proportion of the ‘whole’ (the product’s price or service fee).
Discounting and Promotional Strategies
Retailers frequently employ percentage discounts (e.g., “15% off,” “Buy one, get 50% off”) as a promotional strategy. For consumers, understanding how to calculate these percentages is key to identifying genuine savings. A “what percentage of 18 is 3” scenario can be directly applied here: if an $18 item is discounted by $3, that’s a 16.67% saving. For businesses, carefully calculating the percentage of discount ensures profitability while attracting customers. Over-discounting can erode profit margins, while strategically applied percentage reductions can boost sales volume and market share.
Cultivating Financial Literacy Through Percentage Proficiency
Ultimately, the ability to effortlessly answer “what percentage of 18 is 3” and apply that understanding to complex financial scenarios is a hallmark of strong financial literacy.
Empowering Decision-Making
A solid grasp of percentages empowers individuals to make more informed and confident financial decisions. Whether it’s comparing loan offers, evaluating investment performance, understanding the true cost of a purchase, or optimizing a budget, the ability to think in percentages provides a powerful analytical framework. It moves you beyond simply accepting financial figures at face value and encourages a deeper, more critical examination of financial information. This analytical skill is a cornerstone of taking control of one’s financial destiny.
Beyond the Calculator: Developing Intuitive Understanding
While calculators and financial software are invaluable tools, developing an intuitive understanding of percentages is equally important. This means being able to quickly estimate percentages in your head and grasp the relative magnitude of numbers. For instance, intuitively knowing that 3 is a relatively small, but not insignificant, part of 18 (roughly one-sixth) allows for rapid financial assessments. This intuitive skill helps in real-time decision-making, such as quickly assessing if a discount is truly substantial or if a proposed allocation is proportionate to your goals, even before a precise calculation.
Continuous Learning for Financial Growth
Financial literacy is not a destination but an ongoing journey. The constant evolution of financial products, markets, and economic conditions necessitates continuous learning. Understanding percentages remains a fundamental, unchanging skill that serves as a constant companion throughout this journey. By regularly applying percentage calculations to everyday financial situations, from reviewing credit card statements to analyzing investment reports, individuals can continually refine their financial acumen and secure a more prosperous future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.