
In the world of finance, numbers rarely exist in a vacuum. Whether you are analyzing a stock portfolio, assessing the health of a small business, or managing personal debt, the ability to convert raw figures into percentages is a fundamental skill. When we ask, “What percentage is 10 out of 16?” we are performing a basic calculation that yields 62.5%. While the arithmetic is simple, the implications of a 62.5% ratio in financial contexts—ranging from profit margins to credit utilization—can be the difference between fiscal growth and stagnation.
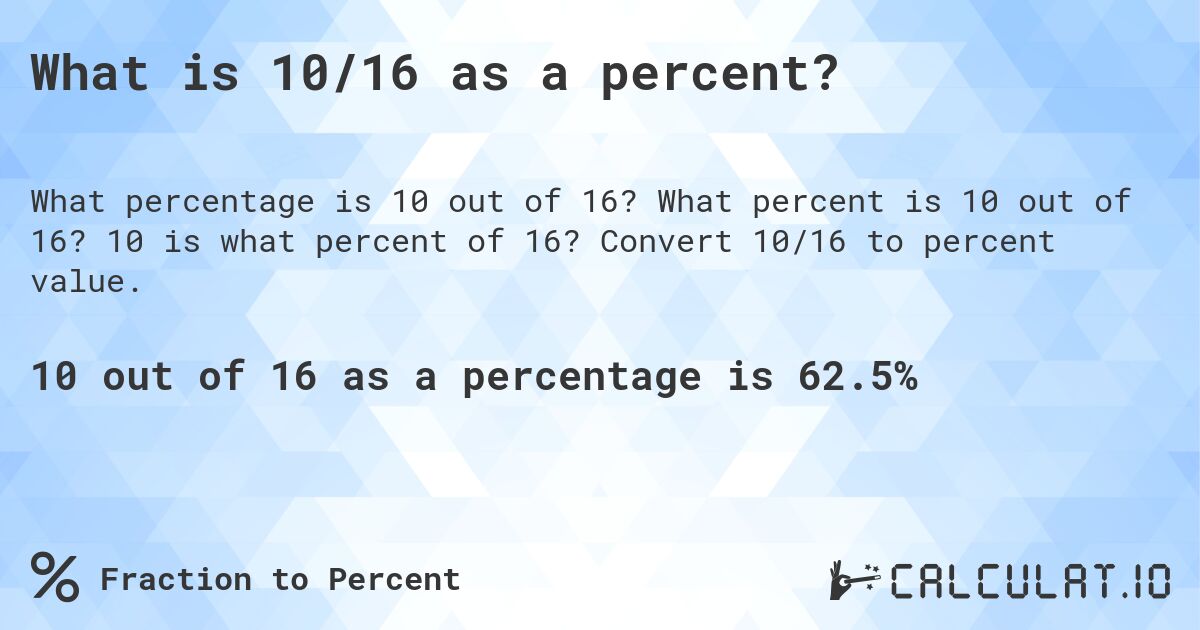
Understanding these proportions allows investors and business owners to benchmark performance against historical data and industry standards. A 62.5% figure can represent a robust gross margin, a concerning debt-to-income ratio, or a significant recovery in a bear market. To truly master the “money” niche, one must move beyond the basic division and explore how these percentages dictate strategy and capital allocation.
The Mathematical Foundation: Calculating 62.5% in a Financial Context
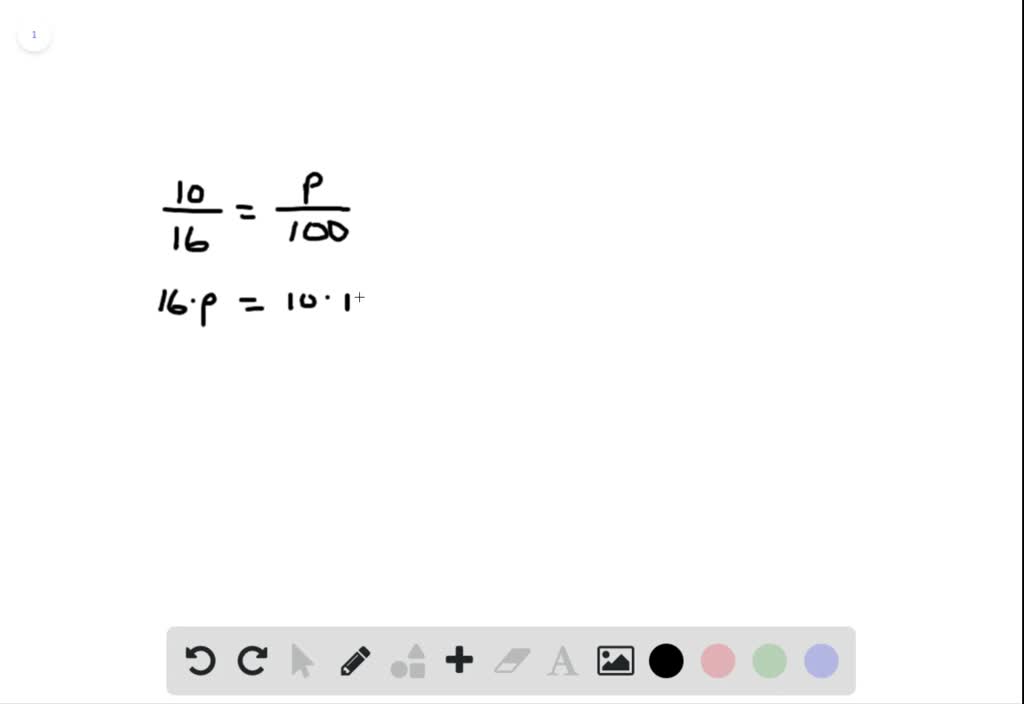
To find the percentage of 10 out of 16, the formula is straightforward: divide the part (10) by the whole (16) and multiply by 100.
10 ÷ 16 = 0.625
0.625 × 100 = 62.5%
In financial terms, this 0.625 is often referred to as a decimal factor or a multiplier. In accounting, this might represent a “cost-to-revenue” ratio or a “payout ratio.”
The Importance of Ratios in Personal Finance
In personal finance, percentages are the primary language of budgeting. For instance, many financial advisors recommend the 50/30/20 rule (50% for needs, 30% for wants, and 20% for savings). If an individual finds that their essential expenses account for 10 out of every 16 units of currency earned—or 62.5%—they are immediately alerted to the fact that they are over-leveraged in their “needs” category. This exceeds the recommended 50% threshold, signaling a need for lifestyle adjustments or debt restructuring.
Scaling the Numbers: From Tens to Thousands
While 10 out of 16 seems small, the ratio scales significantly in corporate finance. A company with $10 million in liabilities against $16 million in total assets maintains that same 62.5% ratio. In this context, it becomes a measure of solvency. Understanding the percentage allows a CFO to communicate the company’s leverage to shareholders without getting bogged down in the raw, often overwhelming, dollar amounts.
Percentages in Investment Performance and Portfolio Management
For an investor, 62.5% is a significant number. It could represent the total return on an investment over a specific period or the weight of a particular asset class within a diversified portfolio.
Evaluating Return on Investment (ROI)
If you purchased a stock at $16 and it rose by $10 to reach $26, your gain is 62.5%. In the world of investing, a 62.5% return is exceptional if achieved over a year, significantly outperforming the historical average of the S&P 500, which typically hovers around 10%. However, if that 62.5% return took ten years to realize, the annualized return (CAGR) would be much lower, roughly 5%. This illustrates why the percentage must always be viewed through the lens of time—a core principle of financial analysis.
Asset Allocation and Risk Mitigation
Modern Portfolio Theory emphasizes the importance of diversification. If an investor holds $16,000 in total assets and $10,000 of that is concentrated in a single high-growth tech stock, their portfolio is 62.5% weighted in one security. From a risk management perspective, this is often considered “over-concentration.” While it allows for massive gains if the stock performs well, it exposes the investor to significant “unsystematic risk.” Financial planners often suggest rebalancing when a single asset exceeds a certain percentage of the total, ensuring that the 62.5% concentration is brought down to a more manageable level, perhaps closer to 10% or 15%.
Dividend Payout Ratios
For income-focused investors, the number 10 out of 16 can represent a dividend payout ratio. If a company earns $1.60 per share and pays out $1.00 in dividends, its payout ratio is 62.5%. This is a critical metric. A ratio of 62.5% suggests the company is returning a healthy portion of profits to shareholders while still retaining 37.5% of its earnings to fund future growth, pay down debt, or bolster the balance sheet. If the percentage were much higher—say, 90%—the dividend might be at risk if earnings dip.

Business Profitability and Operational Efficiency
In the corporate world, percentages are used to strip away the noise of large numbers to reveal the underlying efficiency of an operation. A manager looking at a project that cost $10,000 to generate $16,000 in revenue is looking at a specific margin profile.
Gross Profit Margin vs. Net Profit Margin
Using our 10 out of 16 example, let’s assume a product sells for $16 and the Cost of Goods Sold (COGS) is $6. This leaves a gross profit of $10. In this scenario, the gross profit margin is 62.5% ($10 / $16).
A 62.5% gross margin is generally considered excellent in many industries, such as software or high-end luxury goods. However, if the $10 represents the costs and the $16 represents the revenue, the margin drops to 37.5%.
Business owners must constantly monitor these percentages. A shift from a 62.5% margin to a 60% margin might seem negligible, but on a scale of millions of dollars in revenue, that 2.5% variance can represent the entire budget for a marketing department or a research and development team.
Efficiency Ratios and Overhead Costs
Operating efficiency is often measured by how much of the gross profit is consumed by “Fixed Costs” or “Overhead.” If a business generates $16 in gross profit but spends $10 on rent, utilities, and administrative salaries, 62.5% of their profit is “eaten” by overhead. Financial optimization in this context involves finding ways to lower that percentage—perhaps by renegotiating leases or automating administrative tasks—to ensure that more of the 16 units of currency flow down to the net income line.
Credit, Debt, and the 62.5% Utilization Trap
Perhaps nowhere is the percentage 10 out of 16 more vital to personal financial health than in the realm of credit scoring. Credit utilization is a major component of FICO and VantageScore models.
The Impact on Credit Scores
If you have a credit card with a limit of $1,600 and you carry a balance of $1,000, your credit utilization ratio is exactly 62.5%. In the eyes of credit bureaus, this is a red flag. Financial experts generally recommend keeping credit utilization below 30% to maintain a high credit score.
At 62.5%, a consumer is viewed as “highly leveraged.” This suggests to lenders that the individual may be overly reliant on credit to fund their lifestyle, which increases the risk of default. This single percentage can lead to higher interest rates on future loans, or even the denial of a mortgage or auto loan. Reducing that 62.5% down to 20% or 10% is one of the fastest ways to improve a financial profile.
Debt-to-Income (DTI) Ratios in Lending
When applying for a mortgage, lenders look at the Debt-to-Income ratio. If your monthly debt obligations (car payments, student loans, credit cards) total $1,000 and your gross monthly income is $1,600, your DTI is 62.5%.
Most conventional lenders require a DTI of 43% or lower to approve a home loan. A 62.5% DTI indicates that the borrower has very little “breathing room” in their budget. Even a small financial emergency—like a medical bill or a car repair—could lead to a missed payment. Understanding that 10 out of 16 is 62.5% allows a prospective homebuyer to realize they need to either increase their income or aggressively pay down debt before entering the housing market.
Strategic Financial Decision Making
Ultimately, the goal of converting 10 out of 16 into 62.5% is to facilitate better decision-making. Whether you are a solo entrepreneur, a retail investor, or someone trying to fix their credit, the percentage provides a clear benchmark for action.
Capital Allocation Strategies
A business with $16,000 in excess cash must decide how to use it. If they decide to put $10,000 into a high-yield savings account and $6,000 into new equipment, they have allocated 62.5% of their liquid capital to “safety” and 37.5% to “growth.” This ratio defines the company’s current risk appetite. During an economic downturn, a 62.5% allocation to liquidity is a defensive masterstroke. During a bull market, it might be seen as overly cautious, potentially leaving money on the table.
Conclusion: The Power of Proportional Thinking
In conclusion, the question “What percentage is 10 out of 16?” serves as an entry point into the sophisticated world of financial analysis. The resulting 62.5% is more than just a number; it is a vital sign. It measures the health of a budget, the success of an investment, the efficiency of a business, and the reliability of a borrower. By mastering these proportions, individuals and organizations can move away from emotional decision-making and toward a data-driven approach to wealth creation and preservation. Whether you are looking at 10 dollars, 10 percent of a market, or 10 years of a 16-year financial plan, the percentage remains the most effective tool for clarity in the complex landscape of money.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.