
Managing chronic pain is not merely a clinical challenge; it is a significant financial undertaking. When a patient asks, “What pain reliever can I take with diclofenac?” they are often seeking more than just a medical interaction check—they are navigating a complex ecosystem of healthcare costs, insurance tiers, and the long-term economic implications of their wellness strategy. Diclofenac, a potent Non-Steroidal Anti-Inflammatory Drug (NSAID), is a staple in managing conditions like osteoarthritis and rheumatoid arthritis. However, from a financial and risk-management perspective, how we combine this medication with others can determine the trajectory of our personal healthcare budget.
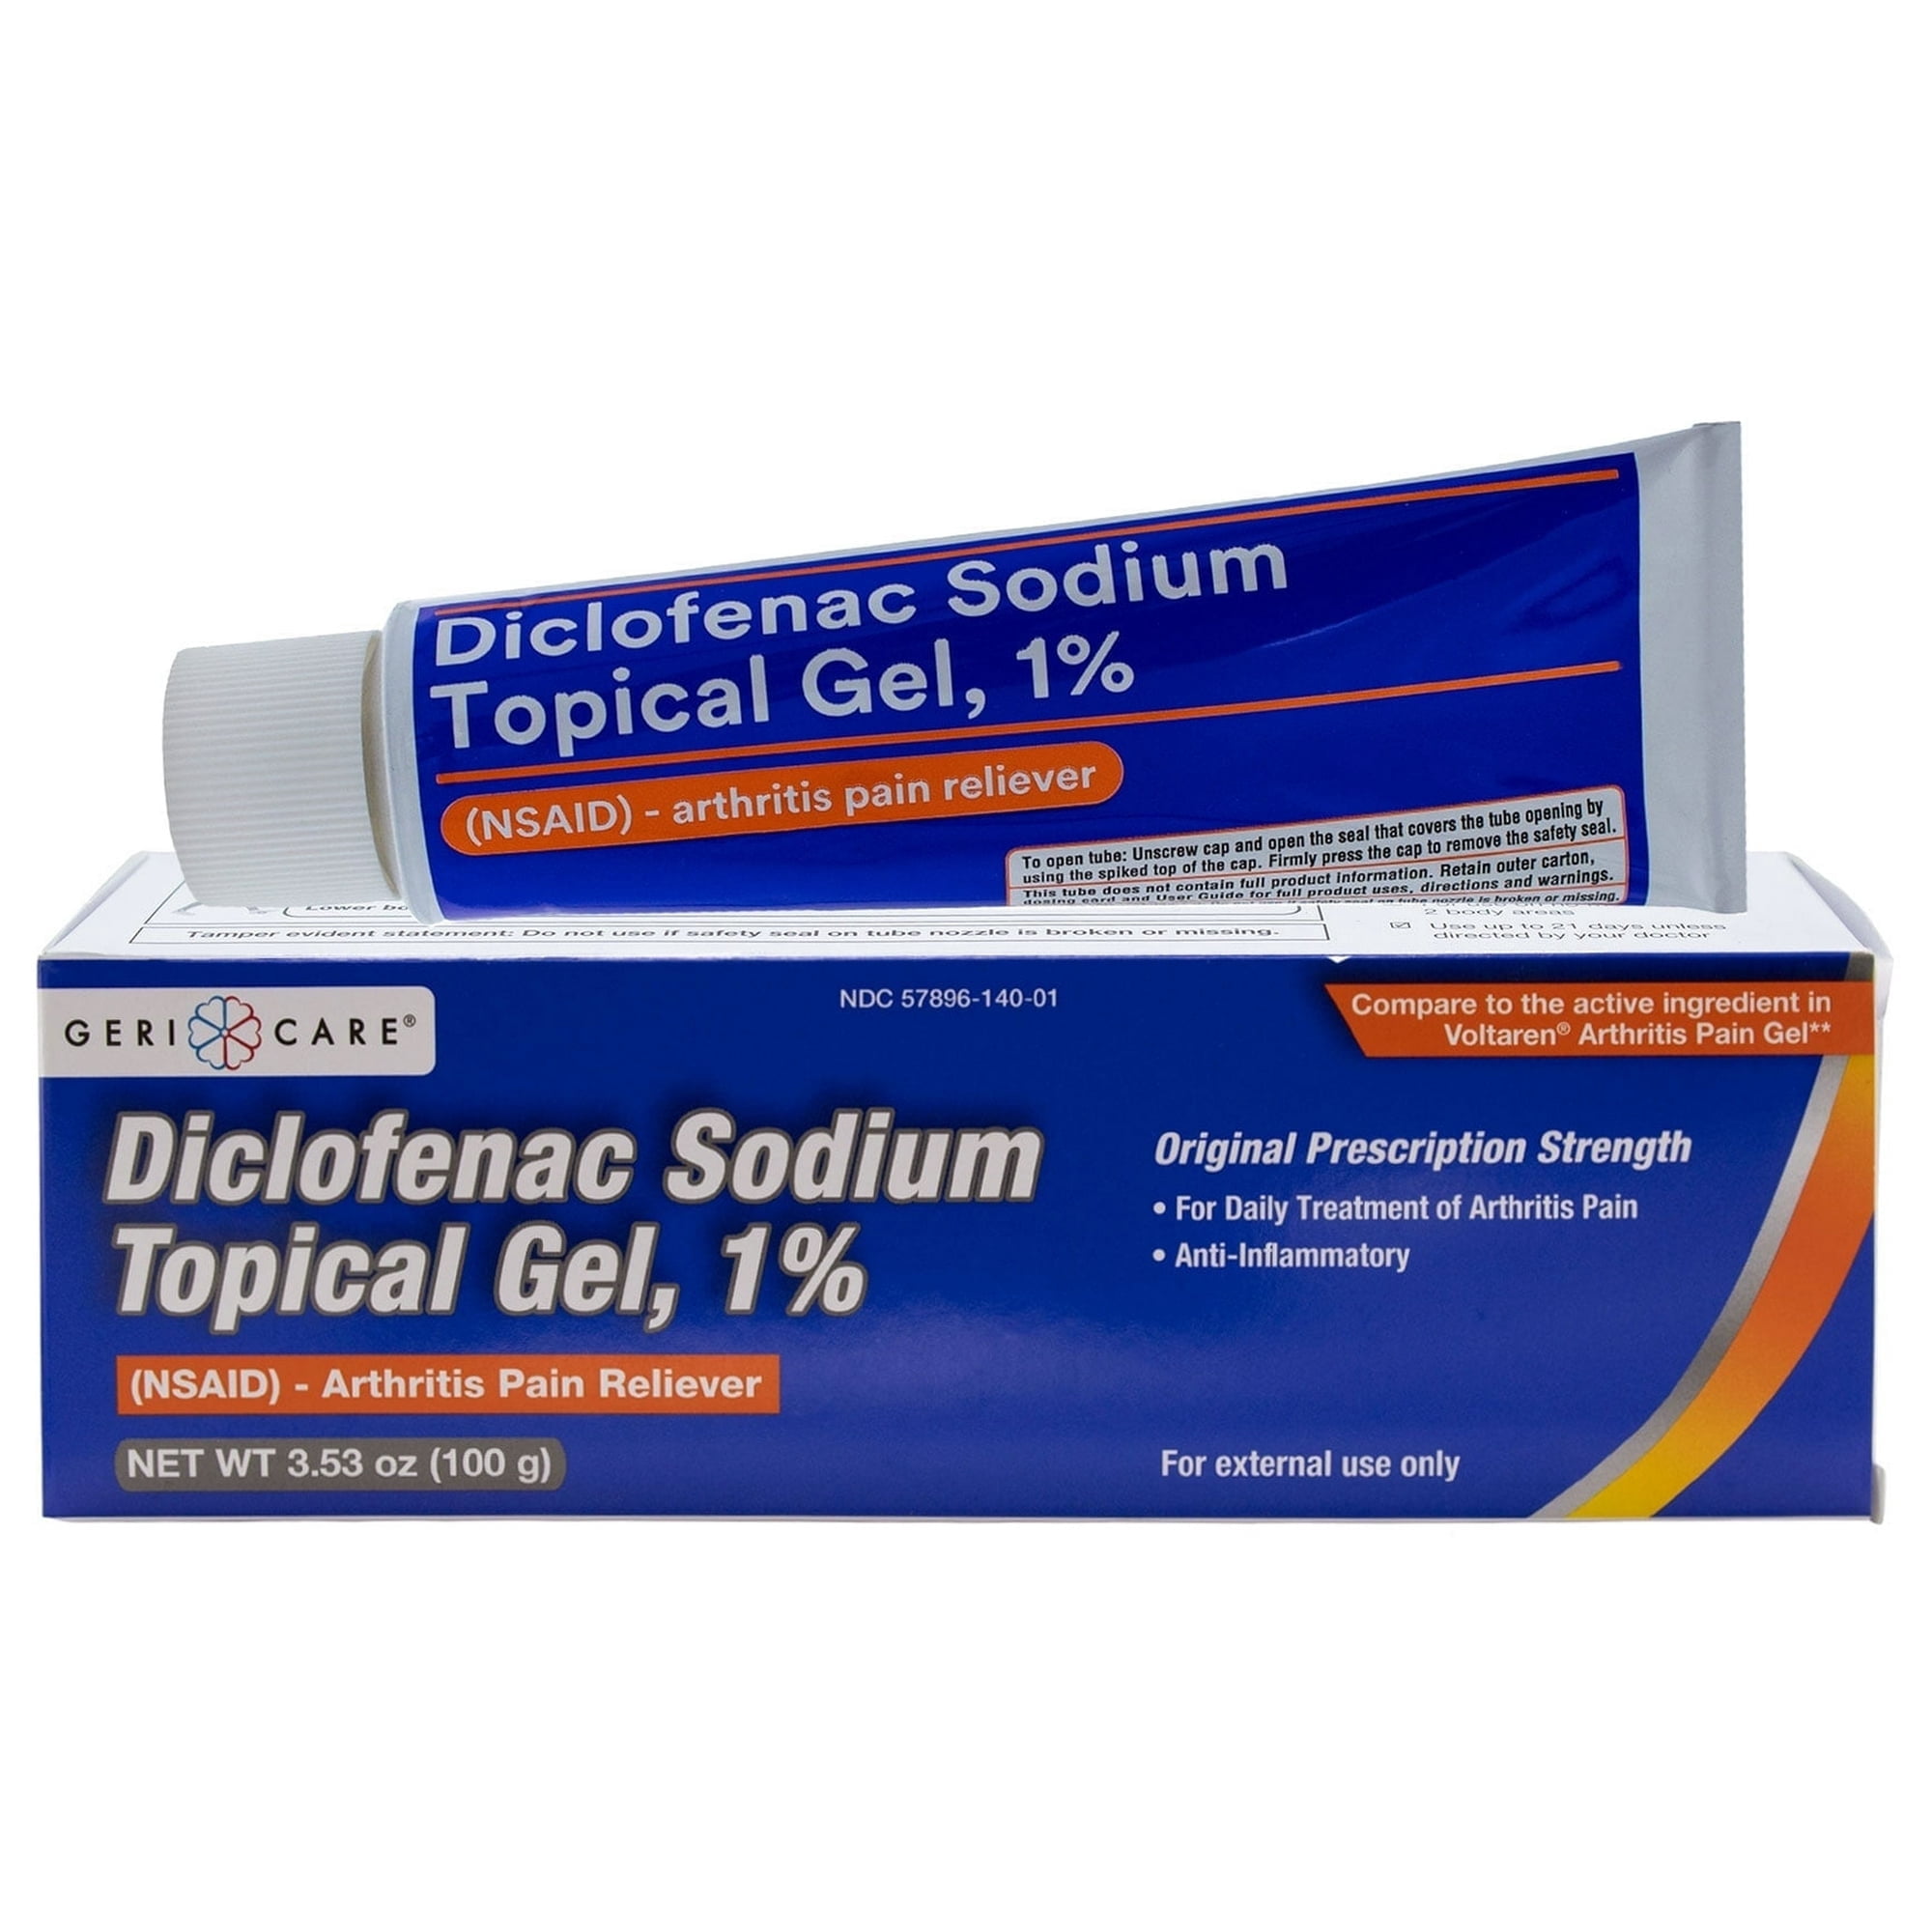
In this comprehensive guide, we analyze the financial strategy behind pain management, the cost-benefit analysis of medication combinations, and how to optimize your personal finance portfolio against the rising costs of chronic care.
The Cost-Efficiency of NSAID Management: Investing in the Right Relief
The global pharmaceutical market for pain relief is worth billions, and for the individual consumer, the choice between brand-name medications and generics is the first major financial hurdle. Diclofenac is available in various forms, including oral tablets, topical gels (such as Voltaren), and even patches. Each comes with a distinct price point and a different impact on your bottom line.
Generic vs. Brand Name: The ROI of Generic Diclofenac
One of the most effective ways to optimize a healthcare budget is to understand the Return on Investment (ROI) of generic medications. Generic diclofenac is chemically identical to its brand-name counterparts but can cost up to 80% less. For a patient on a long-term regimen, this price delta can represent thousands of dollars in annual savings. From a personal finance perspective, shifting to generics allows for the reallocation of funds into high-yield savings accounts or other investment vehicles, effectively turning a “cost of living” into an “opportunity for growth.”
The Hidden Costs of Improper Medication Stacking
When considering what can be taken with diclofenac, the financial stakes are high. Taking another NSAID—such as ibuprofen (Advil/Motrin) or naproxen (Aleve)—alongside diclofenac is not just a health risk; it is a financial liability. This combination significantly increases the risk of gastrointestinal bleeding and renal complications.
From an economic standpoint, the “cost” of an avoidable Emergency Room visit for a GI bleed far outweighs any temporary relief gained from the extra pill. In the United States, an ER visit can range from $500 to several thousand dollars depending on insurance coverage. Therefore, the most fiscally responsible pain reliever to pair with diclofenac is acetaminophen (Tylenol). Acetaminophen operates through a different metabolic pathway and does not multiply the risk of expensive gastric complications, making it the “budget-safe” choice for supplemental pain relief.
Insurance, Formularies, and Out-of-Pocket Optimization
Understanding the business of how drugs are paid for is essential for any savvy consumer. Health insurance companies use “formularies”—lists of covered drugs—to dictate what you pay at the pharmacy counter.
Navigating Pharmacy Benefit Managers (PBMs) and Tiers
Most insurance plans categorize drugs into tiers. Tier 1 usually includes low-cost generics (where generic diclofenac resides), while Tiers 3 and 4 include specialty or brand-name medications with high co-pays. When your doctor prescribes a specific formulation of diclofenac, such as the topical gel, it may be placed in a higher tier.
To optimize your out-of-pocket spending, it is vital to consult your plan’s formulary. If a brand-name topical is too expensive, a financial strategy would involve asking for the generic equivalent or exploring whether the oral version (if appropriate) provides a better cost-to-benefit ratio. Being proactive in this dialogue with your pharmacist can prevent “sticker shock” at the checkout.
Leveraging HSAs and FSAs for Pain Management
For those with High Deductible Health Plans (HDHPs), Health Savings Accounts (HSAs) are one of the most powerful financial tools available. Because contributions to an HSA are pre-tax, using these funds to pay for diclofenac and its compatible counterparts (like acetaminophen) effectively gives you a 20–30% discount based on your tax bracket.
Furthermore, over-the-counter (OTC) pain relievers are now HSA-eligible expenses under recent tax law changes. This means you can use tax-advantaged dollars to build a “pain relief kit,” ensuring that you are always prepared without dipping into your post-tax discretionary income.
The Economic Impact of Chronic Pain on Personal Finance
Chronic pain is more than a physical sensation; it is a “tax” on your productivity and future earning potential. The financial strategy for managing diclofenac use must account for the broader picture of your professional life.
Productivity Loss and the Value of Effective Relief
Economists often discuss “presenteeism”—the phenomenon of being at work but not fully productive due to illness or pain. For self-employed individuals or those in performance-based roles, the cost of untreated pain can manifest as missed deadlines, lost contracts, or slower career progression.
In this context, the cost of diclofenac and supplemental treatments is an investment in human capital. By identifying safe combinations (like diclofenac plus acetaminophen) that allow for a return to peak cognitive and physical performance, the individual is protecting their primary income stream. The “cost” of the medication is negligible compared to the “value” of a fully productive workday.
Long-Term Financial Planning for Chronic Health Conditions
If your need for diclofenac is tied to a chronic condition, your financial planning must shift from short-term budgeting to long-term wealth preservation. This involves:
-
Sinking Funds: Creating a specific “medical fund” within your budget to handle spikes in healthcare costs or physical therapy needs.
-
Disability Insurance: Ensuring that your income is protected if your condition worsens.
-
Automated Expense Tracking: Using digital tools to track every dollar spent on pain management to maximize tax deductions (for those whose medical expenses exceed a certain percentage of their Adjusted Gross Income).
Market Trends: The Business of Pain Relief Innovation
The landscape of pain relief is shifting, influenced by both technological advancement and market demand for non-opioid alternatives. As a consumer and an investor in your own health, staying informed on these trends can lead to better financial and physical outcomes.
Telemedicine as a Cost-Saving Tool for Prescription Management
One of the most significant shifts in the “business of health” is the rise of telemedicine. Instead of paying for a traditional office visit (which includes the cost of travel, time off work, and higher co-pays), many patients now use digital platforms to manage their diclofenac prescriptions.
Telemedicine providers often offer transparent, flat-rate pricing. For the question of “what can I take with diclofenac,” a quick digital consultation can provide a personalized answer and a prescription adjustment for a fraction of the cost of a specialist visit. This efficiency is a hallmark of modern financial management: reducing the “friction” and “middle-man costs” associated with a service.
The Rise of Bio-Similars and New Formulations
As patents expire, new “bio-similar” drugs enter the market, driving down prices through competition. While diclofenac is already a mature product, newer delivery systems (such as nanotechnology-enhanced gels) are entering the market. While these may initially be more expensive, their increased efficacy can lead to lower overall healthcare utilization—meaning fewer doctor visits and fewer secondary medications. Analyzing these new entries through a cost-benefit lens is essential for maintaining a lean healthcare budget.

Conclusion: The Bottom Line on Diclofenac and Your Finances
When you ask what pain reliever can be taken with diclofenac, you are engaging in a form of risk management. Choosing the right partner—acetaminophen—and avoiding the wrong ones—ibuprofen or aspirin—is a move that protects both your health and your bank account.
By applying the principles of personal finance to your medicine cabinet, you can transform a medical necessity into a streamlined component of your broader financial plan. Through the use of generics, tax-advantaged accounts like HSAs, and a keen eye on insurance formularies, you can ensure that the cost of relief never becomes a pain in itself. Ultimately, the goal of any financial strategy in healthcare is to buy back your time and your health at the most efficient price point possible.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.