
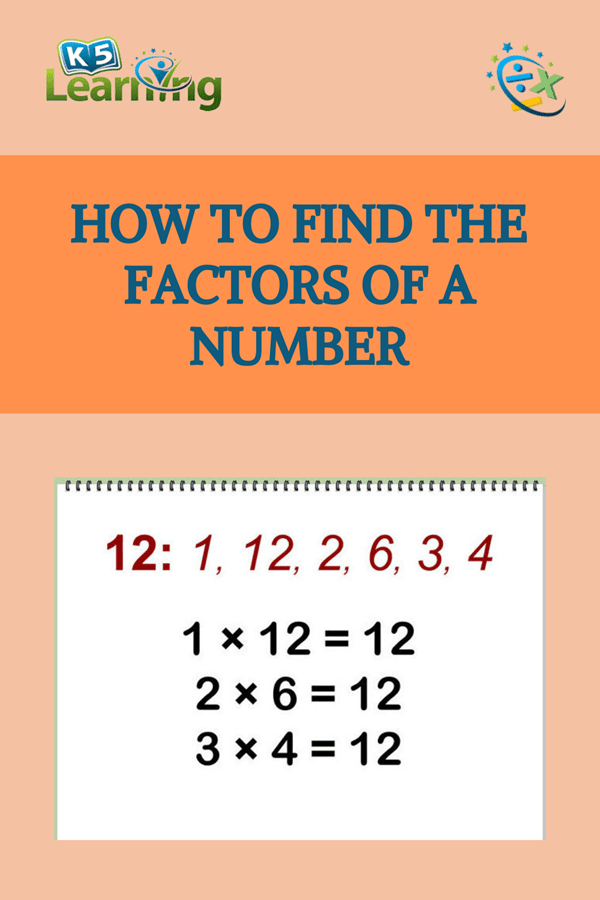
In the complex landscape of personal finance and business growth, understanding the mathematical foundations of wealth is not merely an academic exercise; it is a prerequisite for success. When we ask, “What number is a factor?” in a financial context, we are shifting our focus from simple arithmetic to the identification of the variables that exert a measurable influence on your net worth, profit margins, and long-term investment sustainability. A factor is, by definition, a number that divides into another number evenly, leaving no remainder. In the world of money, factors are the components of your financial life that yield clean, predictable results when optimized.

The Mathematical Nature of Wealth Accumulation
Wealth is rarely the result of a single, massive windfall. Instead, it is the product of a multiplicative process. When evaluating your financial health, you must view every dollar as a unit that can be divided and allocated. The concept of factors applies here because your financial output—your total savings or business revenue—is the product of several smaller, distinct variables.
Identifying Your Financial Factors
To improve your financial position, you must first deconstruct your total wealth into its constituent parts. If your “total” is your annual net income, the factors influencing that number include your hourly rate, the number of hours worked, your tax bracket, and your overhead expenses. If any one of these factors is zero or poorly managed, the entire product suffers.
Optimization Through Division
Just as factoring a polynomial helps simplify complex equations, factoring your budget helps simplify your financial life. When you break down large, intimidating expenses into smaller, manageable units—factors—you gain the ability to manipulate them. By analyzing the “factors” of your debt, such as interest rates, principal balances, and payment schedules, you can identify which specific elements can be divided further to minimize interest accrual. This is the core of financial engineering: finding the smaller numbers that, when adjusted, alter the final product in your favor.
Multipliers and the Compound Interest Factor
While factors are about breaking things down, they are inextricably linked to the power of multipliers. In personal finance, the most potent factor is time, which acts as a constant multiplier in the equation of compound interest.
The Power of the Constant Factor
In the formula for compound interest, $A = P(1 + r/n)^{nt}$, the variables $P$ (principal), $r$ (rate), and $t$ (time) are the critical factors. If you treat your savings rate as a factor, you are determining how much you can contribute to the product of your future wealth. A factor that remains consistent over a long period creates an exponential outcome. Many individuals fail to build wealth because they treat their savings as a remainder rather than a primary factor. To change your financial trajectory, you must treat your investment contributions as a non-negotiable factor that must be included in every month’s “equation.”
Factoring Out Inefficiency
Financial waste can be thought of as a “common factor” that appears across multiple areas of your life. If you have recurring subscriptions you don’t use, high-interest credit card debt, and a lack of tax-advantaged accounts, you have a common factor of inefficiency. To optimize your personal balance sheet, you must “factor out” these inefficiencies. This involves isolating them from your core productive assets and eliminating them, which effectively increases the “greatest common divisor” of your monthly cash flow.
Business Finance: Factoring for Profitability
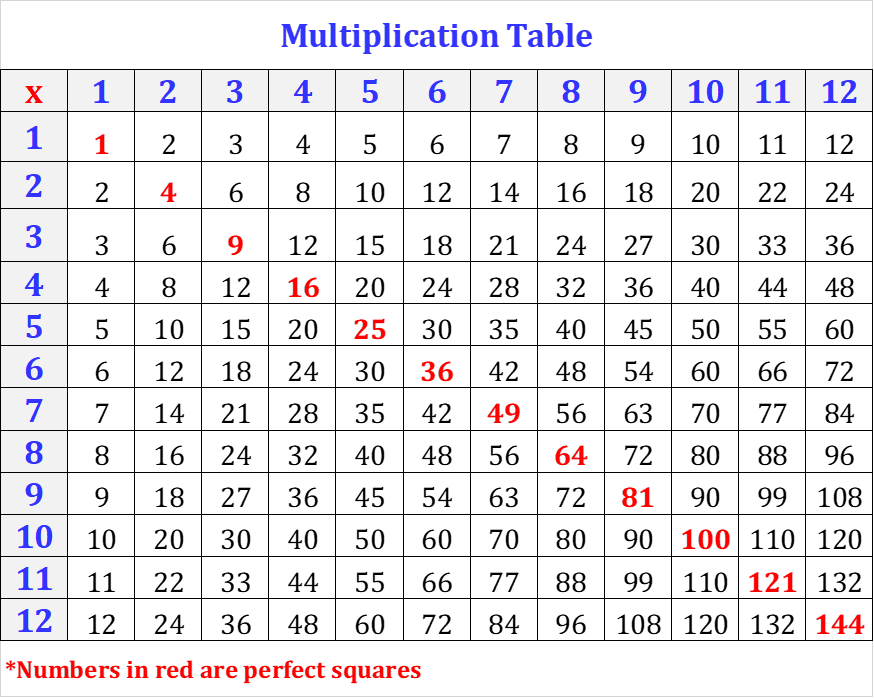
In a corporate or small business context, the question of what number is a factor becomes a matter of survival and scalability. Business owners who understand the math behind their operations can pivot faster and scale more efficiently than those who view their revenue as a vague, singular number.
The Cost of Goods Sold (COGS) as a Primary Factor
Every product you sell has a price, and that price is the product of your costs plus your margin. If your profit margin is shrinking, you must conduct a factor analysis of your COGS. Are your material costs rising? Is labor efficiency dropping? By isolating these variables, you move from guessing why your profits are down to knowing exactly which factor is the culprit. When you identify the specific factor causing the drag, you can apply a corrective coefficient to restore profitability.
Factoring Receivables: A Liquidity Strategy
Beyond pure arithmetic, “factoring” is a legitimate financial instrument. Invoice factoring is a business financing solution where a company sells its accounts receivable to a third party (a factor) at a discount. In this scenario, you are literally trading the uncertainty of future payments for immediate cash flow. This is a perfect example of using the concept of factors to solve a liquidity crisis. You are determining that the “factor” of time—the duration between issuing an invoice and receiving payment—is costing you more than the discount rate charged by the factor. You are effectively dividing your waiting period to multiply your operational capabilities today.
Behavioral Factors in Financial Decision Making
It is a mistake to assume that all financial factors are numeric. Human psychology acts as a significant variable that can either catalyze or sabotage your financial math.
The Emotional Variable
We often view our financial decisions as logical equations, but the inclusion of an emotional variable often distorts the result. Fear, greed, and the desire for social validation act as coefficients that multiply your expenses or divide your ability to take calculated risks. To achieve financial independence, you must learn to factor out emotion from your investment strategy. When the market is volatile, the “factor” of panic often leads to irrational selling. By recognizing that panic is an external, non-numeric factor, you can isolate it and prevent it from altering the outcome of your long-term financial strategy.
Developing a Quantitative Mindset
To master your money, you must adopt a quantitative mindset. This means viewing your financial goals as a series of equations. If your goal is to retire at 50, you must identify the factors that will lead to that result: your savings rate, your rate of return, and your target retirement income. If these factors do not produce the desired product, you must alter the inputs. You cannot negotiate with the math. If the equation does not balance, you must either increase your income factors (the numerator) or decrease your expense factors (the denominator).
Summary: Mastering the Equation of Your Life
The question “what number is a factor” is more than a request for arithmetic; it is a request for insight into the mechanics of your financial ecosystem. Whether you are managing personal savings, optimizing a business budget, or utilizing invoice factoring to maintain cash flow, you are engaging in the process of identifying, analyzing, and manipulating the components of your success.
Those who succeed in finance do not look at their bank accounts as monolithic totals. They see them as the result of a complex interplay of variables. They understand that by adjusting a single factor—whether it is reducing a subscription fee, increasing an investment contribution, or diversifying a portfolio—they can significantly impact the final product.
By deconstructing your financial reality into its smallest factors, you remove the mystery from wealth creation. You cease to be a spectator to your financial life and become the mathematician of your own prosperity. Start today by taking one area of your finances, breaking it down into its primary factors, and evaluating which ones are serving your long-term goals and which ones are effectively acting as a remainder that needs to be discarded. In the math of money, the outcome is entirely dependent on the quality of the factors you choose to multiply. Focus on the right numbers, treat your time and capital as the constants they are, and you will find that the product of your life’s work aligns with your vision for the future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.