
Navy Federal Credit Union (NFCU) has long maintained a reputation for offering some of the most competitive financial products in the United States. Serving service members, veterans, and their families, the institution operates differently than big-box commercial banks. Because it is a member-owned credit union, its profits are returned to members in the form of lower fees, better interest rates, and more robust reward programs. However, for those eligible for membership, the central question remains: which Navy Federal credit card is the best?
The answer is rarely universal. The “best” card is entirely dependent on your spending habits, your credit profile, and your financial goals. Whether you are looking to maximize cash back on groceries, earn points for international travel, or rebuild a damaged credit score, Navy Federal has a specialized tool designed for that specific purpose.
Understanding the Navy Federal Credit Union Value Proposition
Before diving into the specific card tiers, it is essential to understand the foundational benefits that apply to almost all Navy Federal credit cards. Unlike many major issuers, Navy Federal is notably consumer-friendly regarding its fee structures. Most of their cards feature no annual fees (with one notable exception), no balance transfer fees, and no foreign transaction fees. For a military-affiliated audience that often moves or travels overseas, the absence of foreign transaction fees is a significant financial advantage.
Membership Eligibility and the Credit Union Advantage
To apply for any of these cards, you must be a member of the credit union. Membership is open to active-duty members of all branches of the armed forces, veterans, Department of Defense civilians, and their immediate family members. This exclusivity allows the credit union to manage risk more effectively and offer lower interest rates than what is typically found in the general market.
Key Benefits Across the Portfolio
While each card has its own unique earning structure, they share a common DNA. All Navy Federal cards offer access to 24/7 member service, fraud notifications, and a user-friendly mobile app. Furthermore, their cards often come with lower-than-average APRs, making them safer options for those who might occasionally need to carry a balance.
Categorizing the Lineup: Which Card Fits Your Lifestyle?
Navy Federal offers a streamlined selection of credit cards, each targeting a specific persona. To find the best one for you, you must first identify your primary financial objective.
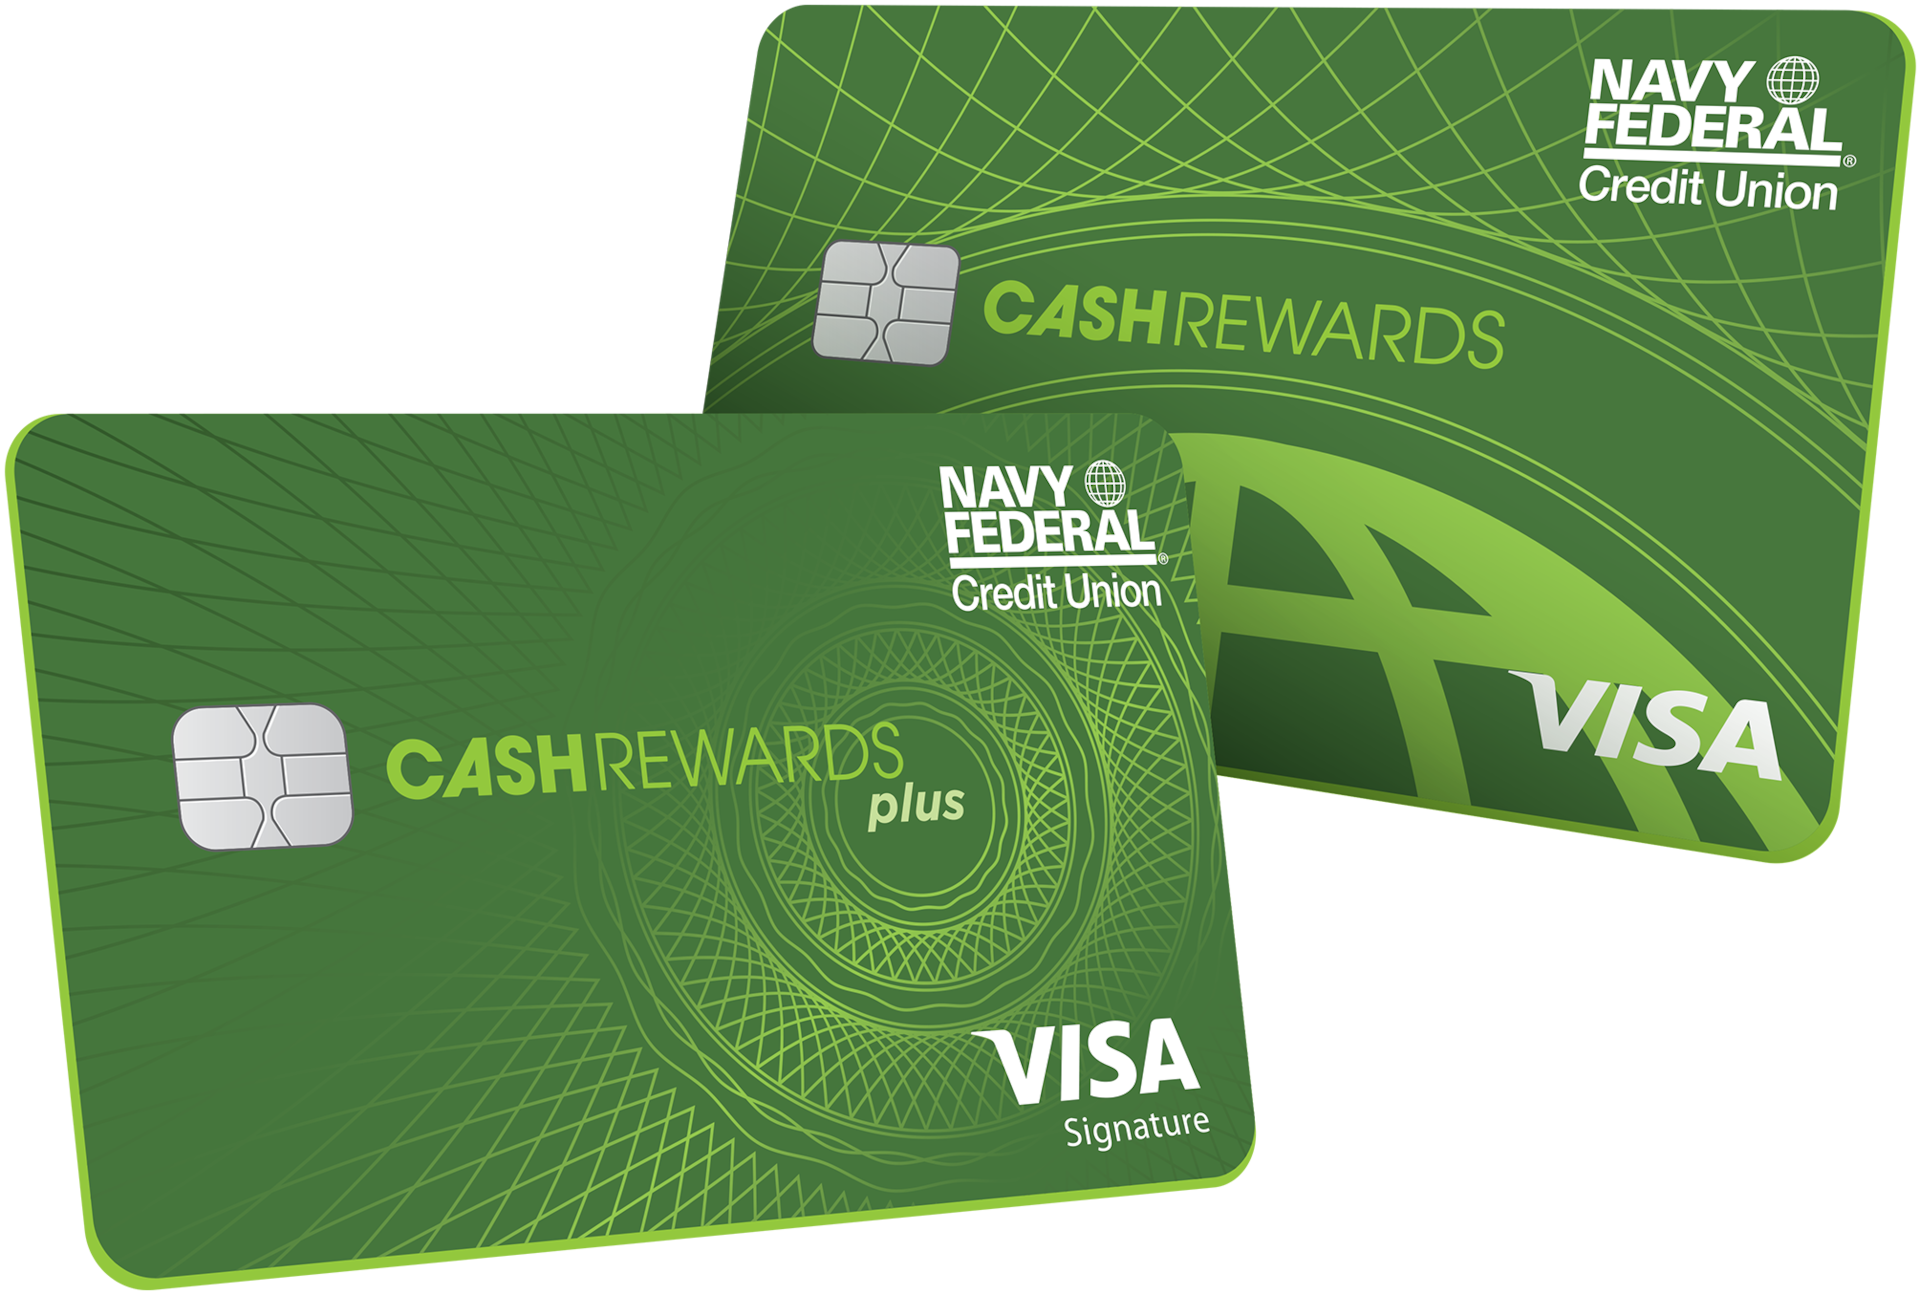
For Everyday Spending: The CashRewards Card
For those who prefer simplicity and liquid rewards, the CashRewards card is often considered the “gold standard” of the lineup. It is a straightforward cash-back card that rewards you for every dollar spent.
Standard members earn 1.5% cash back on all purchases. However, the card becomes significantly more competitive if you have a direct deposit into a Navy Federal checking account, which bumps the reward rate up to 1.75% on everything. There are no categories to track and no limits on how much you can earn. For the consumer who wants a “set it and forget it” card for daily expenses, this is frequently the best choice.
For Power Shoppers: The More Rewards American Express® Card
If your monthly budget is heavily weighted toward domestic life—specifically groceries, dining, and commuting—the More Rewards American Express card is likely your best option. This card offers an aggressive 3x points per dollar spent at supermarkets, 3x at restaurants, 3x at gas stations, and 3x on transit. All other purchases earn 1x point.
This card is particularly impressive because it carries no annual fee. Most cards with a 3x multiplier on groceries and gas charge a yearly premium, but Navy Federal provides this level of earning power for free. It is an ideal tool for families or individuals with high recurring monthly expenses in these specific “lifestyle” categories.
For Frequent Travelers: The Flagship Rewards Card
The Flagship Rewards card is Navy Federal’s premier offering. It is the only card in their portfolio with an annual fee (currently $49), but the benefits are designed to easily offset that cost.
Holders earn 3x points on travel and 2x points on everything else. This makes it one of the strongest “catch-all” cards available, as a 2% baseline return on all non-category spending is the industry benchmark for high-value cards. Additionally, the Flagship Rewards card provides a credit (up to $100) for Global Entry or TSA PreCheck every four years. For anyone who travels even twice a year, the combined value of the higher point-earning rate and the travel perks makes the $49 fee a negligible expense.
For Interest Rate Minimizers: The Platinum Card
Not everyone is looking for rewards. For individuals planning a large purchase or those looking to pay down existing high-interest debt from another bank, the Navy Federal Platinum card is the superior choice.
This card offers the lowest APR in the credit union’s portfolio. Because Navy Federal does not charge balance transfer fees, the Platinum card is a powerful debt-management tool. Moving a balance from a retail store card with a 29% APR to a Navy Federal Platinum card with a significantly lower rate can save a member thousands of dollars in interest over the life of the debt.
For Credit Builders: The nRewards® Secured Card
The “best” card for someone with no credit history or a damaged credit profile is the nRewards Secured card. This card requires a security deposit (starting at $200), which then becomes your credit limit.

Unlike many secured cards from “subprime” lenders, the nRewards card actually earns rewards (1x point per dollar) and has no annual fee. Most importantly, Navy Federal reviews the account starting at six months to see if the member is eligible to “graduate” to an unsecured CashRewards card and have their deposit returned. It is a bridge to better financial products and an essential tool for those in the credit-building phase.
Side-by-Side Comparison: Rewards, Fees, and Interest Rates
When choosing between these options, it helps to view them through the lens of a direct comparison. While the CashRewards and More Rewards cards both offer high yields, they serve different spending patterns.
Evaluating the Points vs. Cash Back Dilemma
In the Navy Federal ecosystem, points are generally valued at 1 cent each. Therefore, 3x points on the More Rewards card is equivalent to 3% cash back. The primary difference is the redemption process. Points can be redeemed for travel, gift cards, or merchandise, whereas cash back is typically more flexible, allowing for direct deposits into your savings or checking account.
If you spend heavily on gas and groceries, the 3% (3x points) of the More Rewards card will outperform the 1.75% of the CashRewards card, even if the redemption process requires an extra step in the mobile app.
Understanding APR and Variable Rates
While rewards get the most attention, the APR (Annual Percentage Rate) is a critical component of the card’s value. Navy Federal uses a tiered system based on creditworthiness. Even their rewards cards feature APRs that are often 5% to 10% lower than comparable cards from national banks like Chase or American Express. If there is any chance you will carry a balance from month to month, the Platinum card is the objective winner, but even the rewards-focused cards offer a safer “safety net” than most competitors.
Strategic Maximization: How to Leverage Your Navy Federal Card
To get the most out of your Navy Federal credit card, you must look beyond the initial sign-up. The credit union is known for its relationship-based banking, meaning the longer you are a member and the more products you use, the more likely you are to receive favorable terms.
Navigating the Navy Federal Ecosystem
One common strategy among “credit enthusiasts” is the two-card setup. By pairing the More Rewards American Express (for 3x on groceries, gas, and dining) with the Flagship Rewards (for 2x on everything else), a member can ensure they never earn less than a 2% return on any purchase. This “trifecta” approach—or in this case, “duo” approach—maximizes the total points earned across a household’s entire budget.
When to Ask for a Credit Limit Increase
Navy Federal is famously generous with credit limit increases (CLIs) for members who show responsible usage. Generally, after 91 days and three full billing cycles, members can request an increase. High credit limits are beneficial because they lower your overall credit utilization ratio—a key factor in your FICO score. Having a $20,000 limit on a Navy Federal card while only spending $1,000 a month keeps your utilization at 5%, which signals to other lenders that you are a low-risk borrower.
The Final Verdict: How to Choose Your “Best” Card
Selecting the best Navy Federal card requires a moment of honest financial reflection.
If you are a commuter and home cook, the More Rewards American Express is your winner due to the 3x multipliers on gas and groceries.
If you are a frequent flyer who wants the highest possible return on every single purchase, the Flagship Rewards card, with its 2x base rate and 3x travel rate, easily justifies its small annual fee.
If you are focused on debt reduction or need to finance a major life event, the Platinum card’s low interest rate is an unmatched utility.
If you value simplicity and cash liquidity, the CashRewards card (especially with direct deposit) provides a high-yield, no-fuss experience.
And finally, if you are starting from scratch, the nRewards Secured card is the most reliable path toward a prime credit score.
Navy Federal Credit Union provides a diverse toolkit. By matching your specific spending profile to the right card, you aren’t just opening a line of credit—you are optimizing your personal economy. In the world of personal finance, the “best” card isn’t the one with the most features; it’s the one that puts the most money back into your pocket based on the way you already live.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.