
In the annals of American pop culture, few figures represent the archetype of the stable, prosperous breadwinner as effectively as Ward Cleaver. As the patriarch of the Cleaver household in the iconic television series Leave It to Beaver, Ward served as a beacon of mid-century middle-class success. However, for many viewers, his professional life remained a bit of an enigma. While he was seen leaving every morning with a briefcase and returning every evening to a perfectly manicured suburban life, the specific nature of his daily tasks was rarely the focus of the narrative.
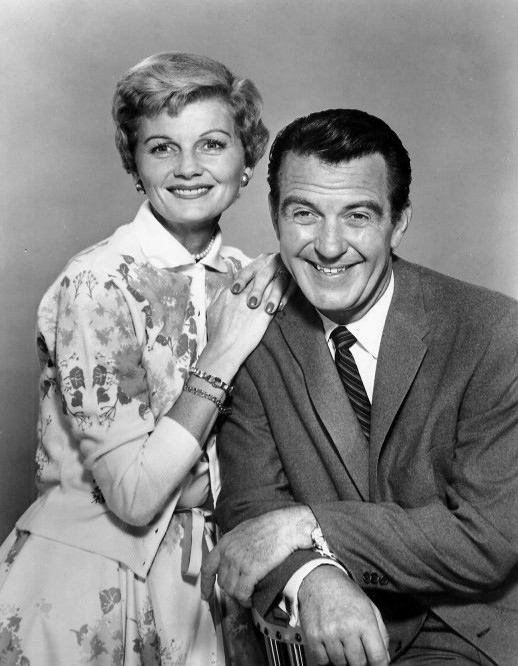
To understand what Ward Cleaver’s occupation was, one must look beyond the screen and into the business finance and personal finance structures of the 1950s and 60s. Ward Cleaver was a “Trust Officer” and an executive at a large, unnamed firm—a role that positioned him at the heart of the “Organization Man” era. Analyzing his career provides a fascinating window into the evolution of wealth management, corporate identity, and the shift from institutional loyalty to the modern era of diversified online income and self-directed investing.
The Mystery of the Briefcase: Defining the White-Collar Executive Role
While the show occasionally kept his duties vague, consistent clues and supplemental materials identify Ward as a high-level executive, specifically a Trust Officer. In the context of business finance, a Trust Officer is a professional responsible for managing assets on behalf of clients, ensuring fiduciary duties are met, and overseeing the long-term growth of estates or corporate funds. This role required a deep understanding of investment strategies, tax laws, and risk management.
The Trust Officer and Fiduciary Responsibility
As a Trust Officer, Ward’s primary professional value lay in his reliability and his grasp of financial instruments. In the mid-20th century, this was a prestigious position that signaled a high level of education and social standing. Unlike the volatile world of modern day-trading or the high-risk tech startups of today, the business of “Trust” was built on the principle of steady, compounding growth and capital preservation.
From a personal finance perspective, this occupation provided Ward with a window into how the wealthy maintained their status. He wasn’t just a cog in a machine; he was a gatekeeper of capital. This role required a mastery of the financial tools available at the time, such as municipal bonds, blue-chip stocks, and insurance products. His professional proximity to wealth likely informed his own disciplined approach to household budgeting and long-term planning.
The Organizational Structure of Mid-Century Business Finance
Ward Cleaver’s career was defined by “The Organization.” During this period, the American corporate structure was characterized by a social contract: in exchange for loyalty and a 40-year commitment, the company provided a stable salary, comprehensive health benefits, and a guaranteed pension. This “lifetime employment” model is the antithesis of the modern gig economy and the frequent “job-hopping” seen in the contemporary tech and finance sectors.
For Ward, the business finance of his employer was inextricably linked to his personal financial security. The firm’s success ensured his mortgage was paid and his children’s college funds were growing. This era represented the peak of the institutionalized middle class, where a single white-collar income could support a family of four, a three-bedroom home in a suburb like Mayfield, and a new car every few years.
The Single-Income Household: Analyzing 1950s Purchasing Power
One of the most frequent questions modern viewers ask when watching Leave It to Beaver is how a single executive salary could afford such a comfortable lifestyle. To answer this, we must dive into the macroeconomics of the era and the specific personal finance advantages enjoyed by the mid-century executive.
Real Estate and the Mayfield Investment
In the 1950s, the ratio of median home prices to median household income was significantly lower than it is today. For a professional in Ward’s position, purchasing a home in a premium suburb was not just a lifestyle choice; it was a primary investment vehicle. Real estate in the post-war era benefited from stable interest rates and a booming domestic economy.
Ward’s occupation allowed him to leverage his steady income to secure favorable financing—a cornerstone of building generational wealth. Because his income was predictable, his ability to manage debt was high. In modern financial terms, Ward maintained a low debt-to-income ratio, allowing him to allocate surplus funds into savings and insurance rather than servicing high-interest consumer debt.
The Inflation Factor: Comparing Salaries Across Decades
While an executive salary in 1957 might have been numerically low by today’s standards (often ranging between $10,000 and $15,000 annually), its purchasing power was immense. When adjusted for inflation, Ward’s salary would be equivalent to a high-six-figure income today. Furthermore, the cost of essential services—healthcare, education, and utilities—consumed a much smaller percentage of the household budget.
This financial “breathing room” is what allowed the Cleavers to maintain their iconic lifestyle. Without the burden of student loans (which were virtually non-existent for his generation) or the high costs of digital subscriptions and modern technology, Ward could focus his financial strategy on traditional wealth-building: equity in the home, a robust life insurance policy, and a diversified portfolio of stocks and bonds.

The Death of the Pension and the Birth of the Soloist
The transition from the world of Ward Cleaver to the modern financial landscape is marked by a fundamental shift in who bears the risk of retirement and income stability. In Ward’s day, the corporation managed the “business finance” of retirement through defined-benefit pension plans. Today, that responsibility has shifted almost entirely to the individual.
From Institutional Security to Self-Managed Portfolios
The “Organization Man” model began to erode in the late 1970s with the introduction of the 401(k) and the rise of shareholder primacy. For a modern professional occupying a role similar to Ward’s, the financial landscape is far more complex. Instead of relying on a company pension, today’s executives must be experts in personal finance, navigating IRA contributions, tax-advantaged accounts, and index fund allocations.
This shift has necessitated a more proactive approach to investing. While Ward could afford to be passive—trusting his employer to handle the long-term math—the modern worker must be an active participant in their financial destiny. The “Trust Officer” of today is often the individual themselves, managing their own “family trust” through digital brokerage accounts and automated investment tools.
The Rise of Side Hustles as a Financial Safety Net
Another major departure from the Cleaver era is the emergence of multiple income streams. In Leave It to Beaver, the idea of Ward having a “side hustle” would have been seen as a sign of financial distress. In the current economy, however, diversifying income through online ventures, consulting, or rental properties is seen as a mark of financial intelligence.
The modern “Ward Cleaver” doesn’t just work a 9-to-5; they likely manage a portfolio of side hustles to hedge against corporate downsizing. Whether it’s monetizing a professional skill set through an online course or investing in REITs to generate passive income, the goal remains the same: achieving the stability that Ward enjoyed, but through a decentralized rather than institutionalized model.
Leveraging Modern Tools for Ward Cleaver-Level Stability
While we may no longer live in an era of lifetime employment and guaranteed pensions, the digital age has provided us with tools that Ward Cleaver could only have dreamed of. Achieving his level of financial peace in the 21st century requires a blend of his old-school discipline and modern technological leverage.
Creating Online Income Streams to Counteract Market Volatility
For many, the dream of the “Mayfield lifestyle” is now being chased through digital entrepreneurship. The ability to generate online income—whether through e-commerce, affiliate marketing, or software-as-a-service (SaaS) platforms—has democratized the path to the middle class. You no longer need to be a “Trust Officer” at a major firm to access high-level income; you can build a “digital trust” from a home office.
This shift has changed the “occupation” landscape. A modern executive might work remotely for a firm in another state while simultaneously managing an automated dropshipping business or a high-yield dividend portfolio. This diversification is the 21st-century equivalent of Ward’s corporate seniority—it provides a buffer against the unpredictability of the global market.
Investing in the Modern ‘Blue Chip’ Environment
Ward’s investment philosophy was likely centered on “Blue Chip” stocks—companies with a long history of stable earnings and dividend payments. In the modern era, the definition of Blue Chip has expanded to include major tech giants and innovative firms that dominate the digital infrastructure.
Today’s personal finance experts advocate for a similar level of discipline: consistent, long-term investing in low-cost index funds that capture the growth of the entire market. By automating these investments, the modern professional can replicate the “slow and steady” wealth accumulation that characterized the mid-century executive class. The briefcase may have been replaced by a laptop, and the pension by a diversified portfolio, but the principles of fiduciary responsibility to one’s own family remain unchanged.

Lessons in Financial Discipline and Long-Term Wealth Management
Ultimately, Ward Cleaver’s occupation was more than just a job title; it was a testament to a specific financial philosophy. He represented the virtue of professional stability, the power of a single well-managed income, and the importance of long-term planning. While the “Organization Man” era has passed, the lessons of his household’s personal finance remain relevant.
To achieve Cleaver-level security today, one must be their own “Trust Officer.” This involves:
- Fiduciary Oversight: Taking total responsibility for where every dollar is allocated, ensuring that long-term goals (college, retirement, home ownership) are prioritized over short-term consumption.
- Asset Diversification: Moving beyond the single-income model to include side hustles and online income streams that protect against the volatility of the modern job market.
- Disciplined Investing: Emulating the “Blue Chip” mindset by consistently contributing to growth-oriented assets and avoiding high-interest debt that erodes purchasing power.
Ward Cleaver’s occupation served as the foundation for the most iconic family in television history. By understanding the economics behind his role, we can better navigate our own professional journeys, utilizing modern financial tools to build a legacy of stability and prosperity in an ever-changing world.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.