
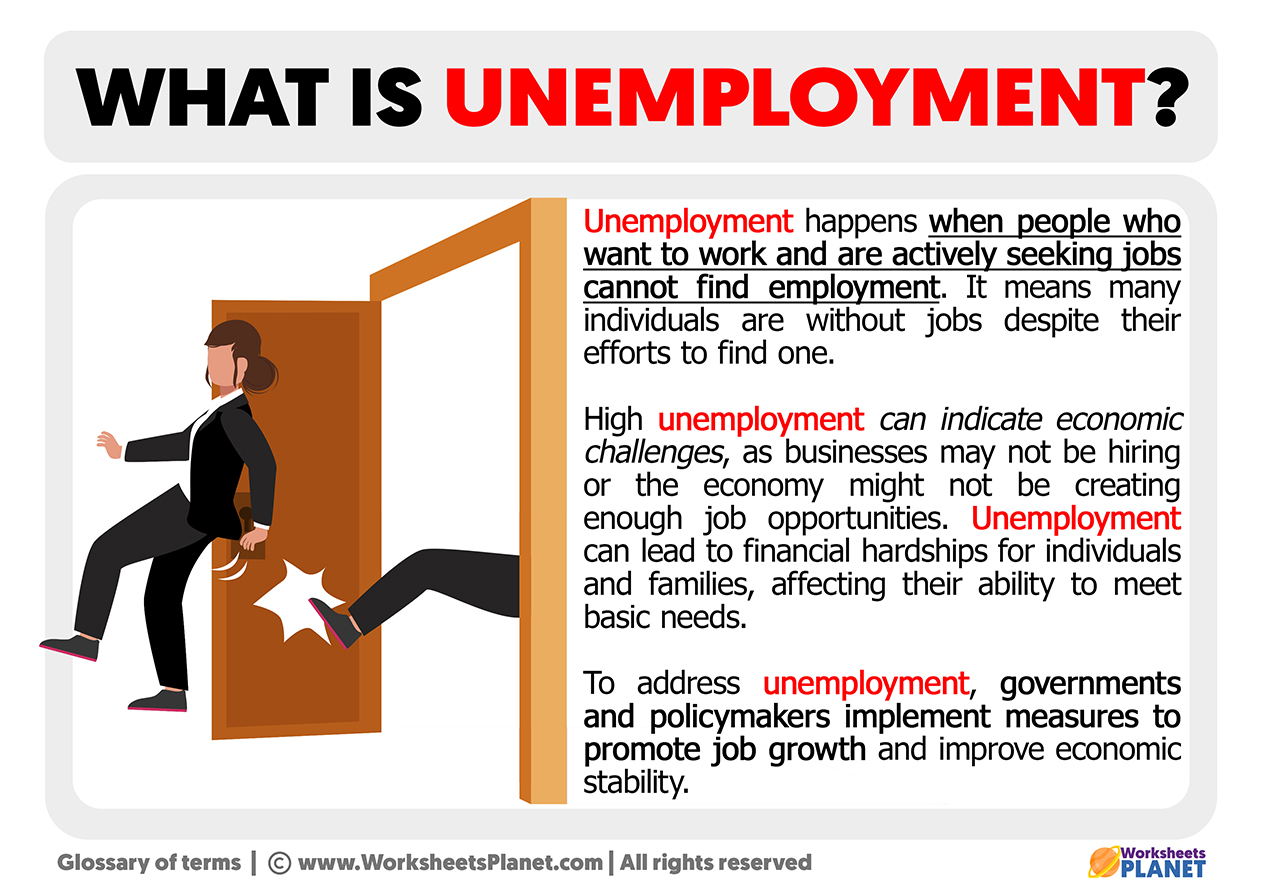
Unemployment is more than just a statistic found in monthly economic reports; it is a fundamental economic indicator that reflects the health of a nation’s labor market and the financial stability of its citizens. At its most basic level, unemployment occurs when individuals who are actively seeking work and are willing to work are unable to find employment. From a “Money” perspective, unemployment is a critical factor that influences everything from consumer spending patterns and interest rates to personal investment strategies and government fiscal policy.
Understanding unemployment requires a deep dive into its various forms, the mechanics of how it is measured, and the profound ripple effects it has on both the macroeconomy and the micro-level of personal finance. For the individual, unemployment is a period of financial risk; for the market, it is a barometer of future growth or recession.
The Diverse Categories of Unemployment
To grasp the financial implications of a shifting labor market, one must first distinguish between the different types of unemployment. Economists generally categorize unemployment into four distinct types, each with its own causes and financial consequences.
Frictional Unemployment: The Natural Transition
Frictional unemployment occurs when workers are between jobs or are entering the labor market for the first time. This is often viewed as a “healthy” form of unemployment because it suggests a dynamic economy where people are seeking better opportunities, higher pay, or roles that better suit their skills. From a personal finance standpoint, frictional unemployment is usually temporary. However, it highlights the importance of liquidity. Individuals in this phase rely heavily on savings or short-term financial instruments to bridge the gap between paychecks.
Structural Unemployment: The Evolution of the Economy
Structural unemployment is more permanent and concerning. It happens when there is a fundamental mismatch between the skills workers possess and the skills required by employers. This is often driven by technological advancements, such as automation or artificial intelligence, or shifts in the global economy. In the “Money” niche, structural unemployment represents a significant investment risk for human capital. When a sector becomes obsolete, the financial value of the skills associated with that sector plummets, requiring significant reinvestment in education and training to regain earning potential.
Cyclical Unemployment: The Business Cycle Impact
Cyclical unemployment is directly tied to the business cycle. When the economy enters a recession, demand for goods and services falls, leading businesses to reduce their workforce to cut costs. This type of unemployment is what most investors watch closely, as it signals a broader economic downturn. During periods of high cyclical unemployment, consumer confidence drops, leading to decreased spending, lower corporate earnings, and often, volatility in the stock market.
Seasonal Unemployment: Periodic Fluctuations
Certain industries, such as agriculture, tourism, and retail, experience predictable changes in labor demand based on the time of year. While seasonal unemployment is expected, it requires rigorous personal budgeting. Workers in these industries must manage their cash flow meticulously during “peak” months to sustain their lifestyle during the “off-peak” months, making financial literacy and disciplined saving essential.
The Macroeconomic Indicators: Measuring Labor Health
For investors and financial analysts, the “unemployment rate” is a primary data point used to forecast market movements. However, the headline number often cited in the media does not tell the full story. To truly understand the financial landscape, one must look at the nuances of labor statistics.
The U-3 vs. U-6 Unemployment Rates
The U-3 rate is the official unemployment rate most commonly reported. It measures the number of people who are jobless and have actively looked for work in the past four weeks. However, the U-6 rate provides a broader financial picture. The U-6 includes the unemployed plus “discouraged workers” (those who have stopped looking) and “underemployed” workers (those working part-time who want full-time work). For a business analyst, a high U-6 rate suggests that the economy is not operating at full capacity, which can lead to stagnant wage growth and lower overall economic output.
The Labor Force Participation Rate
This metric measures the percentage of the working-age population that is either employed or actively seeking employment. A declining participation rate can be a red flag for the long-term financial health of a country. It may indicate an aging population or a workforce that feels alienated by the current economic structure. For personal finance, this trend affects the sustainability of social safety nets, like Social Security, and can lead to higher tax burdens on the remaining workforce.
The Relationship Between Unemployment and Inflation
In the world of finance, the Phillips Curve describes the historical inverse relationship between rates of unemployment and corresponding rates of inflation within an economy. When unemployment is low, wages tend to rise as employers compete for talent. This increased spending power can drive up prices, leading to inflation. Central banks, such as the Federal Reserve, monitor these levels closely to decide whether to raise or lower interest rates. For the average investor, these decisions directly impact the cost of borrowing and the returns on fixed-income investments.
The Financial Impact on Personal Wealth and Recovery
On a personal level, unemployment is one of the most significant financial shocks an individual can face. Navigating this period requires a strategic approach to money management to prevent long-term debt and wealth erosion.
The Importance of the Emergency Fund
The gold standard of personal finance is the emergency fund—typically three to six months of living expenses held in a liquid account. Unemployment transforms this concept from a theoretical “best practice” into a survival necessity. Without this cushion, individuals are often forced to tap into long-term investment accounts, such as 401(k)s or IRAs, which can result in heavy taxes, penalties, and the loss of compound interest growth.
Debt Management and Credit Scores
During periods of joblessness, maintaining a credit score becomes a defensive financial strategy. Missing payments on mortgages, car loans, or credit cards can lead to a downward spiral of high interest rates and reduced financial mobility in the future. Financial experts often recommend “triage budgeting” during unemployment—prioritizing essential payments and contacting creditors early to discuss hardship programs or temporary forbearance.
The “Scarring Effect” on Lifetime Earnings
Economic research suggests that long-term unemployment can have a “scarring effect” on a person’s lifetime earnings. For every month spent out of the workforce, an individual may face lower starting salaries at their next job and a slower trajectory for promotions. This makes “upskilling” or “reskilling” not just a career move, but a critical financial investment. Spending money on a certification or a technical course during unemployment can often yield a much higher return on investment (ROI) than simply waiting for a market recovery.
Modern Trends: The Gig Economy and Automation
The definition of employment and unemployment is shifting as the digital economy evolves. The rise of “side hustles,” the gig economy, and the threat of automation are changing how we quantify being “jobless.”
The Gig Economy as a Financial Buffer
The growth of platforms like Uber, Upwork, and Fiverr has created a new middle ground between full employment and unemployment. Many individuals now use gig work as a form of “self-insurance” against job loss. While this provides immediate cash flow, it presents new financial challenges, such as the lack of employer-sponsored health insurance, 401(k) matching, and the burden of self-employment taxes. For many, “underemployment” in the gig economy is the new face of the unemployment crisis.
Automation and the Value of Human Labor
As AI and robotics continue to integrate into the workforce, the risk of structural unemployment increases. From a business finance perspective, automation is an efficiency gain. However, from a labor perspective, it requires a massive shift in how we value human input. Investors are increasingly looking at “future-proof” sectors—those that require high-level emotional intelligence, complex problem solving, and creative strategy—as the safest bets for long-term income stability.

Strategic Financial Planning for Employment Gaps
The reality of the modern economy is that most workers will face a period of unemployment at least once in their careers. Strategic financial planning can turn a potential disaster into a manageable transition.
- Diversifying Income Streams: The most resilient financial profiles are those that do not rely on a single paycheck. This might include dividend-paying stocks, rental income, or a secondary online business.
- Tax Planning: Unemployment benefits are generally considered taxable income. Many people are surprised by a tax bill at the end of the year because they did not have taxes withheld from their government checks.
- Reviewing Asset Allocation: If the broader economy is signaling a rise in cyclical unemployment, it may be a sign for investors to shift toward more defensive assets, such as consumer staples or healthcare stocks, which tend to perform better during downturns.
In conclusion, unemployment is a multifaceted concept that serves as a pulse for the economy and a crucible for personal finance. By understanding the types of unemployment and the macro-indicators that drive them, individuals can better position their portfolios and their careers to withstand economic volatility. Whether it is through building a robust emergency fund or staying ahead of technological trends, the goal remains the same: achieving financial security in an ever-changing labor market.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.