
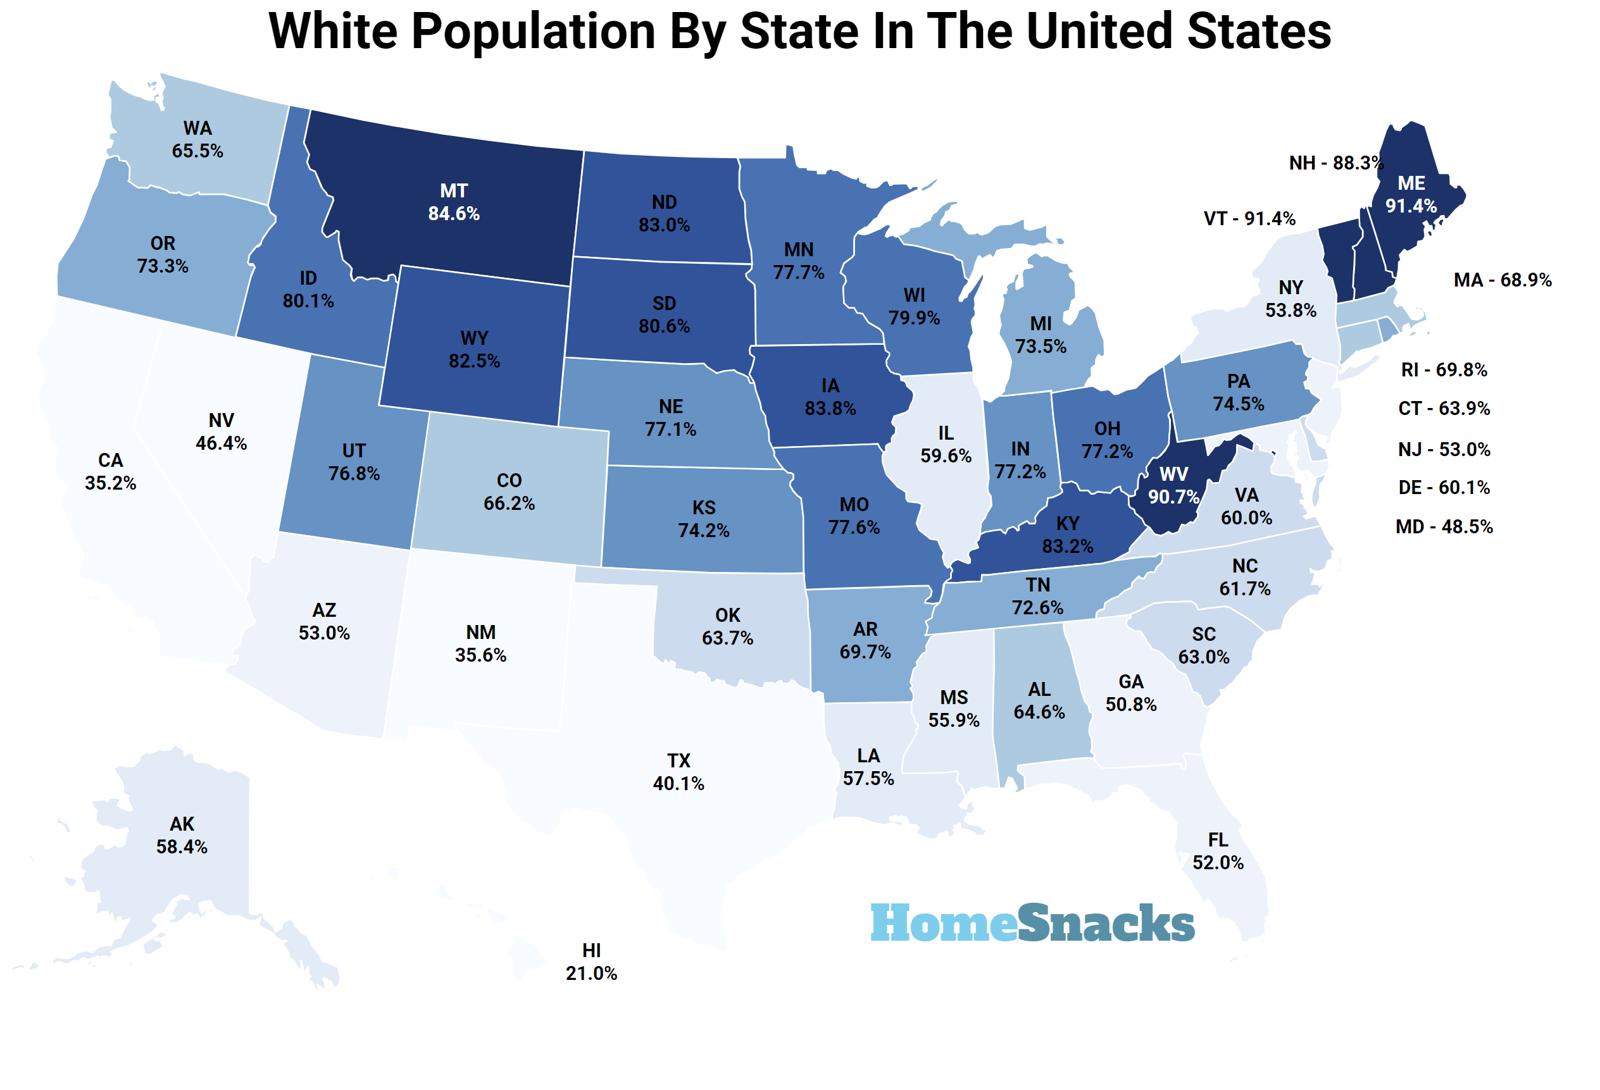
When investors and financial analysts look at the map of the United States, they often view it through the lens of growth potential, tax incentives, and labor market trends. However, one of the most significant—though often understated—factors in regional economic stability is demographic composition. If one asks, “What is the whitest state in the US?” the answer is statistically Maine, closely followed by Vermont and West Virginia. From a financial perspective, these states represent a unique subset of the American economy.
In the realm of money, personal finance, and real estate investing, high levels of demographic homogeneity offer specific predictors for market behavior. Understanding the financial DNA of these regions allows investors to capitalize on stability while navigating the challenges of aging workforces and shifting consumer demands.

The Intersection of Demographics and Regional Real Estate Investing
Real estate is rarely just about bricks and mortar; it is a play on human movement and population stability. In states like Maine and Vermont, where the population remains over 90% white, the real estate market operates with a distinct cadence compared to the volatile, rapidly diversifying sunbelt states.
Why Homogeneity Matters to Property Investors
For a real estate investor, a demographic that remains consistent over decades suggests a lower risk of “neighborhood transition” volatility, but it also signals a different type of growth. In states with high homogeneity, property values tend to be driven by “lifestyle migration” rather than industrial booms. During the post-2020 era, we saw a massive influx of “Zoom town” investors into Northern New England. These investors were betting on the stability and safety associated with these demographics, driving up prices in markets that had previously seen decades of stagnation.
Case Study: Economic Stability in Vermont and Maine
Vermont and Maine serve as fascinating case studies for capital preservation. Because these states have high percentages of homeownership among their majority population, the housing markets are often less speculative. For the personal finance enthusiast looking for a “safe haven” for equity, these states offer a buffer against the extreme troughs of the national housing cycle. However, the lack of demographic churn can lead to a supply-demand imbalance; as younger, more diverse populations do not migrate in at the same rate, the secondary market (rental properties) may face a ceiling in terms of high-yield growth compared to more metropolitan hubs.
Market Saturation and Consumer Spending Patterns in Single-Demographic Regions
From a business finance perspective, the demographic makeup of a state dictates the “Consumer Basket.” When a state is statistically the “whitest,” its spending patterns often skew toward specific sectors: healthcare for an aging population, home improvement, and outdoor recreation.
Tailoring Personal Finance Products to Local Needs
Financial advisors operating in Maine or West Virginia must approach wealth management differently than those in California or Texas. In more homogeneous, rural-leaning states, there is often a higher concentration of “trapped wealth”—capital tied up in land, family businesses, or traditional pensions. For the finance professional, the opportunity lies in liquidation strategies and estate planning. The marketing of financial products here isn’t about “getting rich quick” through high-risk tech stocks; it is about wealth preservation and generational transfer within a stable social framework.
The Impact of Aging Populations on State Revenue
There is a direct financial correlation between a state’s demographic homogeneity and its fiscal health regarding social services. In the “whitest” states, the median age is often significantly higher than the national average. This creates a “silver economy.” While this provides a steady stream of revenue for healthcare-related businesses and specialized REITs (Real Estate Investment Trusts) focusing on senior living, it places a strain on state budgets. Investors must keep a close eye on the tax trajectories of these states; as the tax base ages, the financial burden for infrastructure often shifts toward property taxes, which can eat into the net operating income of real estate portfolios.
The Economic Implications of Limited Diversity in Business Growth
While homogeneity can offer social and real estate stability, it presents a complex challenge for corporate strategy and venture capital. Modern business finance thrives on the “Innovation Quotient,” which research consistently links to diverse perspectives and international connectivity.
Labor Markets and the Innovation Gap
States that lack demographic diversity often struggle with “brain drain”—the exodus of young talent to more diverse, high-growth urban centers. From a business finance standpoint, this creates a tight labor market. If you are looking to scale a tech startup or a high-output manufacturing firm, the “whitest” states may present a hurdle in recruitment. The cost of labor can paradoxically be higher in these regions not because of high cost of living, but because of a scarcity of specialized skills. Investors looking at these regions should focus on companies that are leveraging automation to bypass the demographic constraints of the local workforce.
Strategies for Scaling Businesses in Homogeneous Markets
For entrepreneurs, the key to financial success in these regions is niche dominance. In a market where the consumer base is culturally and demographically uniform, a brand can achieve high levels of loyalty more quickly than in a fragmented urban market. The “Buy Local” movement is incredibly potent in states like Maine and Vermont. Businesses that successfully integrate into the local identity can command premium pricing, leading to higher profit margins. For a side hustler or a small business owner, the strategy is not to appeal to everyone, but to become an indispensable part of the local community’s economic fabric.
Financial Planning for Relocation: Moving to “High-Stability” States
For individuals looking at their personal balance sheets, the decision to move to one of the most homogeneous states is often a play on the “Cost of Living vs. Quality of Life” equation. While these states are often perceived as more affordable, the financial reality is nuanced.
Balancing Tax Incentives and Job Opportunity
When evaluating a move to a state like West Virginia (which has seen significant demographic focus in recent years), one must look at the “Net Benefit.” West Virginia has introduced aggressive financial incentives, such as “Ascent WV,” which pays remote workers to relocate to the state. This is a direct attempt to use cash incentives to balance out the lack of organic demographic growth. For a remote worker, the arbitrage of earning a “Silicon Valley salary” while living in a state with low property costs and high homogeneity can result in a massive increase in personal net worth over a five-year period.
Long-term Wealth Accumulation in Northern New England
In contrast, Maine and Vermont have higher tax burdens compared to the national average. Here, the “Money” play is less about immediate cash flow and more about long-term asset appreciation and lifestyle equity. For the personal finance strategist, the goal in these states is to maximize tax-advantaged accounts (like 401ks and IRAs) to offset high state income taxes, while simultaneously investing in physical land. Historically, land in these states has acted as a “hard asset” that holds value even during inflationary periods, making it a cornerstone of a conservative investment portfolio.
Conclusion: The Financial Forecast for the Most Homogeneous States
Answering the question “What is the whitest state in the US?” provides more than just a census statistic; it provides a roadmap for a specific type of economic inquiry. For the investor, the “whitest” states represent a portfolio of “Low Volatility, Steady Growth” assets.
While these regions may lack the explosive, unicorn-style growth of high-diversity tech hubs, they offer something increasingly rare in the global economy: predictability. Whether it is the stability of the Maine real estate market, the “silver economy” opportunities in Vermont, or the relocation incentives in West Virginia, there is significant money to be made for those who understand how to navigate the unique financial currents of America’s most demographically consistent states. By focusing on wealth preservation, niche market dominance, and strategic relocation, individuals and businesses can thrive in these unique economic micro-climates.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.