
When a patient receives a diagnosis of Stage 3 Chronic Kidney Disease (CKD), the immediate focus is rightfully on clinical intervention—managing blood pressure, monitoring GFR levels, and adjusting diet. However, there is a secondary, often overlooked “treatment” that is equally vital for the patient’s long-term well-being: financial strategy. Stage 3 is a critical juncture not just biologically, but economically. It represents a “yellow light” period where proactive financial planning can prevent the catastrophic “Stage 5” fiscal crisis that often accompanies end-stage renal failure.
To treat the financial implications of Stage 3 kidney disease is to engage in a rigorous process of asset protection, insurance optimization, and cash-flow management. This article explores the professional financial framework required to navigate the costs of chronic illness, ensuring that the diagnosis does not derail a lifetime of wealth building.
Understanding the “Financial Staging” of Chronic Illness
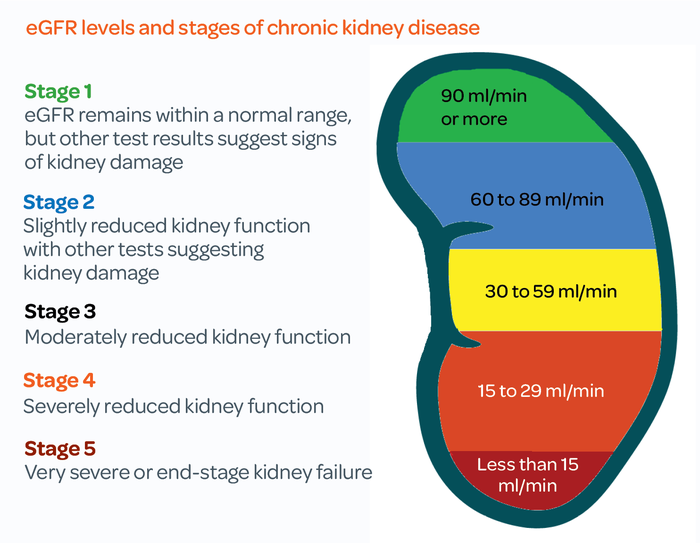
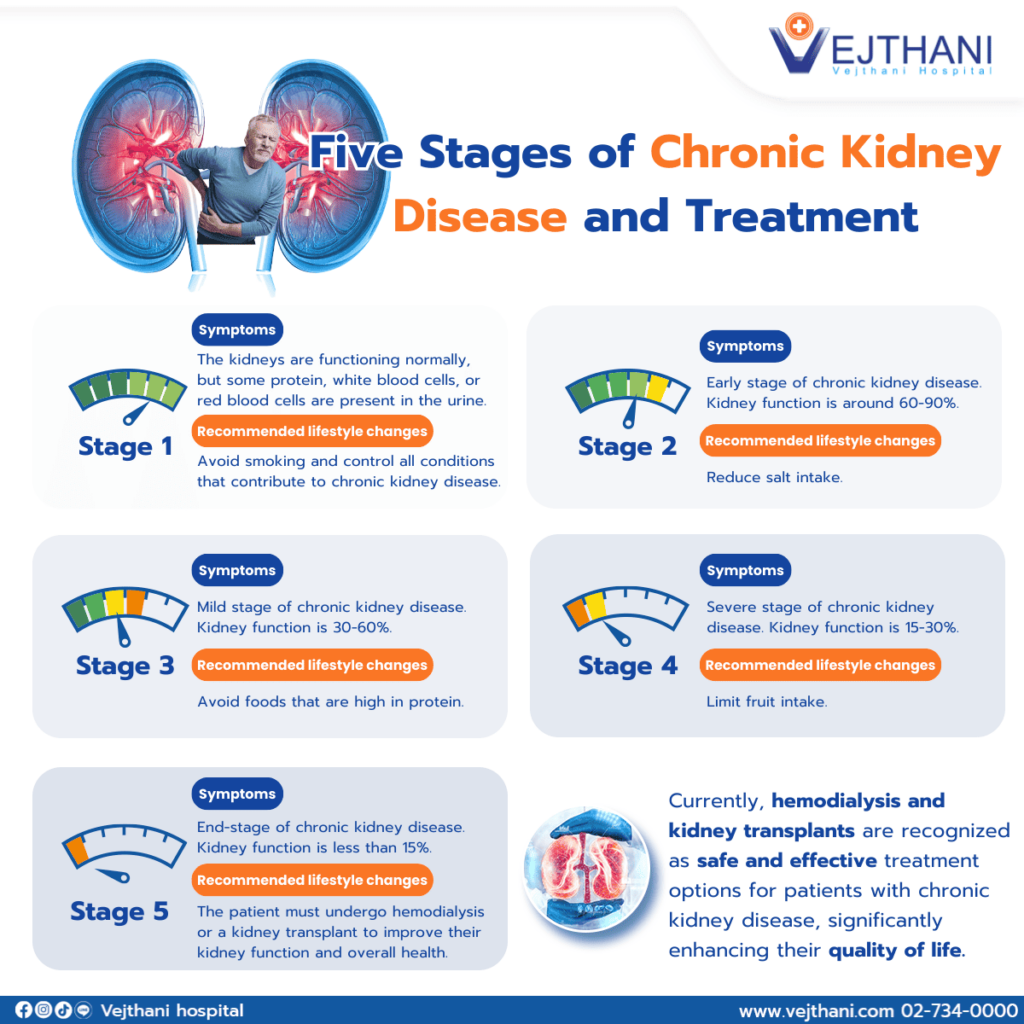
In the medical world, Stage 3 CKD is defined by a moderate decrease in kidney function. In the financial world, Stage 3 is the “Intervention Zone.” It is the period before the high-cost requirements of dialysis or transplantation (Stage 5) begin, yet it is where the cumulative costs of specialist co-pays, medications, and potential loss of productivity start to mount.
Direct Medical Costs vs. Indirect Income Loss
The financial treatment of CKD begins with a bifurcated analysis of expenses. Direct costs are the quantifiable line items: nephrologist consultations, laboratory tests, and pharmacological interventions like ACE inhibitors or statins. While insurance may cover a significant portion, the out-of-pocket “leakage” can be substantial.
Indirect costs are more insidious. They include the opportunity cost of time spent at appointments and the “productivity tax” of fatigue, which may limit a patient’s ability to pursue overtime, side hustles, or promotions. Treating these financial symptoms requires a shift in how one views their human capital. At Stage 3, the goal is to optimize one’s work environment—perhaps through a transition to remote work or more flexible hours—to preserve earning capacity for as long as possible.
The Threshold of Stage 3: Why it’s the Critical Financial Intervention Point
Stage 3 is unique because the patient is typically still fully integrated into the workforce. This provides a window of opportunity that does not exist in later stages. This is the time to lock in certain financial protections, such as disability insurance or life insurance riders, before the condition progresses to a point where one becomes uninsurable or the premiums become prohibitive. A “financial treatment plan” initiated at Stage 3 can save hundreds of thousands of dollars over a decade compared to a reactive approach at Stage 4 or 5.
Strategic Budgeting: The First Line of Financial Treatment
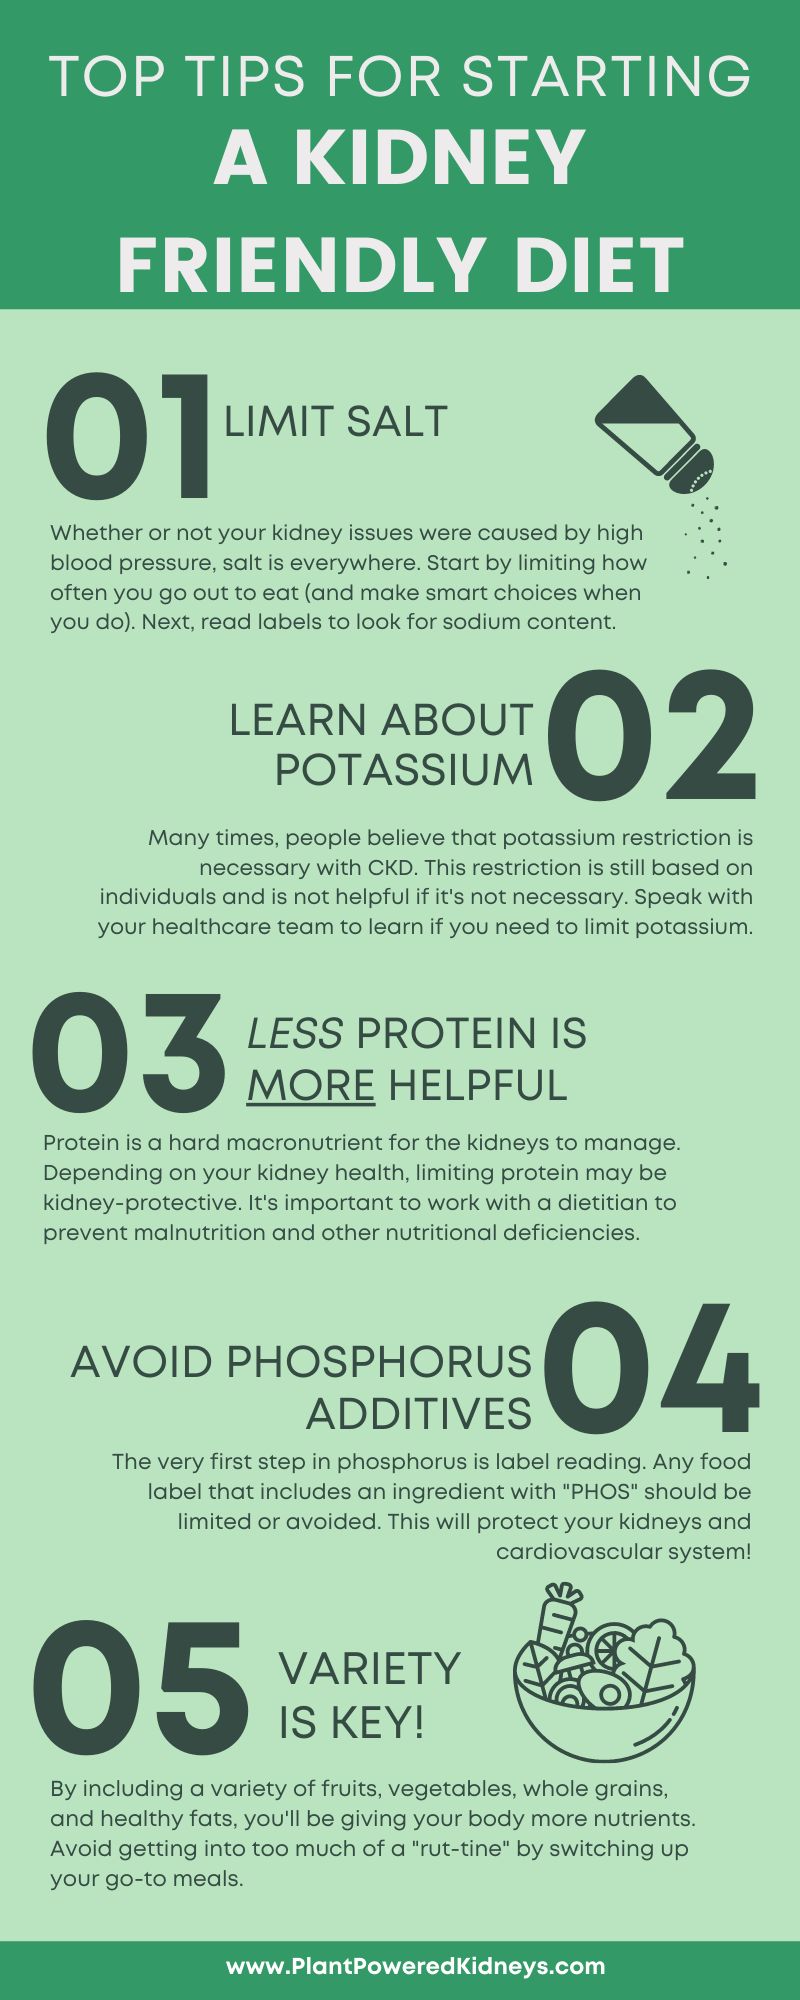
Just as a renal diet requires tracking sodium and potassium, the financial treatment of CKD requires a meticulous tracking of capital. Budgeting for a chronic illness is not about austerity; it is about the strategic allocation of resources to ensure medical compliance without sacrificing financial stability.
Auditing Insurance Coverage and Out-of-Pocket Maximums
The most effective “medication” for high healthcare costs is a robust insurance policy. During the annual open enrollment period, a Stage 3 patient must perform a cold-eyed analysis of their plan options. A plan with a lower monthly premium but a high deductible may be a poor choice for someone requiring frequent blood work and specialist visits.
Professional financial treatment involves calculating the “Total Cost of Ownership” for the health plan. This includes the annual premium plus the Out-of-Pocket (OOP) maximum. For many Stage 3 patients, selecting a “Platinum” or “Gold” tier plan—even with a higher monthly cost—ends up being the cheaper route because they are virtually guaranteed to hit their OOP maximum early in the year. Once that ceiling is reached, the “treatment” for the rest of the year is essentially subsidized by the insurer.
Leveraging Health Savings Accounts (HSAs) and FSAs
For those in the early phases of Stage 3 who are still healthy enough to manage with lower-cost interventions, the Health Savings Account (HSA) is a powerful financial tool. It offers a triple tax advantage: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free.
Think of the HSA as a dedicated “Kidney Health Endowment.” By maxing out contributions during Stage 3, a patient can build a significant war chest that can be used to pay for a future transplant or expensive immunosuppressant drugs in the years to come. If the employer offers a Flexible Spending Account (FSA), this should be used for predictable annual costs like prescriptions and co-pays, effectively providing a 20–30% discount on those services by using pre-tax dollars.
Investment Realignment and Asset Protection
A chronic diagnosis necessitates a re-evaluation of one’s investment portfolio. The “treatment” here involves balancing the need for long-term growth with the sudden necessity for increased liquidity.
Adjusting Risk Tolerance in the Face of Healthcare Expenses
Traditional financial advice suggests a risk profile based on age. However, a Stage 3 CKD diagnosis introduces a “health-adjusted risk profile.” If a patient anticipates a significant medical expense (such as a surgery) within the next 24 to 36 months, keeping that money in a volatile stock market is risky.
Financial treatment for the Stage 3 investor often involves creating a “Medical Tier” in their portfolio—a bucket of highly liquid, low-volatility assets (like high-yield savings accounts or short-term T-bills) that can cover one to two years of maximum out-of-pocket medical expenses. This prevents the patient from being forced to sell stocks during a market downturn to pay for an emergency medical bill.
Long-term Disability Insurance and Social Security Safeguards
One of the most devastating financial side effects of advancing kidney disease is the loss of the ability to work. In Stage 3, while the patient is still likely working, they must review their Long-Term Disability (LTD) coverage.
Many employer-provided LTD plans only cover 50–60% of base salary, which may not be enough to cover both living expenses and increased medical costs. Supplementing this with a private, “own-occupation” disability policy is a key component of financial treatment. Furthermore, understanding the Social Security Disability Insurance (SSDI) “Blue Book” requirements for chronic kidney disease is essential. While Stage 3 rarely qualifies for SSDI on its own, knowing the specific laboratory thresholds required for a future claim allows the patient to keep the precise medical records necessary for an eventual application.
Building a “Health-First” Financial Legacy
The final stage of financial treatment involves looking beyond the patient’s own needs to the security of their family and the efficiency of their estate. Chronic illness management is a marathon, and the financial structures must be built to last.
Estate Planning and Special Needs Trusts
If the diagnosis progresses, there may come a time when the patient needs to qualify for government assistance programs like Medicaid, which have strict asset limits. A “financial treatment plan” includes consulting with an elder law or disability attorney to discuss “Medicaid Spend-down” strategies or the creation of irrevocable trusts.
For those with dependents, updating a will and establishing a durable power of attorney for both finances and healthcare is non-negotiable. This ensures that if the disease causes a sudden health crisis, a trusted individual can manage the patient’s business affairs and ensure that bills continue to be paid and investments managed without interruption.
Tax Strategies for High Medical Deductions
The silver lining of high medical costs is their tax-deductibility. According to the IRS, medical expenses are deductible to the extent they exceed 7.5% of Adjusted Gross Income (AGI).
A sophisticated financial treatment for Stage 3 involves “bunching” medical expenses. For example, if a patient needs a specific diagnostic procedure, dental work, and new medical equipment, they might aim to schedule all of them in a single calendar year. By concentrating these costs, they are more likely to surpass the 7.5% threshold and the standard deduction, resulting in a significant tax refund that can be reinvested back into their “Medical Tier” savings.
Conclusion: The ROI of Financial Vigilance
The treatment for Stage 3 kidney disease is often discussed in terms of pills and procedures, but for the modern patient, it must also be discussed in terms of portfolios and premiums. The economic toll of CKD can be as debilitating as the physical symptoms if left unmanaged.
By treating the financial health of the household with the same rigor that a nephrologist treats the kidneys—through careful monitoring, strategic intervention, and long-term planning—patients can maintain their quality of life and financial independence. Stage 3 is not just a medical warning; it is a financial call to action. With a professional strategy in place, a patient can face the future not with the fear of insolvency, but with the confidence of a well-funded plan.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.