
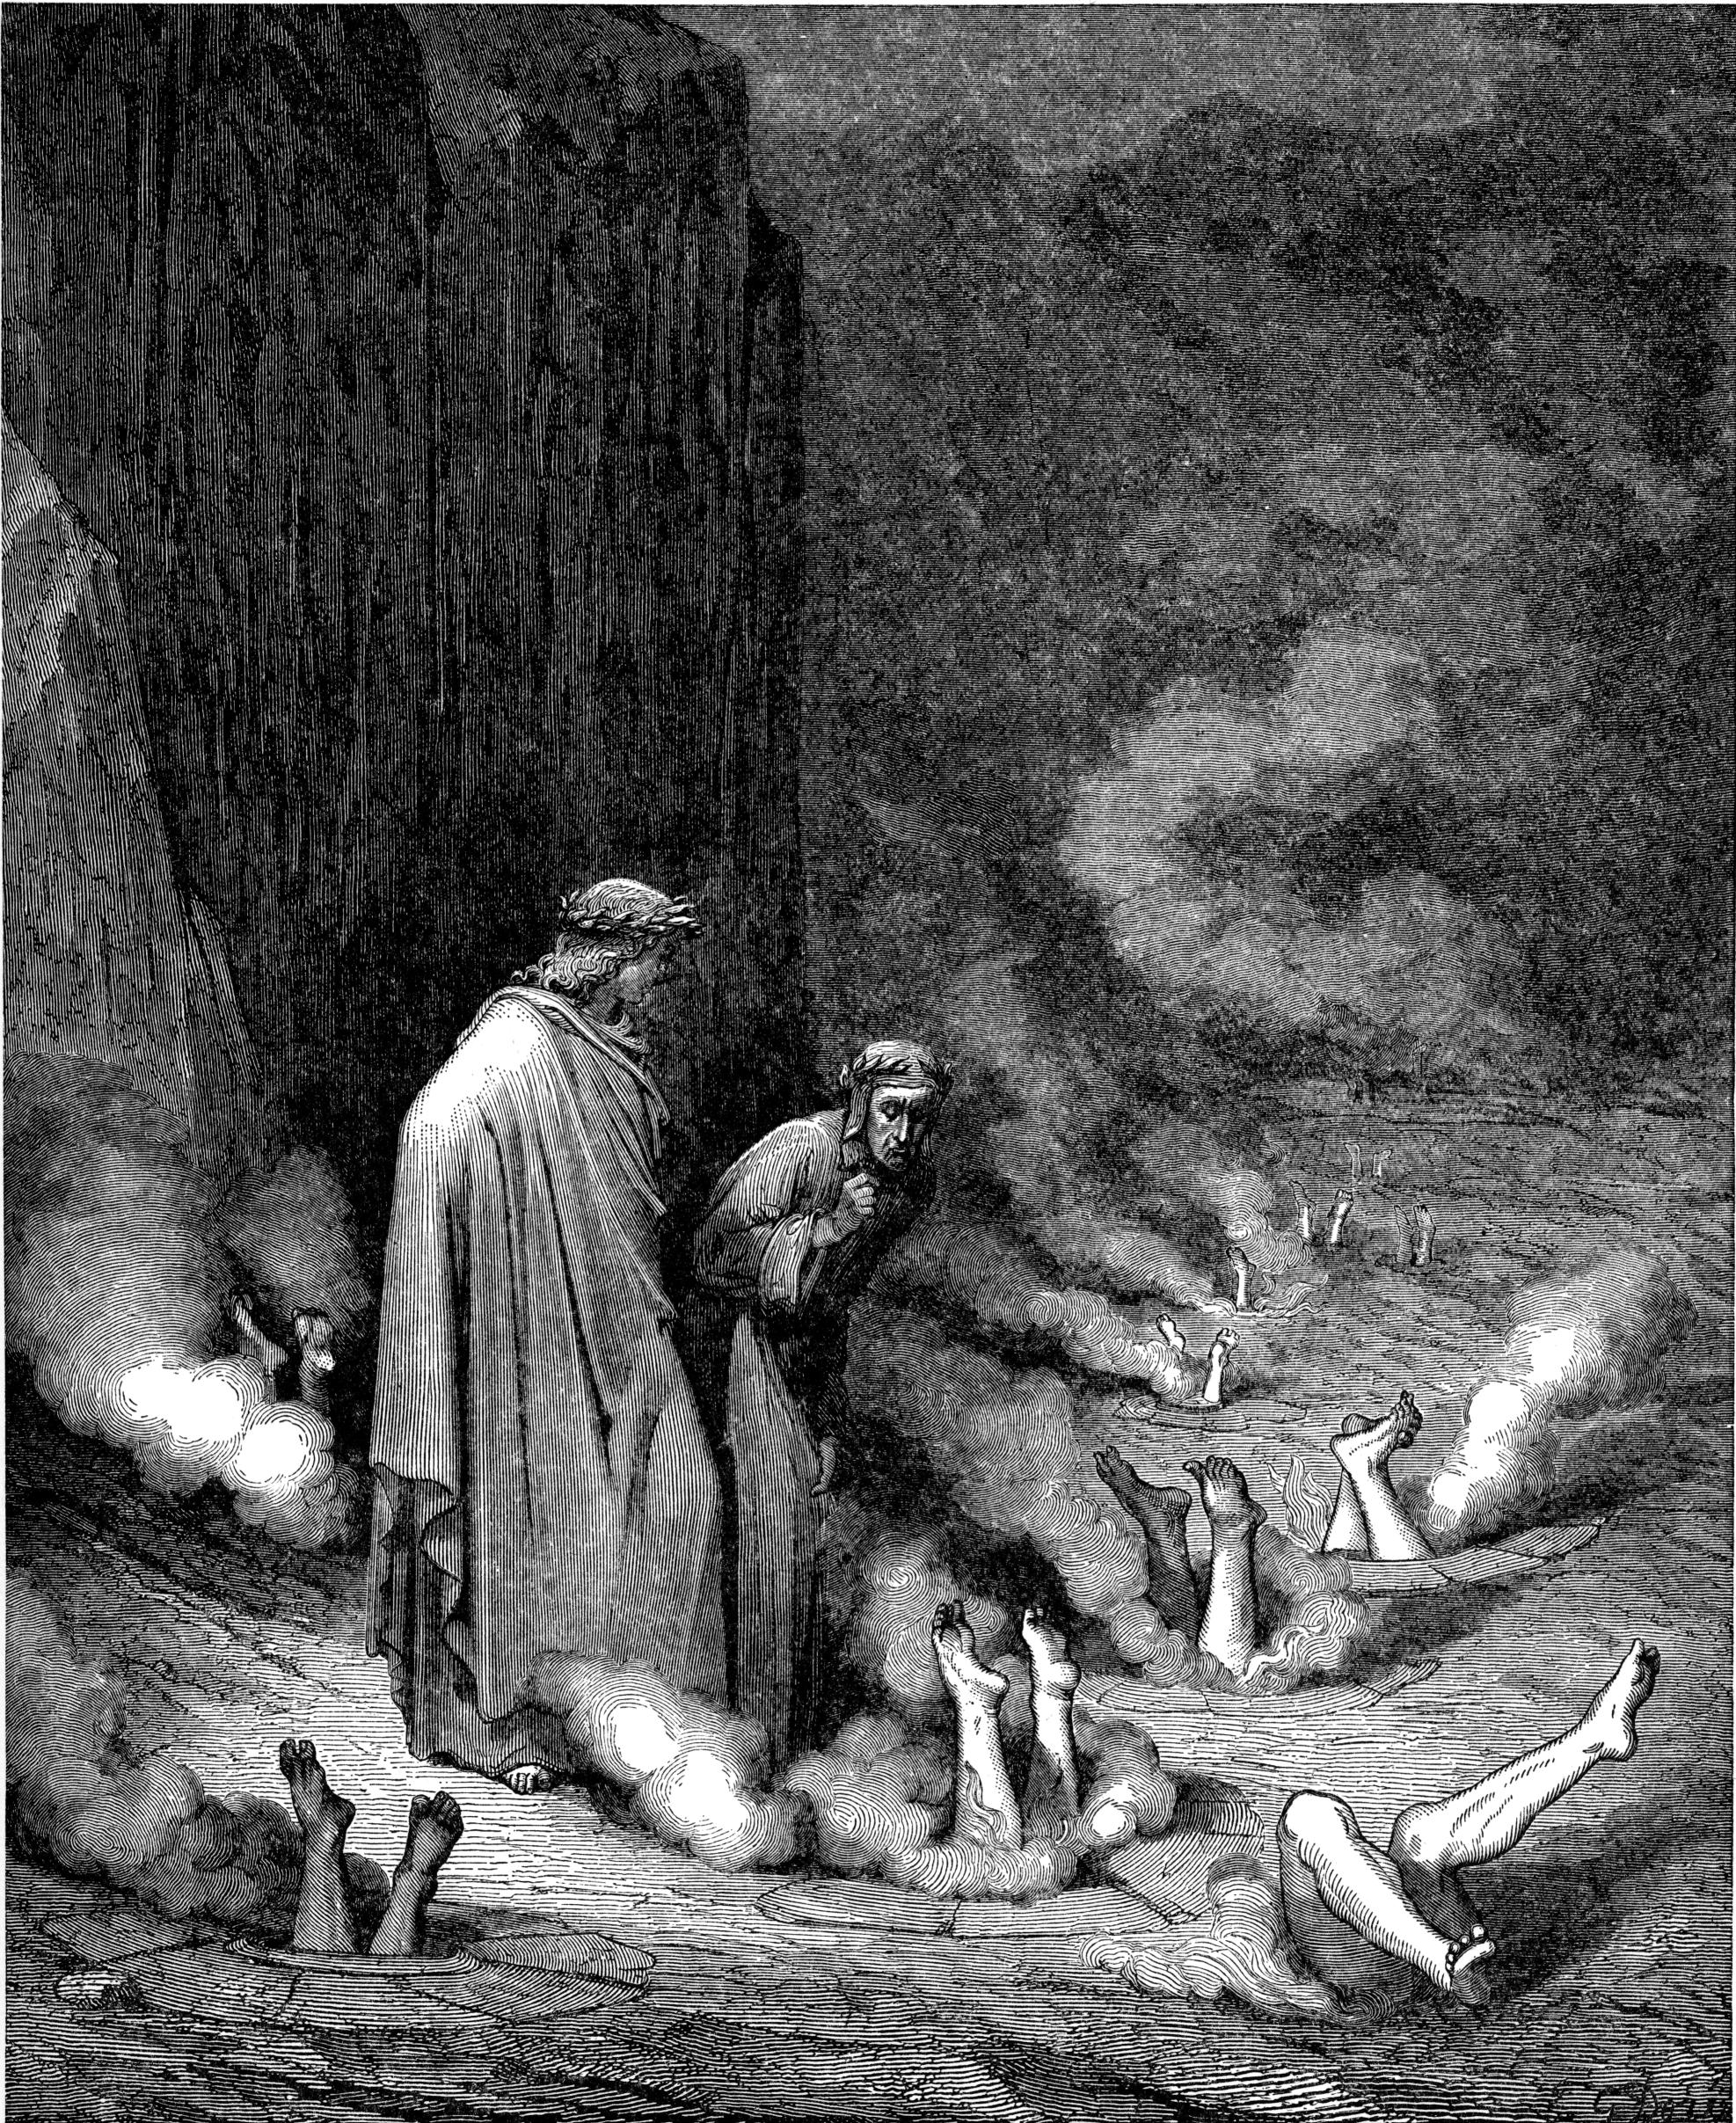
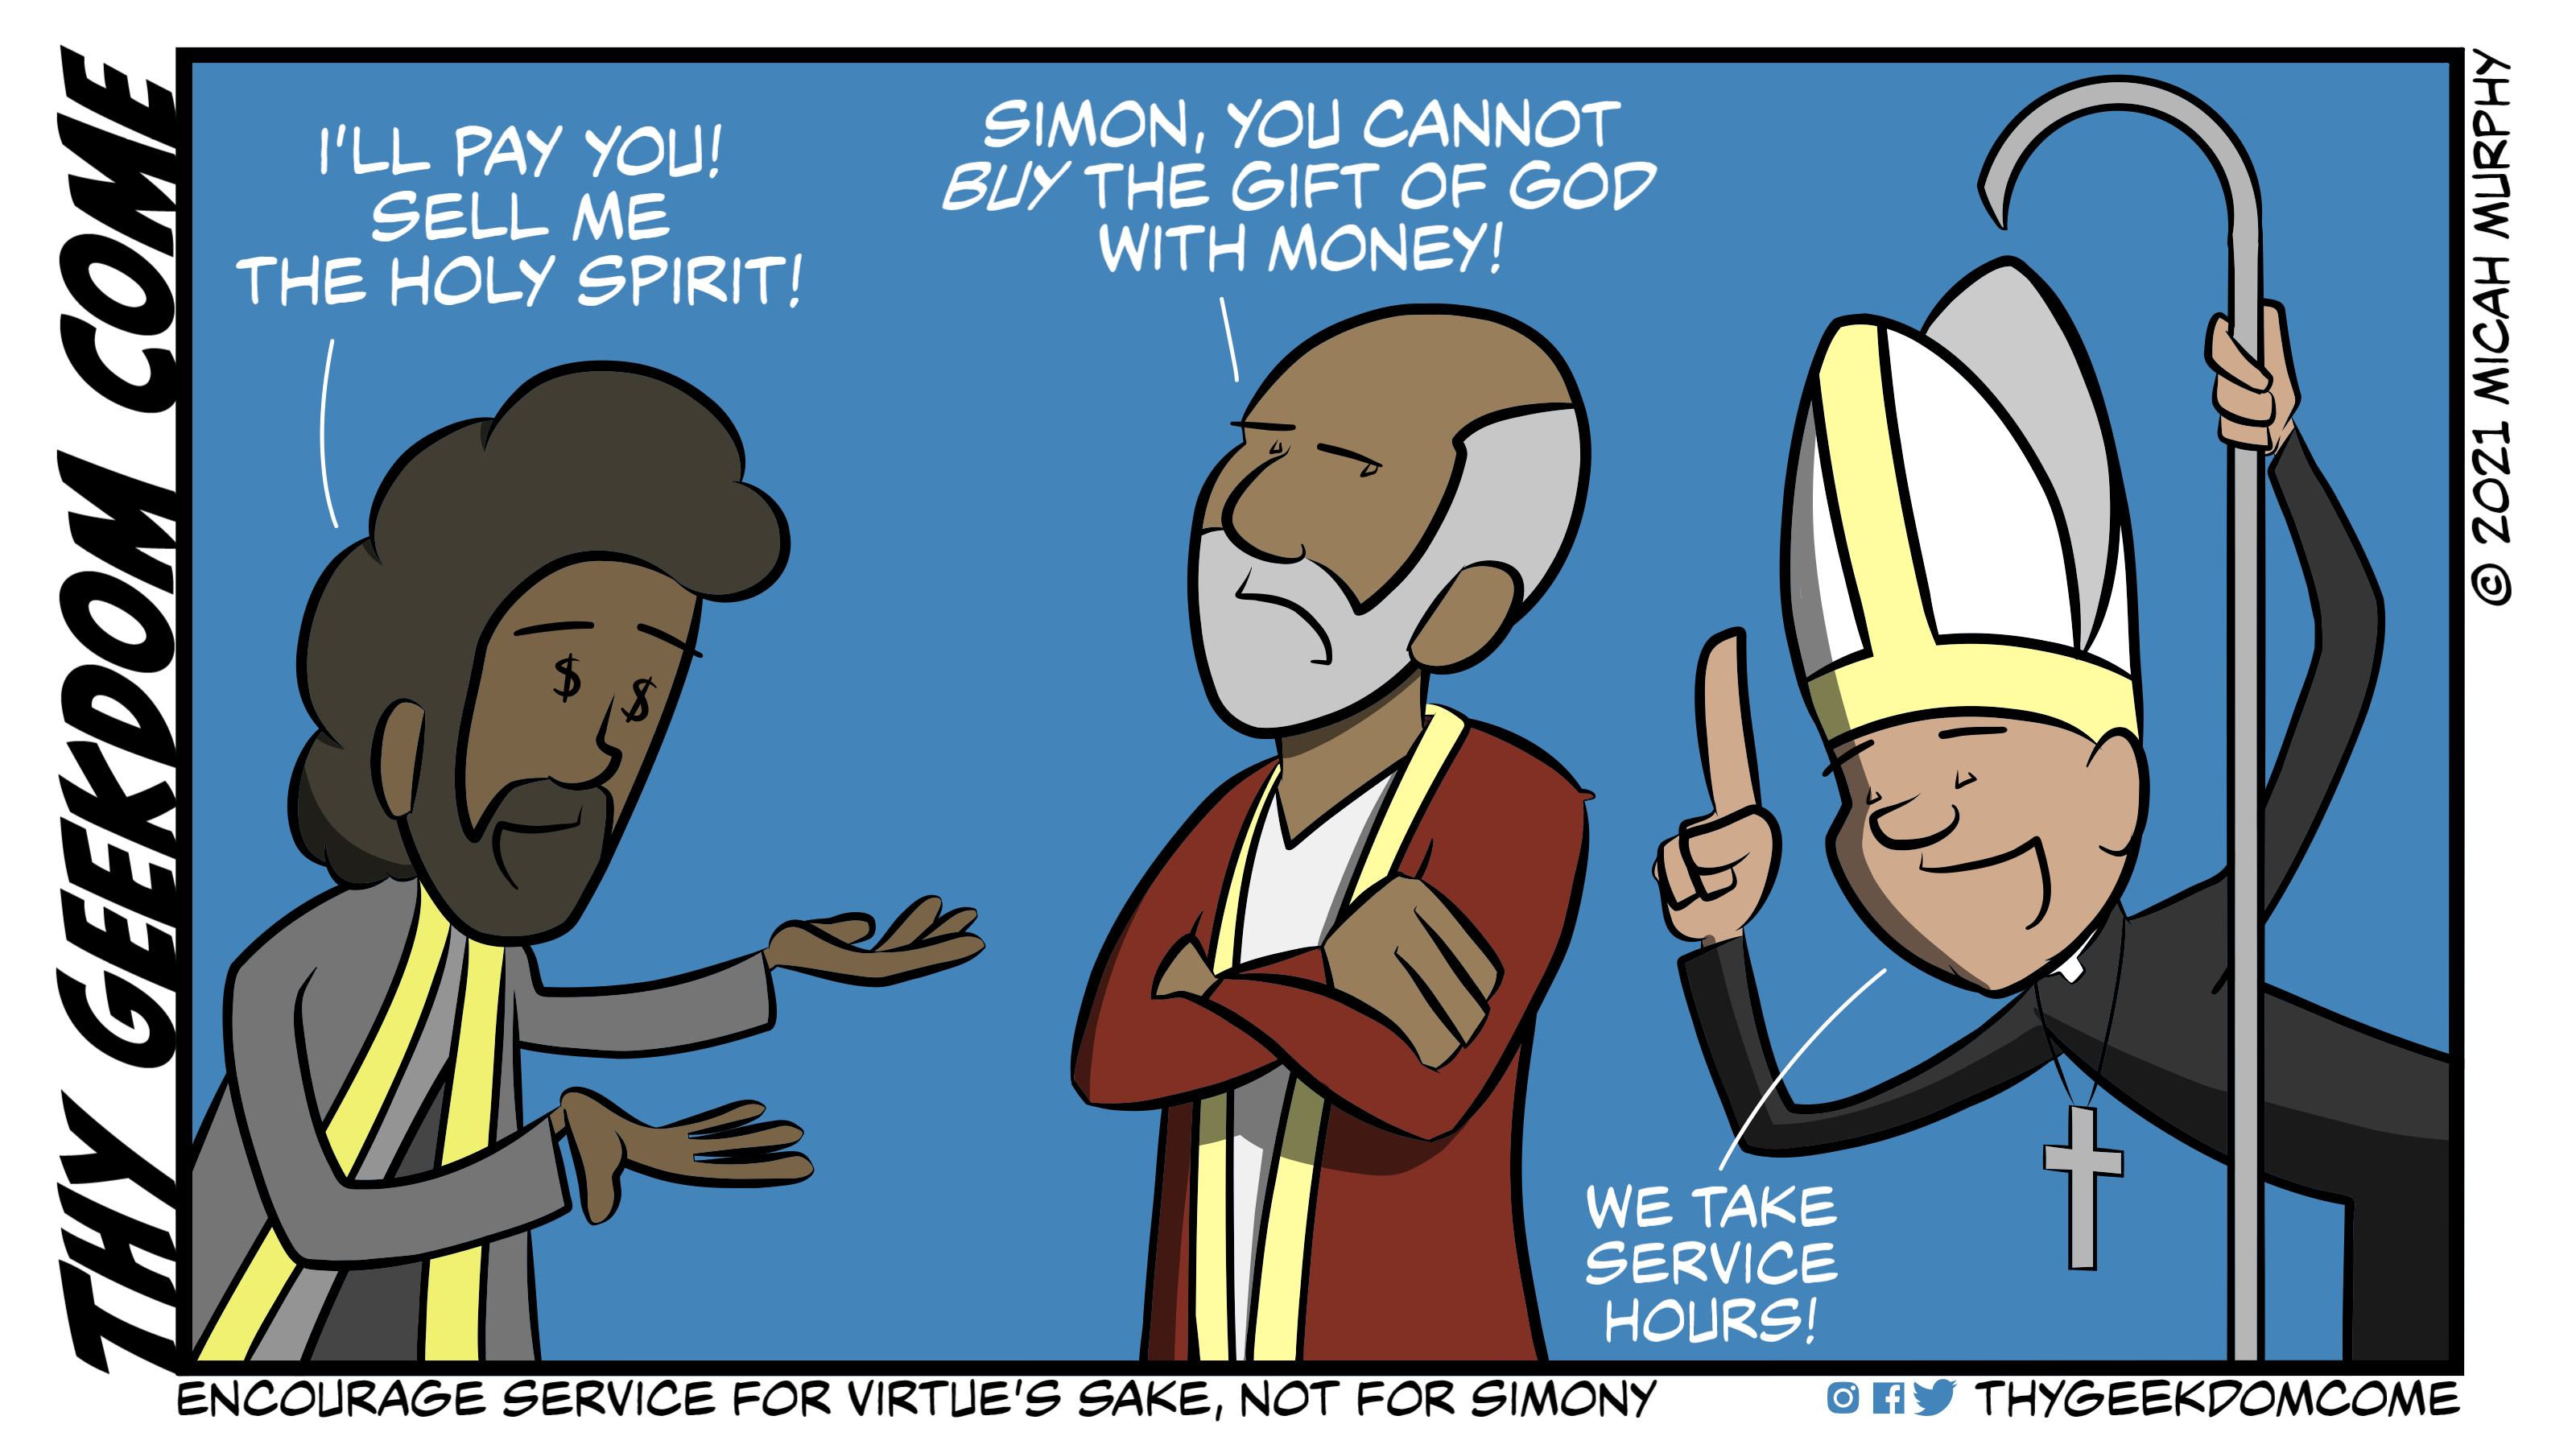
While the term “simony” finds its roots in medieval ecclesiastical history—referring to the act of buying or selling church offices or spiritual privileges—it has evolved into a powerful metaphor for the modern financial world. In the context of 21st-century money management, business ethics, and corporate governance, the “sin of simony” describes the corruption of a system through the commodification of things that should never be for sale: influence, fiduciary duty, and fair market access.
In today’s economy, where capital is often used not just to build value but to purchase unearned advantages, understanding the mechanics of this financial simony is essential for any investor or business leader. Whether it takes the form of “pay-to-play” schemes in pension fund management or the buying of political influence to skew market regulations, simony remains a pervasive threat to the integrity of global finance.

The Modern Financial Definition of Simony
In its original context, simony was considered a grave offense because it attempted to put a price tag on the divine. In the world of finance, we replace “the divine” with “the fiduciary.” A fiduciary duty is the highest standard of care at law; it is the sacred trust between a money manager and their client, or a board of directors and their shareholders. When this trust is sold for a kickback, a referral fee, or a political contribution, we are witnessing the modern version of simony.
The Commodification of Trust
Trust is the invisible infrastructure of the financial markets. When you deposit money into a brokerage account or invest in a mutual fund, you are operating under the assumption that the gatekeepers of that capital are acting in your best interest. Financial simony occurs when that access is sold to the highest bidder. This might look like a “preferred” investment list where companies pay the brokerage to be featured, rather than being selected based on performance metrics. When the selection criteria shift from “merit” to “membership fee,” the spiritual core of the financial contract is broken.
Pay-to-Play: The Institutional Sin
In the institutional investment world, simony often manifests as “pay-to-play.” This occurs when investment advisors or money managers make political contributions to government officials in exchange for being awarded the contract to manage public pension funds. This is not merely a political issue; it is a financial one. When a manager is chosen because of their checkbook rather than their track record, the retirees who depend on those funds are the ones who pay the price through lower returns and higher risk.
Corporate Simony: The High Cost of Buying Influence
Corporate governance is designed to ensure that a company is run for the benefit of its stakeholders. However, the “sin” of simony often creeps into the boardroom, where influence is traded like a commodity. This can lead to a misalignment of incentives that eventually erodes the brand’s value and the company’s financial health.
The Sale of Board Seats and Executive Perks
While board seats are technically appointed based on expertise and oversight capabilities, there is often a “simoniacal” element to how these positions are distributed. When seats are given to individuals primarily because of their ability to provide “access” to regulatory bodies or because of reciprocal favors between CEOs, the oversight function of the board is compromised. Instead of a meritocracy, the corporation becomes a network of traded favors. This lack of independent oversight is often the precursor to major financial scandals, as seen in the collapses of companies like Enron or Wirecard.
Lobbying as Market Arbitrage
There is a fine line between legitimate corporate advocacy and the purchase of market advantages. When a corporation spends millions to secure a regulatory loophole that prevents competition, they are engaging in a form of financial simony. They are not winning in the marketplace through innovation or efficiency; they are buying a “spiritual” privilege—the right to exist outside the normal rules of the market. This creates a “moat” that is not built on brand strength or product quality, but on the corruption of the legislative process. For the investor, this represents a significant risk, as these advantages are fragile and dependent on political winds rather than business fundamentals.
Wealth Management and the Ethics of Access
For the individual investor, simony often appears in the “velvet rope” economy of wealth management. There is a persistent myth in finance that the best returns are hidden behind high-entry barriers—exclusive funds, private equity deals, and “invite-only” investment vehicles. While some of these require sophistication, many are simply vehicles for charging higher fees for the same market exposure.
The Moral Hazard of Paid Entry
When an investor pays an “access fee” to get into a fund, they are often participating in a system where the manager’s primary incentive is to collect assets under management (AUM) rather than to generate alpha. This is the simony of the retail world: selling the “blessing” of exclusivity. Historically, many of these exclusive vehicles have underperformed simple, low-cost index funds after accounting for their exorbitant fees. The “sin” here is the deception—the promise that paying more for “special” access will result in a superior outcome, when in fact it only enriches the gatekeeper.
The “Clubby” Nature of Alternative Investments
The world of private equity and venture capital often operates on a network of personal connections. While networking is a legitimate part of business, it becomes simoniacal when it excludes qualified capital in favor of “connected” capital. This creates a bubble of groupthink where investments are made based on social standing rather than rigorous financial analysis. For the broader economy, this means capital is misallocated, flowing toward the well-connected rather than the most innovative or efficient businesses.
Protecting Your Capital from Ethical Bankruptcy
How does an investor or business owner navigate a world where the “sin of simony” is so prevalent? The answer lies in radical transparency and a return to fundamental value. Ethical investing is not just a moral choice; it is a defensive strategy against the volatility that corruption invariably creates.
Transparency as the Ultimate Antidote
The best defense against pay-to-play and influence peddling is sunshine. Investors should prioritize firms that are transparent about their fee structures, their political contributions, and their board selection processes. A company that has nothing to hide is less likely to be hiding the “rot” of simoniacal practices. When evaluating an investment, ask: “Is this company winning because they are the best, or because they have the best connections?” If the answer is the latter, your capital is at risk the moment those connections fail.
The Long-Term ROI of Integrity
There is a growing body of evidence suggesting that companies with high scores in corporate governance (the “G” in ESG) tend to outperform their peers over the long term. This is because they avoid the “hidden taxes” of corruption. They don’t have to worry about the sudden loss of a “bought” regulatory favor or the fallout from a bribery scandal. By avoiding the sin of simony, these companies build a brand and a business model that are resilient. They trade in value, not in favors.
The Future of Financial Integrity and Decentralization
As we look toward the future of money, new technologies are offering ways to automate away the opportunities for simony. The rise of Decentralized Finance (DeFi) and blockchain technology is, at its core, an attempt to remove the “middleman” who might be tempted to sell access or influence.
Democratizing Access Through Technology
In a truly transparent, code-based financial system, the “sin” of simony becomes much harder to commit. A smart contract does not care who your father is or how much you contributed to a political campaign. It executes based on predefined rules that apply to everyone equally. This democratization of access is the polar opposite of simony. It moves us toward a world where financial “blessings”—returns, liquidity, and credit—are distributed based on math and merit rather than the purchase of influence.
The Role of the Conscious Investor
Ultimately, the prevalence of simony in our financial systems depends on the complicity of the participants. As long as investors are willing to pay for “special” access and turn a blind eye to how their managers secure contracts, the practice will continue. However, a new generation of investors is demanding more. They are looking for more than just a return on investment; they are looking for a return to integrity. By identifying and rejecting the modern sin of simony, we can move toward a more equitable and stable financial future where the only thing for sale is the product itself, and the only way to win is to be the best in the market.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.