
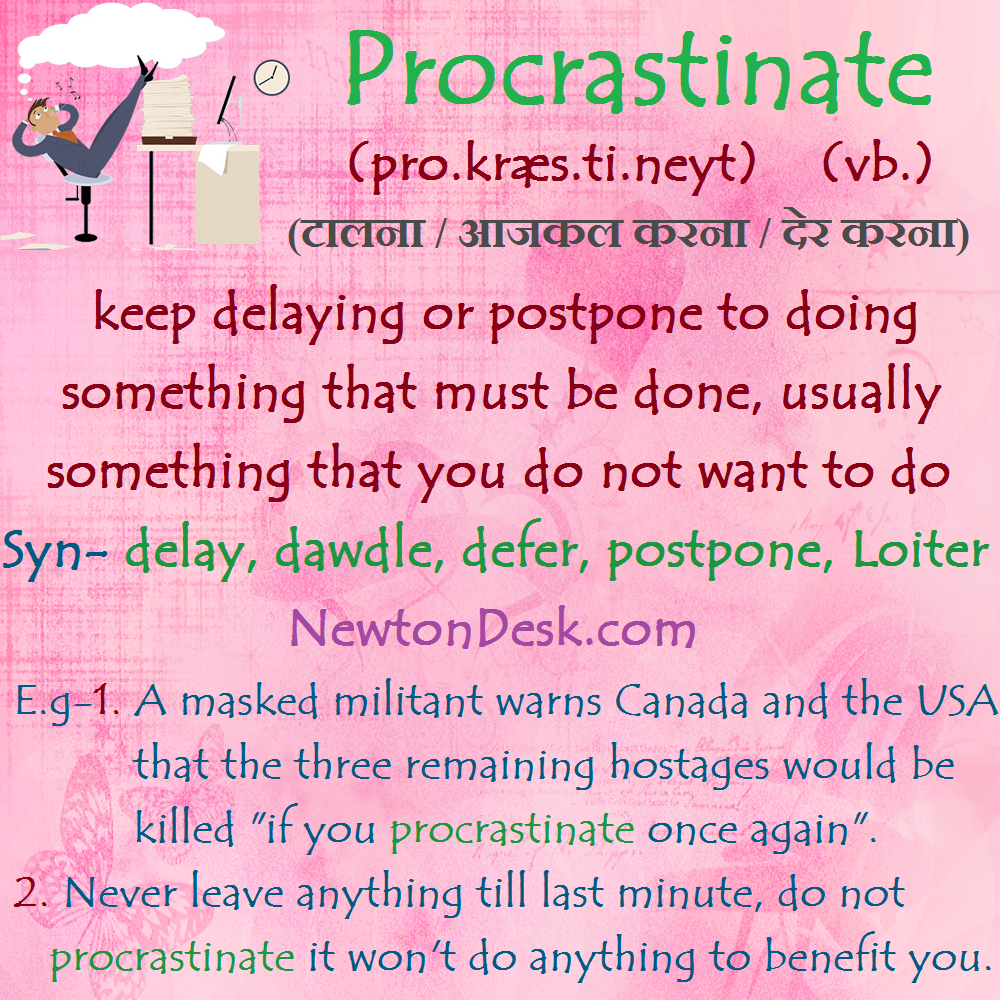
In the realm of personal finance and business strategy, the meaning of procrastinating transcends the simple act of “putting things off.” While the term is often associated with academic deadlines or household chores, in a financial context, procrastination is a quantifiable liability. It is the voluntary delay of an intended course of action despite expecting to be worse off for the delay. When applied to capital allocation, debt management, or investment strategy, procrastination acts as a silent tax on one’s future self, eroding the most valuable asset any investor possesses: time.

To understand the meaning of procrastinating within the money niche, one must view it through the lens of opportunity cost. Every day a decision is deferred—whether it is starting a retirement fund, refinancing a high-interest loan, or launching a side venture—the potential for growth diminishes while the cost of entry often increases. This article explores the deep financial implications of procrastination, the psychological barriers that lead to fiscal inertia, and the systemic strategies required to overcome the “wait and see” mentality that plagues so many balance sheets.
Understanding Procrastination Through the Lens of Opportunity Cost
In economic terms, the meaning of procrastinating is synonymous with the mismanagement of opportunity cost. Opportunity cost represents the benefits an individual, investor, or business misses out on when choosing one alternative over another. When the choice is “doing nothing” (procrastinating) versus “taking action,” the cost is the foregone return on that action.
Temporal Discounting and the Wealth Gap
A primary driver of financial procrastination is a psychological phenomenon known as temporal discounting. This is the tendency for people to value smaller, immediate rewards over larger, delayed rewards. In money management, this manifests as spending a paycheck on a luxury item today rather than investing it for a much larger payout in twenty years.
The “meaning” of procrastinating here is a fundamental disconnect between the current self and the future self. Financial success requires a cognitive bridge between these two identities. When we procrastinate on saving or investing, we are essentially treating our future self as a stranger whose needs are less urgent than our current desires. This cognitive bias creates a wealth gap that becomes increasingly difficult to close as one ages.
The Psychology of Financial Avoidance
Financial procrastination is rarely about laziness; it is often rooted in anxiety and the fear of making a wrong decision. This is frequently referred to as “Analysis Paralysis.” When faced with a complex array of investment options—ETFs, mutual funds, crypto-assets, or real estate—the sheer volume of information can lead to a total shutdown of the decision-making process.
In this context, procrastination is a defense mechanism. By not choosing, the individual avoids the immediate pain of a potential mistake. However, in the world of finance, the “non-choice” is, in itself, a choice with a guaranteed negative outcome: the loss of time-weighted returns. Understanding that a “good” plan executed today is superior to a “perfect” plan executed three years from now is the first step toward financial literacy.
The Mathematics of Delay: How Procrastination Erodes Your Net Worth
To truly grasp the meaning of procrastinating in finance, one must look at the math. The power of compounding interest is often called the eighth wonder of the world, but it only functions when given a long runway. Procrastination effectively shortens that runway, leading to exponential losses.
The Retirement Penalty: A Decadal Comparison
Consider two individuals, Investor A and Investor B. Investor A understands the cost of procrastination and begins investing $500 a month at age 25. Investor B procrastinates, waiting until age 35 to start the exact same monthly contribution. Assuming an average annual return of 7%, by the time both reach age 65, Investor A will have approximately $560,000 more than Investor B.
The “meaning” of those ten years of procrastination for Investor B was a half-million-dollar penalty. Investor B would have to nearly double their monthly contributions for the rest of their working life just to catch up to where Investor A would have been by starting early. This illustrates that the cost of procrastination is not linear; it is compounding.
Debt Stagnation and Interest Accumulation
Procrastination is equally destructive on the liability side of the balance sheet. Delaying the repayment of high-interest debt, such as credit card balances, is a form of financial self-sabotage. Many individuals procrastinate on debt consolidation or aggressive repayment because the total sum feels overwhelming.
However, the meaning of procrastinating on debt is the voluntary payment of “rent” on money you have already spent. Every month a balance is carried, the interest charges accumulate, often at rates exceeding 20%. By delaying action, the debtor ensures that a larger portion of their future income is diverted toward interest rather than principal, creating a cycle of “interest-only” living that can last decades.
Market Inertia: Why “Waiting for the Right Moment” Is a Losing Strategy
In the world of investing, procrastination often masquerades as “prudence.” Investors claim they are waiting for a market correction, a clearer economic outlook, or a dip in prices before committing their capital. This is the classic meaning of procrastinating in a professional investment context.
Analysis Paralysis in the Equities Market
Market timing is a notoriously difficult feat that even seasoned professionals struggle to master. For the average investor, procrastinating on entering the market because of “uncertainty” usually results in missing the most profitable days of the year. History shows that the bulk of stock market gains often occur in short, unpredictable bursts.
By procrastinating and staying in cash, an investor is essentially betting that they can predict the bottom of a cycle. The cost of being wrong is significant. Missing just the ten best-performing days of the S&P 500 over a 20-year period can result in a portfolio value that is 50% lower than if the investor had remained consistently invested.
The Real Estate Lag: Missing the Cycle
Procrastination in real estate often revolves around the dream of the “perfect property” or the “perfect interest rate.” While due diligence is necessary, chronic procrastination in a rising market can price an individual out of a neighborhood permanently. The meaning of procrastinating in real estate is often the difference between building equity in one’s own asset and paying down a landlord’s mortgage. As property values and rents rise, the barrier to entry grows, making the initial delay a permanent financial setback.
Entrepreneurial Procrastination: The Hidden Cost to Business Growth
For business owners and side-hustlers, procrastination is a direct threat to scalability and competitive advantage. In the corporate world, the meaning of procrastinating is the loss of market share.
Delaying the Pivot or Product Launch
Innovation waits for no one. When an entrepreneur procrastinates on launching a Minimum Viable Product (MVP) because they want it to be “perfect,” they lose the opportunity to gather real-world data. In the interim, a competitor may enter the market with a less polished but functional version, capturing the early adopters.
The financial meaning of procrastinating on a launch is the loss of the “First Mover Advantage.” In business, speed is often more valuable than precision. Procrastination in this niche results in sunk costs—money spent on development that never sees a return because the market window has closed.
The Cost of Inefficient Tax and Compliance Management
Many small business owners procrastinate on administrative tasks, such as bookkeeping, tax planning, and compliance. This is perhaps the most avoidable form of financial procrastination. Delaying these tasks leads to late fees, missed deductions, and, in extreme cases, legal audits that can bankrupt a burgeoning enterprise. Effective wealth management requires proactive tax strategies; procrastinating until April 14th to look at your finances means you have already lost the chance to implement tax-saving measures for the previous year.
Systems Over Willpower: Reversing the Trend of Financial Inactivity
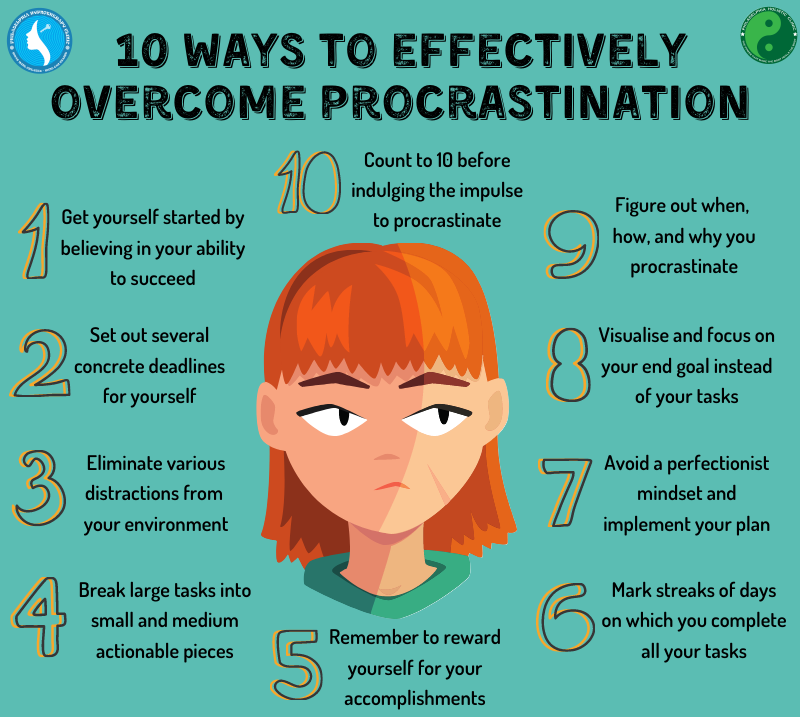
If the meaning of procrastinating is rooted in psychological avoidance and fear, the solution is not “trying harder” but rather building systems that remove human emotion from the equation.
Leveraging Automation to Bypass Human Error
The most effective way to combat financial procrastination is through automation. By setting up automatic transfers to savings accounts, investment portfolios, and debt payments, the individual removes the need to make a “choice” every month. Automation solves the problem of temporal discounting by ensuring the future self is paid before the current self has a chance to spend or hesitate.
The Minimum Viable Financial Plan
To overcome analysis paralysis, one must embrace the “Minimum Viable Financial Plan.” This involves identifying the three most impactful actions one can take—such as contributing to a 401(k) up to the employer match, building a three-month emergency fund, and paying off high-interest debt—and executing them immediately.
The meaning of procrastinating is often tied to the feeling of being overwhelmed. By narrowing the focus to a few critical moves, the barrier to action is lowered. Once these foundational elements are in place, the momentum of success usually makes it easier to tackle more complex financial decisions later.
In conclusion, the meaning of procrastinating in the world of money is the active destruction of potential wealth. Whether it is through missed compound interest, accumulated debt, or lost business opportunities, the cost of “later” is always higher than the cost of “now.” Professional financial health requires the recognition that time is a finite resource and that inactivity is the most expensive strategy an individual can employ. Turning “someday” into “today” is the single most effective investment one can ever make.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.