
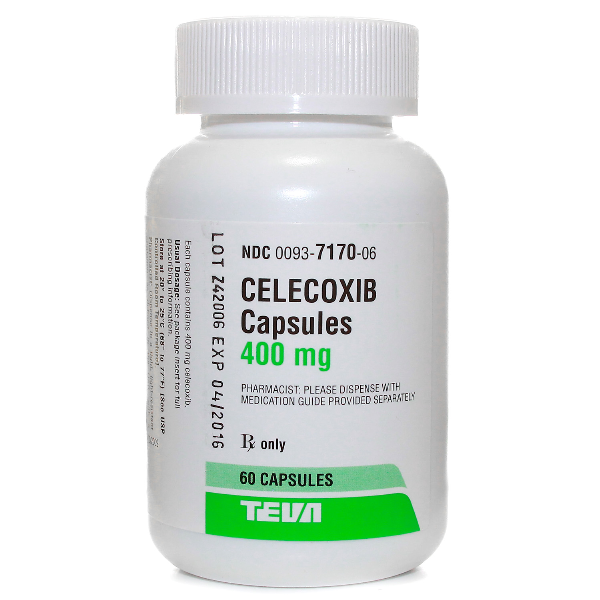
For the cost-conscious consumer and the savvy personal finance enthusiast, understanding the pharmaceutical market is as essential as tracking interest rates or stock market volatility. When a physician prescribes a medication like Celebrex, the immediate financial question is rarely about the chemical composition, but rather: “What is the generic version, and how much will it save me?” The generic equivalent of Celebrex is celecoxib.
While the name change from Celebrex to celecoxib might seem minor, the financial implications are massive. Transitioning from a brand-name drug to its generic counterpart is one of the most effective ways to optimize a personal healthcare budget, often reducing out-of-pocket expenses by 80% to 85%. In the broader context of personal finance and business economics, the story of Celebrex and celecoxib serves as a masterclass in market competition, patent lifecycles, and the high cost of brand loyalty in the medical sector.

The Financial Transition from Brand to Generic
The pharmaceutical industry operates on a cycle of high-risk investment followed by a period of protected profit. When Celebrex was first introduced by Pfizer, it was a breakthrough non-steroidal anti-inflammatory drug (NSAID) known as a COX-2 inhibitor. Because the company invested billions into research, development, and clinical trials, they were granted a patent that allowed them to be the exclusive provider of the drug for years. During this time, the “brand premium” was at its peak.
Breaking Down the Price Delta
The price delta between a brand-name drug and its generic is driven by the absence of “sunk costs.” Generic manufacturers do not have to replicate the original research or the expensive clinical trials that proved the drug’s safety and efficacy. Instead, they simply have to prove to the FDA that their version, celecoxib, is bioequivalent to Celebrex—meaning it works in the same way and provides the same clinical benefit.
From a personal finance perspective, this creates a massive arbitrage opportunity for the consumer. While a 30-day supply of brand-name Celebrex can cost several hundred dollars without insurance, the generic celecoxib can often be found for under $20 through various discount programs. This 90% reduction in cost is not a reflection of lower quality, but a reflection of a competitive market where multiple manufacturers are now producing the same molecule.
Why the Name Matters to Your Wallet
In the world of marketing and brand strategy, “Celebrex” is a multi-billion dollar asset. In the world of your personal balance sheet, it is an unnecessary expense. The pharmaceutical industry spends billions on direct-to-consumer advertising to ensure that when you think of joint pain or arthritis, you think of their brand name.
However, from a financial utility standpoint, the molecule is what provides the value, not the label. By insisting on the generic celecoxib, you are essentially refusing to pay for the manufacturer’s marketing budget and historical R&D costs. In financial terms, choosing the generic is a “value play”—you are getting the exact same utility at a fraction of the price.
Healthcare as a Personal Finance Line Item
In the modern financial landscape, healthcare is often the largest “wildcard” variable in a household budget. Whether you are managing a chronic condition or dealing with temporary inflammation, the way you interact with the pharmacy counter can dictate your ability to hit other financial goals, such as retirement contributions or emergency fund targets.
Leveraging Insurance Formularies for Cost Reduction
Most private insurance plans and Medicare Part D providers use what is known as a “formulary.” This is a tiered list of drugs that determines how much the insurance company will cover and how much the patient will pay in co-pays.
- Tier 1: Preferred Generics (Lowest co-pay, often $0–$10).
- Tier 2: Non-preferred Generics or Preferred Brands.
- Tier 3: Non-preferred Brands (High co-pay).
- Tier 4/Specialty: Most expensive drugs.
Celecoxib almost universally falls into Tier 1 or Tier 2, whereas Celebrex remains in the higher, more expensive tiers. If your doctor prescribes the brand name, your insurance might even refuse to cover it until a “step therapy” process is completed, where you are forced to try the generic first. Understanding this financial structure allows you to have an informed conversation with your healthcare provider about “prescribing for your budget” as much as for your biology.
Tax-Advantaged Accounts: HSAs and FSAs
For those utilizing High Deductible Health Plans (HDHPs), the choice between Celebrex and celecoxib has a direct impact on the longevity of a Health Savings Account (HSA). Since an HSA is a triple-tax-advantaged vehicle—offering tax-deductible contributions, tax-free growth, and tax-free withdrawals for medical expenses—every dollar saved on a prescription is a dollar that can remain invested in the market.
If you spend $200 a month on a brand-name drug instead of $15 on a generic, you are losing $185 of “investable capital.” Over 10 years, assuming a 7% market return, that $185 monthly difference represents a lost opportunity cost of nearly $30,000. In this light, the decision to use the generic celecoxib is not just a daily saving; it is a long-term investment strategy.
The Business of Pharmaceuticals: Brand Protection vs. Generic Competition
To understand why Celebrex costs what it does, one must look at the business strategy of pharmaceutical giants. The transition of a drug from patent-protected to generic is often referred to as the “patent cliff.” When a drug falls off this cliff, the original manufacturer can lose up to 90% of their revenue from that product within a year.
Patent Expirations and the “Patent Cliff”
The lifecycle of Celebrex is a classic example of corporate financial defense. As the patent expiration approached, the manufacturer employed various strategies to maintain market share, including authorized generics and legal challenges. For the investor or the business student, this illustrates the tension between innovation (which requires high profits) and accessibility (which requires competition).
When the patent for Celebrex finally expired, it opened the floodgates for manufacturers like Teva, Mylan, and Lupin to enter the market with their own versions of celecoxib. This shift from a monopoly to a perfectly competitive market is what drives prices down. As a consumer, you are the beneficiary of this macroeconomic shift.
Generic Entry and the Law of Supply and Demand
The price of celecoxib is not fixed; it is subject to the laws of supply and demand. In the early months after a patent expires, the first generic manufacturer may have a period of “exclusivity,” keeping prices relatively high. However, once four or five different companies are producing the same 200mg capsule of celecoxib, the drug becomes a commodity. At this point, the price is driven down to the marginal cost of production, which is incredibly low for most chemical synthesis.
Tools and Strategies for Optimizing Medical Spending
Knowing the name of the generic is only the first step. To truly master the “money” side of healthcare, you must use the financial tools available to compare prices and bypass traditional insurance friction.
Comparison Shopping and Digital Financial Tools
In many cases, the “negotiated rate” your insurance company provides for a generic drug is actually higher than the cash price. Digital tools and platforms have revolutionized this aspect of personal finance.
- Cash-Pay Pharmacies: Companies like Mark Cuban’s Cost Plus Drug Company have disrupted the market by offering drugs like celecoxib at a flat 15% markup over the manufacturing cost, plus a small labor fee. This often results in prices lower than an insurance co-pay.
- Discount Cards: Platforms like GoodRx or SingleCare act as aggregators, allowing consumers to see which local pharmacy (CVS, Walgreens, Costco, etc.) has the lowest price for celecoxib in real-time.
Using these tools is a form of financial due diligence. Just as you wouldn’t buy a car or a house without comparing prices, you should not fill a recurring prescription without checking the competitive landscape of pharmacy pricing.
The Hidden Role of Pharmacy Benefit Managers (PBMs)
The reason why Celebrex stays expensive, and why you might not always be offered the cheapest generic, often lies with Pharmacy Benefit Managers (PBMs). These are the “middlemen” of the healthcare industry. They negotiate rebates from manufacturers. Sometimes, a PBM might actually prefer a brand-name drug because the rebate they receive from the manufacturer is higher than the savings from a generic.
This opaque financial system means that the consumer must be their own advocate. Always ask the pharmacist: “Is the cash price for the generic celecoxib lower than my insurance co-pay?” Frequently, the answer will surprise you, and paying out-of-pocket can actually save you money while keeping your insurance premiums or deductible counts in check.
The Bottom Line on Celecoxib Savings
The transition from brand-name Celebrex to generic celecoxib is a clear win for your personal finances. By understanding the generic name, the market forces that determine its price, and the tools available to find the best deal, you can take control of your healthcare spending. In a world where financial uncertainty is common, optimizing your “fixed” costs—like recurring prescriptions—is one of the most reliable ways to increase your discretionary income and build long-term wealth.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.