
In the world of personal finance and global economics, the number 0.01 represents far more than a simple mathematical value. While the immediate answer to the question “what is the fraction for 0.01” is mathematically straightforward—1/100—the implications of this fraction are foundational to how we understand money, interest, and the growth of wealth. Whether you are analyzing a bank’s interest rate, calculating the expense ratio of an index fund, or tracking the dividend yield of a blue-chip stock, the ability to conceptualize 0.01 as one part of a hundred is essential for financial literacy.
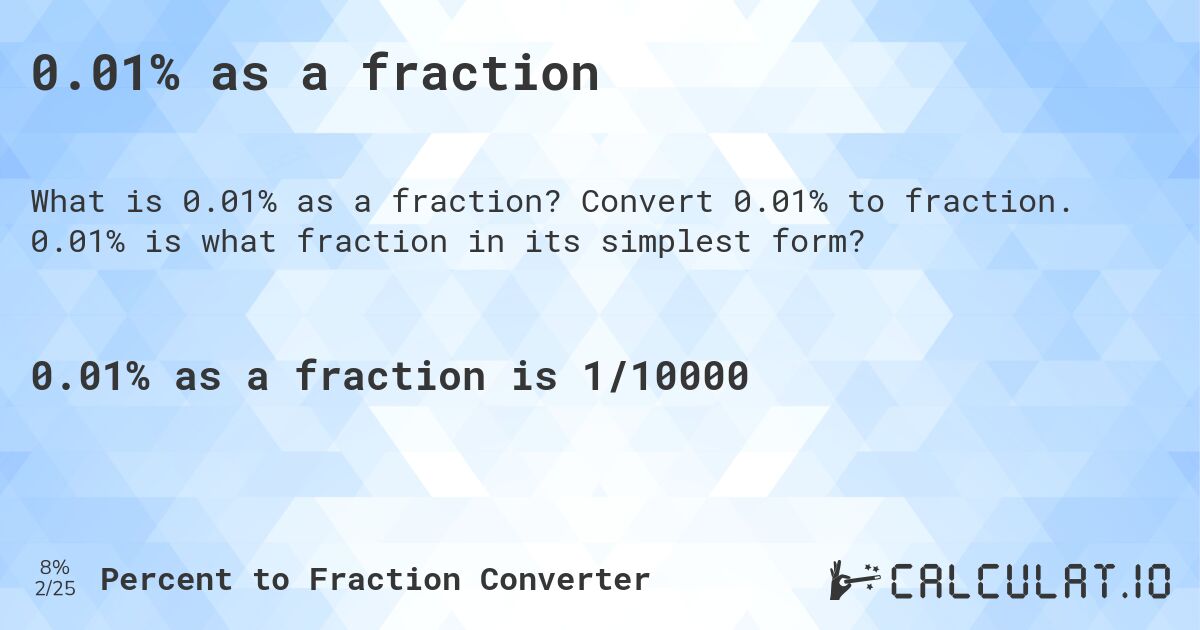
The Mathematical Foundation: Converting 0.01 to its Fractional Form
To understand the weight of 0.01 in a financial context, one must first master the conversion process. Mathematics is the language of money, and decimals are simply another way to express fractions. In our base-10 monetary system, decimals allow for the precise division of assets.
The Place Value System
The decimal 0.01 is positioned two places to the right of the decimal point. In the standard place value system, the first position to the right is the “tenths” place, and the second is the “hundredths” place. Therefore, 0.01 literally translates to “one-hundredth.” When we write this as a fraction, the numerator is the significant digit (1) and the denominator is the place value (100). This results in the fraction 1/100.
Practical Conversion Steps
To convert any decimal like 0.01 into a fraction, you follow a standardized logical path used by financial analysts and accountants:
- Identify the Place Value: Since 0.01 reaches the hundredths place, the denominator will be 100.
- Remove the Decimal: The number becomes the numerator. In this case, 1.
- Simplify: The fraction 1/100 is already in its simplest form, as 1 and 100 share no common factors other than 1.
Why the Fraction 1/100 Matters in Financial Literacy
Understanding that 0.01 is 1/100 is the first step in understanding percentages. The term “percent” comes from the Latin per centum, meaning “by the hundred.” Therefore, 0.01 is equivalent to 1%. In personal finance, 1% is often the “tipping point” for many financial decisions. Whether it is a 1% cash-back reward on a credit card or a 1% annual fee on a managed investment account, recognizing this value as 1/100 of your total capital helps in visualizing the actual cost or gain of a financial product.
The Power of 0.01 in Investing and Banking
In large-scale investing, the fraction 1/100 is not just a small number; it is a significant lever that can move millions of dollars. Professional traders and institutional investors rarely look at 0.01 as a negligible “penny.” Instead, they see it as a fundamental unit of measurement that dictates market trends and portfolio health.
Basis Points (BPS) and Interest Rates
In the world of fixed income and central banking, 0.01 is often further divided into “basis points.” One basis point is defined as 1/100th of 1 percent (0.0001). However, the primary movement of interest rates often occurs in increments that reflect the 0.01 (1%) scale. When the Federal Reserve adjusts interest rates by “25 basis points,” they are moving the needle by 0.25%, which is a fraction of the 1/100 unit. For a homeowner with a $500,000 mortgage, a difference of 0.01 (1%) in an interest rate can result in tens of thousands of dollars in interest paid over the life of the loan.
The Impact of 0.01 on Large Portfolios
For a retail investor with $1,000, 1/100 of their portfolio is only $10. However, for a hedge fund managing $10 billion, 0.01 represents $100 million. This scalability is why financial software and high-frequency trading algorithms are designed to capture gains even smaller than 0.01. In the context of “slippage” during trades, a price movement of 0.01 can be the difference between a profitable quarter and a loss.
Expense Ratios and Fund Management
One of the most critical applications of the 0.01 fraction is in the calculation of expense ratios for Mutual Funds and Exchange-Traded Funds (ETFs). An expense ratio is the annual fee that all funds or ETFs charge their shareholders. It is expressed as a percentage of the fund’s daily net assets. If an index fund has an expense ratio of 0.01 (1%), you are paying $1 for every $100 invested. While this sounds small, the compounding effect of losing 1/100 of your capital every year to fees can reduce a retirement nest egg by hundreds of thousands of dollars over 30 years. Savvy investors look for “low-cost” funds where the fraction is even smaller, such as 0.0003 (0.03%).
Micro-Investing and the “Penny” Strategy

While institutional finance deals with 0.01 on a massive scale, the rise of fintech has allowed individual consumers to leverage the 1/100 fraction to build wealth from the ground up. This is commonly referred to as micro-investing.
Fractional Shares and Decimal Ownership
Historically, to own a piece of a company like Berkshire Hathaway or Amazon, an investor needed enough cash to buy a full share, which could cost thousands of dollars. Modern brokerage apps have revolutionized this through “fractional shares.” Investors can now buy 0.01 of a share. This allows someone with only $10 to own a small fraction (1/100) of an expensive stock. This democratization of the stock market relies entirely on the mathematical precision of the 0.01 decimal, ensuring that even small-scale participants can benefit from the growth of major corporations.
Dividend Yields and Precision
Dividends are payments made by a corporation to its shareholders. Often, these dividends are distributed in cents per share. For example, a company might pay a dividend of $0.01 per share. While this seems inconsequential, an investor holding 10,000 shares would receive $100. Understanding the 1/100 fraction allows investors to calculate their “Yield on Cost,” helping them determine if the income generated by an asset justifies the capital risk.
Round-Up Apps: Turning 0.01 into Wealth
Several popular financial tools use the “round-up” method to encourage saving. These apps monitor a user’s spending; if a user buys a coffee for $3.99, the app rounds the transaction to $4.00 and invests the $0.01 difference. This strategy operates on the philosophy that 1/100 of a dollar is a negligible amount for daily spending but, when aggregated over thousands of transactions and allowed to compound, can form the basis of a significant investment portfolio.
Digital Currencies and the Division of Assets
The emergence of cryptocurrency has pushed the concept of fractional ownership even further than traditional finance. While the US dollar is typically divided into 100 parts (cents), digital assets are often divisible by much smaller fractions, yet the 0.01 threshold remains a psychological and functional benchmark.
Satoshi Units and Small Denominations
In the Bitcoin ecosystem, the smallest unit is a “Satoshi,” which is 0.00000001 BTC. However, as the price of Bitcoin fluctuates, investors often think in terms of 0.01 BTC. If Bitcoin is priced at $60,000, 0.01 (or 1/100th) of a Bitcoin is worth $600. This makes 0.01 a common entry point for casual investors who want exposure to the asset class without purchasing a whole unit.
Transaction Fees and Gas Costs
In decentralized finance (DeFi), transaction fees—often called “gas fees”—are calculated using decimals. An investor might pay 0.01 of an Ether token to move assets across a network. Understanding the fractional value of 0.01 in the context of the current market price is vital to ensure that transaction costs do not exceed the value of the trade itself.
Psychological Barriers to Small Decimals
Despite its mathematical simplicity, the fraction 1/100 often presents a psychological challenge for investors. Humans are naturally inclined to focus on whole numbers, frequently dismissing the “small change” represented by 0.01.
The “Small Change” Fallacy
The “small change” fallacy is the cognitive bias where individuals undervalue small denominations of money. In personal finance, this manifests as a willingness to waste pennies or overlook small recurring fees. However, because money is cumulative, every 0.01 is a building block. Successful financial planning requires a shift in perspective: seeing 0.01 not as a remnant of a dollar, but as 1% of a future goal.

Compound Interest: The Long-Term Value of 1/100
Albert Einstein reportedly called compound interest the “eighth wonder of the world.” The magic of compounding relies on small, consistent gains. A portfolio that grows by an average of 7.01% annually will significantly outperform a portfolio growing at 7.00% over several decades. That 0.01 difference—the 1/100th of a percent—compounds upon itself, creating a wider and wider gap in total wealth.
In conclusion, while “what is the fraction for 0.01” is a question with a simple mathematical answer (1/100), its application in the world of money is vast and complex. From the basis points that dictate global trade to the round-up apps that help individuals save their first thousand dollars, the hundredth place is where much of the world’s financial growth is calculated. By mastering the understanding of this small fraction, investors can better navigate fees, maximize interest, and appreciate the immense power of incremental wealth building.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.