
Navigating the housing market, whether as a first-time homebuyer or a seasoned investor looking to refinance, inevitably leads to one crucial question: “What is the current mortgage rate?” This seemingly simple query, however, belies a complex interplay of economic forces, individual financial profiles, and market dynamics that shape the final interest rate an individual receives. Understanding the current landscape of mortgage rates is paramount, as even a small difference can translate into tens of thousands of dollars over the lifespan of a loan, significantly impacting affordability, monthly payments, and long-term financial planning.
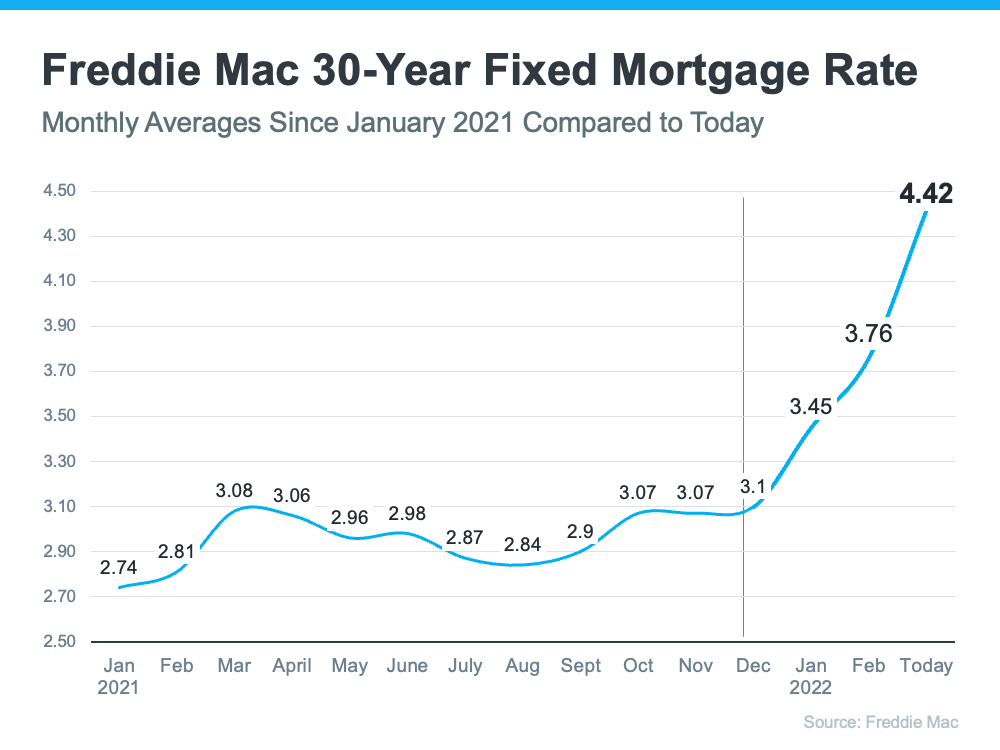
Mortgage rates are not static; they are highly dynamic, fluctuating daily, sometimes even hourly, in response to a myriad of global and domestic indicators. They represent the cost of borrowing money to purchase a home, expressed as a percentage of the loan amount. This article will delve into the multifaceted world of mortgage rates, exploring the factors that influence them, the various types of loans available, how a borrower’s personal financial health impacts their eligibility and rate, and strategies to secure the most favorable terms in today’s market. By demystifying the “current mortgage rate,” we aim to equip you with the knowledge to make informed and strategic decisions in your homeownership journey.
Understanding Mortgage Rates: More Than Just a Number
To truly grasp what the “current mortgage rate” signifies, one must look beyond the advertised percentage and understand the underlying components and the broader economic landscape that dictates its movement. It’s a figure that encapsulates a great deal about the economy and your personal financial standing.
The Anatomy of a Mortgage Rate
When you see a mortgage rate advertised, it’s typically referring to the interest rate – the percentage of the principal loan amount that a lender charges you annually for the use of their money. However, this isn’t the whole story. The Annual Percentage Rate (APR) is a more comprehensive measure of the total cost of borrowing. APR includes the interest rate plus other fees and charges associated with the loan, such as origination fees, discount points, and some closing costs. Comparing APRs across different lenders provides a more accurate picture of the true cost of a loan, making it a superior metric for comparison than the interest rate alone.
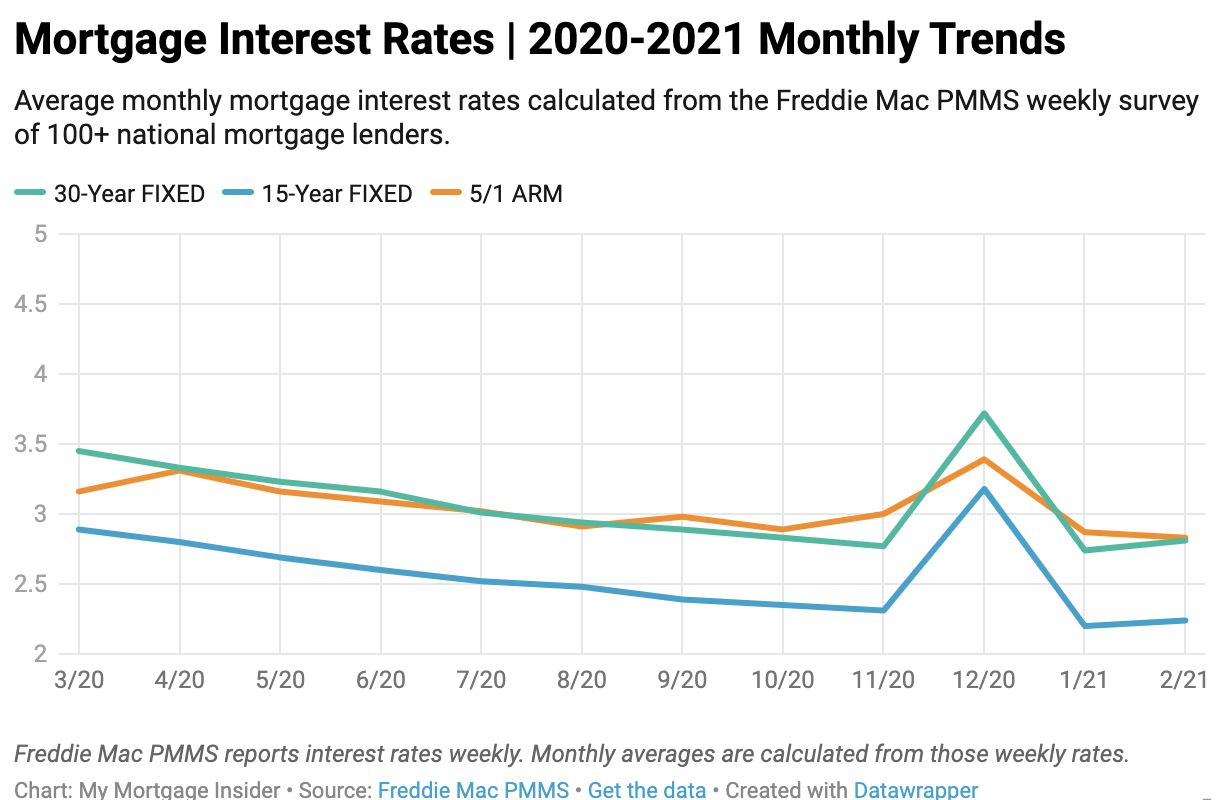
Mortgages also come in two primary forms: Fixed-Rate Mortgages (FRMs) and Adjustable-Rate Mortgages (ARMs). A fixed-rate mortgage ensures your interest rate remains constant for the entire loan term, providing predictability in your monthly payments. An adjustable-rate mortgage, on the other hand, typically starts with a lower, fixed interest rate for an initial period (e.g., 3, 5, 7, or 10 years) and then adjusts periodically based on a benchmark index, potentially leading to higher or lower payments over time.
Key Factors Influencing Rates
Mortgage rates are not set in a vacuum. They are heavily influenced by a confluence of macroeconomic factors, financial market conditions, and central bank policies. Understanding these drivers is crucial for anticipating rate movements.
-
Economic Indicators: Rates tend to rise with a strong economy, marked by low unemployment, robust GDP growth, and rising inflation. Lenders anticipate that if the economy is growing, there will be more demand for money, and they will need to charge more for it. Conversely, economic slowdowns or recessions often lead to lower rates as the Federal Reserve might cut rates to stimulate economic activity.
-
Federal Reserve Policy: While the Federal Reserve doesn’t directly set mortgage rates, its actions significantly impact them. When the Fed raises or lowers the federal funds rate – the target rate for overnight lending between banks – it influences other interest rates throughout the economy, including those on consumer loans and mortgages. The Fed’s stance on quantitative easing or tightening, involving the buying or selling of government bonds and mortgage-backed securities, also plays a critical role.
-
Treasury Yields: The yield on the 10-year Treasury note is a particularly strong indicator for fixed mortgage rates. Mortgage rates tend to move in tandem with 10-year Treasury yields, as both are influenced by investor expectations for inflation and economic growth. When investors demand higher returns on Treasuries, it often signals an expectation of higher inflation, pushing mortgage rates up.
-
Mortgage-Backed Securities (MBS) Market: A significant portion of mortgages are packaged into Mortgage-Backed Securities and sold to investors. The demand for and pricing of these securities in the secondary market directly impact the rates lenders offer. High demand for MBS allows lenders to offer lower rates, while low demand or higher perceived risk drives rates up.
-
Global Economic Events: International conflicts, geopolitical instability, commodity price fluctuations, or financial crises in other major economies can trigger a “flight to safety,” where investors pull money out of riskier assets and into safer government bonds, potentially lowering Treasury yields and, consequently, mortgage rates. Conversely, global inflationary pressures can push rates higher.
Types of Mortgage Rates Available Today
The variety of mortgage products on the market can be overwhelming, but understanding the core categories and their nuances is essential for choosing the loan that best fits your financial strategy and risk tolerance.
Fixed-Rate Mortgages (FRMs): Stability in an Unpredictable Market
Fixed-rate mortgages are the most common and often preferred choice for homebuyers seeking predictability. Your interest rate remains constant for the entire life of the loan, meaning your principal and interest payments never change, regardless of market fluctuations.
-
30-Year Fixed-Rate Mortgage: This is the most popular choice, offering the lowest monthly payments due to the extended repayment period. While the monthly payments are more manageable, you’ll pay more interest over the life of the loan compared to shorter terms. It provides excellent long-term budget stability.
-
15-Year Fixed-Rate Mortgage: This option features a significantly higher monthly payment than a 30-year loan but comes with a lower overall interest rate and results in substantial interest savings over the life of the loan. Borrowers build equity much faster, paying off their home in half the time. It’s ideal for those with stable, higher incomes who can comfortably afford the increased monthly commitment.
Adjustable-Rate Mortgages (ARMs): Flexibility with Calculated Risk
ARMs are characterized by an initial fixed-rate period, after which the interest rate adjusts periodically based on a predetermined index plus a margin. They are often designated by two numbers, like a 5/1 ARM, meaning the rate is fixed for the first five years and then adjusts annually thereafter.
-
Hybrid ARMs (e.g., 5/1 ARM, 7/1 ARM, 10/1 ARM): These are the most common types of ARMs. The first number indicates the length of the initial fixed-rate period (e.g., 5 years), and the second number indicates how often the rate adjusts after that (e.g., every 1 year). ARMs typically start with a lower interest rate than comparable fixed-rate mortgages, making them attractive for borrowers who anticipate selling or refinancing before the fixed period ends, or those who expect their income to increase significantly.
-
Rate Caps: ARMs include various caps that limit how much the interest rate can change. An initial cap limits the first adjustment, a periodic cap limits subsequent adjustments, and a lifetime cap limits how much the rate can increase over the entire loan term. While these caps provide some protection, borrowers must be comfortable with the potential for increased monthly payments if rates rise.
Government-Insured Loans: Special Options for Specific Needs
Beyond conventional loans, several government-backed programs offer unique advantages, often targeting specific borrower demographics or property types.
-
FHA Loans: Insured by the Federal Housing Administration, these loans are designed to help borrowers with lower credit scores or smaller down payments (as low as 3.5%) qualify for a mortgage. They require mortgage insurance premiums (MIP) for the life of the loan.
-
VA Loans: Guaranteed by the Department of Veterans Affairs, these loans are available to eligible service members, veterans, and surviving spouses. They offer significant benefits, including no down payment requirement, no private mortgage insurance (PMI), and competitive interest rates.
-
USDA Loans: Backed by the U.S. Department of Agriculture, these loans aim to promote homeownership in eligible rural and suburban areas. They offer 100% financing (no down payment) for low- and moderate-income borrowers, subject to specific property and income requirements.
How Your Personal Profile Affects Your Rate
While broader economic factors set the general trend for mortgage rates, your individual financial circumstances play a critical role in determining the specific rate you’ll be offered. Lenders assess your risk as a borrower, and the lower the perceived risk, the better your rate will likely be.
Credit Score: Your Financial Report Card
Your credit score, primarily your FICO score, is one of the most significant determinants of your mortgage rate. It’s a numerical representation of your creditworthiness, reflecting your payment history, amounts owed, length of credit history, new credit, and credit mix.
-
Impact of FICO Score Ranges: Borrowers with excellent credit scores (typically 760 and above) qualify for the lowest interest rates, as they are deemed the least risky. As your score decreases, the interest rate you’re offered generally increases to compensate the lender for the higher perceived risk of default.
-
Improving Your Credit Score: Prior to applying for a mortgage, focusing on improving your credit score can yield substantial savings. This includes paying bills on time, reducing outstanding debt, avoiding opening new credit accounts, and correcting any errors on your credit report.
Down Payment: The Bigger, The Better
The amount of money you put down upfront as a down payment directly impacts your Loan-to-Value (LTV) ratio, which is the amount of your mortgage divided by the home’s appraised value.
-
Relationship Between Down Payment Size and LTV: A larger down payment results in a lower LTV, signaling less risk to the lender. This can translate into a lower interest rate. Conversely, a smaller down payment (e.g., less than 20%) means a higher LTV and often a higher interest rate.
-
Private Mortgage Insurance (PMI) Implications: If your down payment is less than 20% of the home’s purchase price, lenders typically require you to pay for Private Mortgage Insurance (PMI). PMI protects the lender in case you default on your loan. While it makes homeownership accessible with less upfront capital, it adds to your monthly housing costs and doesn’t benefit you directly.
Debt-to-Income (DTI) Ratio: Balancing Your Books
Your Debt-to-Income (DTI) ratio is a key metric lenders use to assess your ability to manage monthly payments and repay debt. It compares your total monthly debt payments to your gross monthly income.
-
Front-End vs. Back-End DTI: Lenders often look at two DTI ratios. The “front-end” ratio (or housing ratio) calculates the percentage of your gross income that goes towards housing costs (principal, interest, taxes, insurance). The “back-end” ratio (or total debt ratio) includes all monthly debt payments, including housing, car loans, student loans, and credit card payments.
-
Why Lenders Care: A lower DTI ratio indicates you have more disposable income available to meet your mortgage obligations, making you a less risky borrower and potentially qualifying you for a better rate. Lenders typically prefer a total DTI ratio no higher than 43% for conventional loans, though this can vary by loan type and lender.
Loan Term and Type
As discussed earlier, the chosen loan term (e.g., 15-year vs. 30-year fixed) and type (e.g., conventional, FHA, VA, ARM) also influence the rate. Shorter fixed-rate terms typically carry lower interest rates than longer ones because the lender is exposed to interest rate risk for a shorter period. Different loan types have their own rate structures based on the risk profiles they serve.
Strategies for Securing the Best Mortgage Rate
Given the significant financial implications of mortgage rates, being proactive and strategic in your approach can lead to substantial long-term savings. Securing the “current best mortgage rate” isn’t about luck; it’s about preparation and smart decision-making.
Shop Around and Compare Offers
This is arguably the most crucial step. Never settle for the first quote you receive. Mortgage rates can vary significantly between different lenders, even on the same day for the same borrower.
-
Getting Quotes from Multiple Lenders: Contact various lenders – traditional banks, credit unions, online lenders, and mortgage brokers. Each might have different loan products, underwriting criteria, and pricing models.
-
Importance of Comparing APR, Not Just Interest Rate: As mentioned, always compare the Annual Percentage Rate (APR), as it provides a truer reflection of the total cost of the loan, including all fees. Request a Loan Estimate from each lender, which is a standardized form that allows for easy comparison of rates and fees.
Optimize Your Financial Health
Before you even start shopping, dedicate time to strengthening your financial position. This will make you a more attractive borrower and qualify you for better rates.
-
Improving Credit Score, Reducing Debt: Work on paying down credit card balances, personal loans, and other debts. Make sure all your bill payments are on time. Consider checking your credit report for errors and disputing them.
-
Saving for a Larger Down Payment: The more you can put down upfront, the lower your LTV will be, potentially reducing your interest rate and avoiding PMI.
Understand Rate Locks and Points
These features allow you to control and potentially lower your interest rate once you’re in the application process.
-
What a Rate Lock Is and Its Duration: A rate lock guarantees that the interest rate you’ve been offered will remain the same for a specified period (e.g., 30, 45, or 60 days) while your loan is being processed. This protects you from rate increases during that time. Ensure your lock period is long enough to cover your expected closing date.
-
Paying Points to “Buy Down” the Rate vs. No-Points Loans: “Discount points” are an upfront fee paid to the lender in exchange for a lower interest rate. One point typically equals 1% of the loan amount. You’ll need to calculate a “breakeven point” to determine if paying points makes financial sense – how long will it take for the monthly savings to offset the upfront cost? If you plan to stay in the home for a long time, paying points might be beneficial.

Consider Refinancing
For current homeowners, refinancing can be a powerful tool to take advantage of lower current mortgage rates or adjust loan terms.
-
When It Makes Sense to Refinance: If current rates are significantly lower than your existing mortgage rate, refinancing can reduce your monthly payments or the total interest paid over the life of the loan. Other reasons include shortening your loan term to pay off the mortgage faster, converting an ARM to a fixed-rate loan for stability, or cashing out equity for other financial needs.
-
Costs of Refinancing: Be mindful that refinancing involves closing costs, similar to your original purchase loan. Ensure the savings generated by a lower rate outweigh these upfront expenses.
In conclusion, “what is the current mortgage rate?” is a question with a dynamic and multi-layered answer. It’s not a single, universal figure but rather a moving target shaped by global economic trends, central bank policies, and critically, your individual financial health. By understanding the factors at play, exploring the diverse range of available loan products, meticulously preparing your financial profile, and diligently shopping for the best terms, you can confidently navigate the mortgage market. Staying informed and seeking professional financial advice are your best allies in securing a rate that aligns with your financial goals and helps you achieve your homeownership aspirations.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.