
In the world of personal finance, few numbers carry as much weight as the mortgage interest rate. For the average homebuyer, a fluctuation of even half a percentage point can mean the difference between an affordable monthly payment and a financial burden that spans decades. When people ask, “What is the current interest rate for a mortgage?” they are rarely looking for a singular, static number. Instead, they are navigating a complex ecosystem influenced by global economics, central bank policies, and individual financial health.
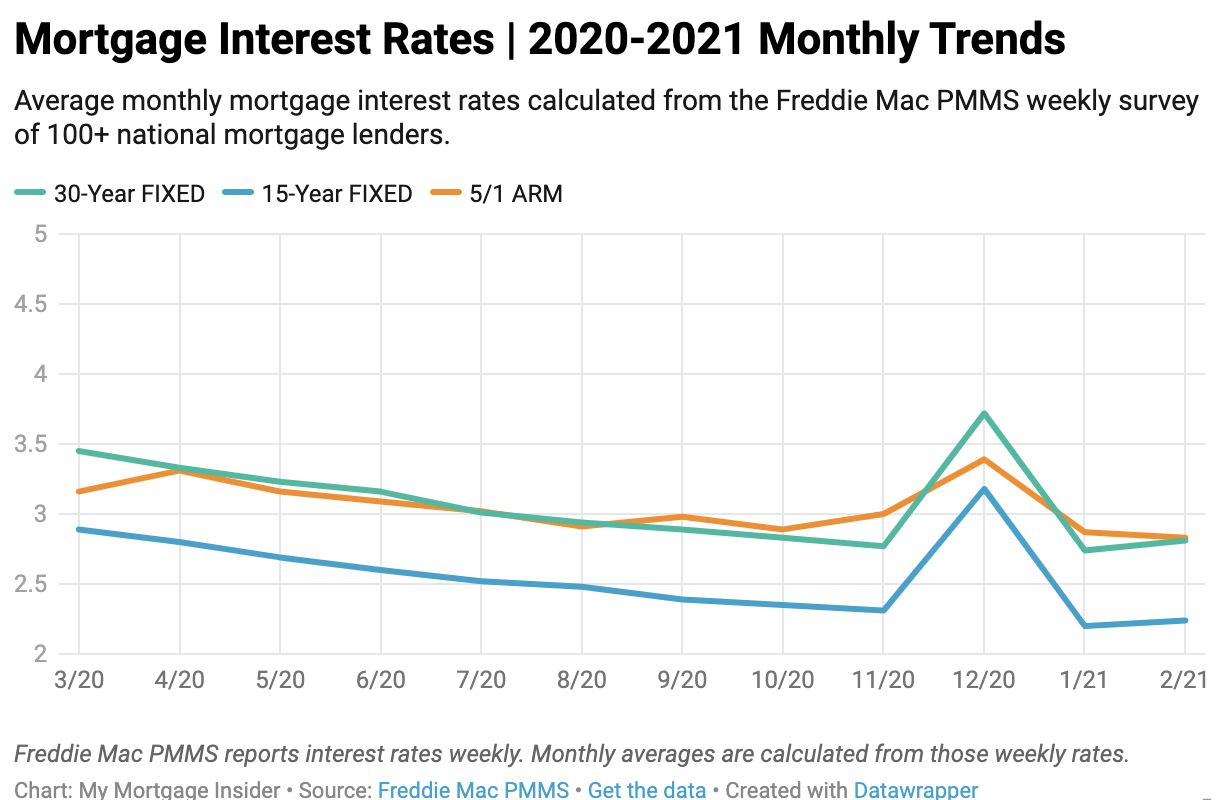
As of the current market cycle, mortgage rates have moved away from the historic lows seen during the early 2020s, transitioning into a period of stabilization and heightened sensitivity to inflation data. Understanding where these rates stand today requires a look at both the macroeconomic forces at play and the microeconomic factors that determine what an individual lender will offer a specific borrower.
Understanding the Current Mortgage Landscape
The mortgage market does not exist in a vacuum. It is deeply tethered to the broader bond market and the monetary policy decisions made by central banks, most notably the Federal Reserve in the United States. While the Federal Reserve does not directly set mortgage rates, its influence over the federal funds rate creates a ripple effect that dictates the cost of borrowing across the entire economy.
The Impact of Central Bank Policies
When the Federal Reserve adjusts the federal funds rate—the rate at which banks lend to one another overnight—it changes the “cost of money.” In an effort to combat inflation, central banks often raise these rates to slow down spending. For mortgage lenders, this means their own borrowing costs increase, which they pass on to consumers in the form of higher mortgage interest rates. Conversely, when the economy slows and inflation is under control, the Fed may lower rates to stimulate borrowing and investment, leading to more favorable mortgage terms for homebuyers.
The Role of the 10-Year Treasury Yield
For those tracking mortgage trends, the 10-year Treasury yield is often a more accurate daily barometer than the federal funds rate. Traditionally, there is a strong correlation between the yield on the 10-year Treasury note and the interest rate on a 30-year fixed-rate mortgage. Lenders typically price mortgages at a “spread” above the Treasury yield to account for the risk and the administrative costs of the loan. When investors are nervous about the economy and flock to the safety of government bonds, yields drop, often pulling mortgage rates down with them. When optimism or inflation fears rise, yields climb, and mortgage rates follow suit.
Factors That Determine Your Personal Interest Rate
While national averages provide a benchmark, the rate you are quoted by a lender is highly personalized. Two neighbors buying identical houses at the exact same time might receive significantly different interest rate offers based on their financial profiles. Understanding these variables is essential for anyone looking to optimize their home-buying strategy.
Credit Score: The Ultimate Lever
In the eyes of a mortgage lender, your credit score is the primary indicator of risk. Borrowers with “excellent” credit (typically 740 and above) are rewarded with the lowest available rates because they have a proven track record of managing debt responsibly. Those with “fair” or “poor” credit scores represent a higher risk of default, and lenders compensate for this risk by charging higher interest rates. Over the life of a 30-year loan, a borrower with a 760 credit score might save tens of thousands of dollars compared to a borrower with a 660 score.
Loan-to-Value (LTV) Ratios and Down Payments
The amount of skin you have in the game matters. The Loan-to-Value ratio represents the percentage of the home’s value that you are borrowing versus the amount you are paying upfront. A 20% down payment (resulting in an 80% LTV) is the industry standard for securing competitive rates and avoiding Private Mortgage Insurance (PMI). If a borrower puts down less than 20%, the lender views the loan as riskier, often leading to a slightly higher interest rate or additional monthly costs.
Debt-to-Income (DTI) Considerations
Lenders also examine your Debt-to-Income ratio, which compares your total monthly debt payments to your gross monthly income. A high DTI suggests that you may struggle to make mortgage payments if your financial situation changes. To mitigate this risk, lenders may increase the interest rate or require a larger down payment to ensure the monthly obligation is manageable.
Fixed-Rate vs. Adjustable-Rate Mortgages: Which Is Better Now?
Choosing the right loan product is just as important as the timing of the market. The current interest rate environment often dictates whether a borrower should opt for the stability of a fixed-rate mortgage or the initial savings of an adjustable-rate mortgage (ARM).

The Security of Fixed Rates
The 30-year fixed-rate mortgage remains the gold standard for American homeowners. It provides a predictable monthly payment that never changes, regardless of how high inflation or market interest rates may climb in the future. In a rising-rate environment, locking in a fixed rate acts as a hedge against future volatility. For many, the peace of mind that comes with knowing their housing costs are set for the next three decades is worth the potentially higher initial rate compared to an ARM.
The Strategic Use of ARMs
Adjustable-rate mortgages offer a lower introductory interest rate for a set period—usually five, seven, or ten years. After this period, the rate adjusts annually based on current market indices. In a high-rate environment, an ARM can be a savvy financial tool for buyers who plan to sell the home or refinance before the introductory period ends. If market rates are expected to decline in the coming years, starting with a lower ARM rate and then refinancing into a fixed-rate loan when the market cools can be a highly effective way to manage cash flow.
Current Market Trends and Future Projections
Predicting the exact movement of mortgage rates is notoriously difficult, as they are susceptible to “black swan” events and sudden shifts in economic data. However, by observing current trends, we can glean insight into where the market is headed.
Navigating Volatility
We are currently in a period characterized by “data dependency.” This means that every monthly report on consumer prices, employment numbers, and retail sales can cause mortgage rates to fluctuate. If a jobs report comes in stronger than expected, suggesting the economy is “too hot,” rates may tick up on fears that the Fed will keep borrowing costs high. Conversely, signs of economic cooling can lead to immediate rallies in the bond market, bringing mortgage rates down.
When to Lock in Your Rate
Rate locking is a critical step in the mortgage process. Once you find a rate that fits your budget, a “lock” guarantees that rate for a specific period (usually 30 to 60 days) while your loan is processed. In a volatile market, waiting for a “bottom” that may never come can be a risky gamble. Professional financial advisors often suggest that if the current rate makes the home affordable and fits your long-term financial goals, locking it in is often the wisest move.
Strategies to Secure the Lowest Possible Rate
Even when national averages are high, there are tactical maneuvers borrowers can use to secure a more favorable deal.
Buying Down the Rate with Points
Mortgage points, or “discount points,” allow borrowers to pay an upfront fee to the lender at closing in exchange for a lower interest rate. One point typically costs 1% of the total loan amount and reduces the interest rate by about 0.25%. This is a long-term play; it requires an upfront investment, but it can result in significant savings over the life of the loan. This strategy is particularly effective for those who plan to stay in their homes for ten years or more.
Shopping Multiple Lenders
One of the most common mistakes homebuyers make is failing to shop around. Mortgage rates are not uniform across the industry. Credit unions, national banks, and online mortgage lenders all have different overhead costs and risk appetites. By obtaining Loan Estimates from at least three different lenders, borrowers can compare not only the interest rates but also the closing costs and origination fees. In many cases, a borrower can use a quote from one lender to negotiate a better deal with another.
Improving Your Financial Profile Before Applying
If you are not in a rush to buy, taking six months to a year to polish your financial profile can pay dividends. This includes paying down high-interest credit card debt to lower your DTI and ensuring there are no errors on your credit report. A jump of just 20 points in your credit score can sometimes move you into a new pricing tier, saving you thousands of dollars in interest.
Conclusion
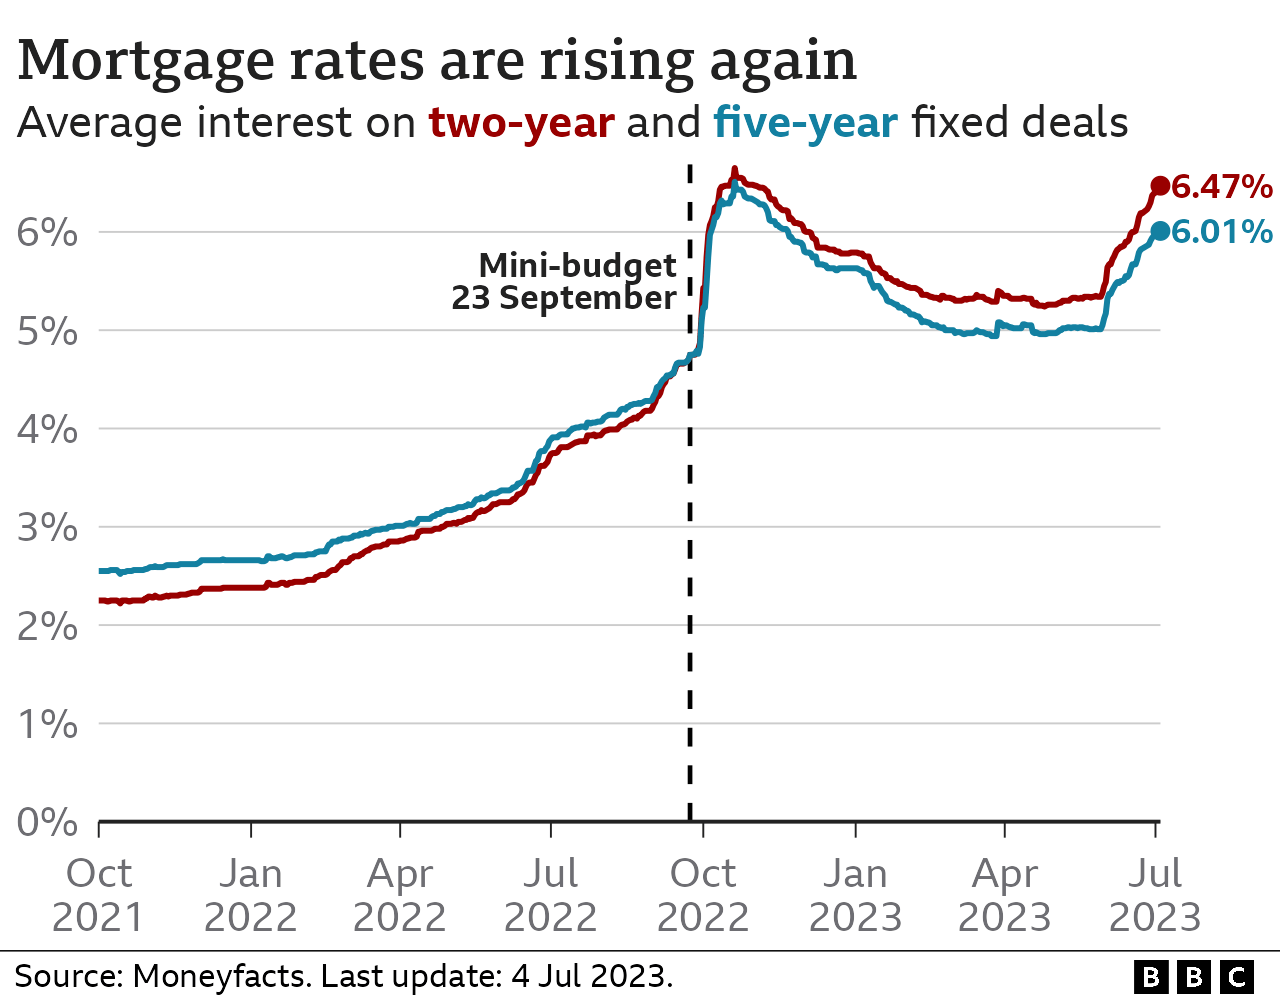
The current interest rate for a mortgage is a moving target, shaped by a complex interplay of global economic health and individual financial responsibility. While we may no longer be in the era of 3% interest rates, the current market still offers opportunities for those who are prepared and informed. By understanding the factors that drive rates, choosing the right loan product, and employing strategic tactics like rate shopping and buying points, you can navigate the mortgage landscape with confidence. In the end, a mortgage is more than just a loan; it is a fundamental component of your long-term financial strategy, and securing the best possible rate is a vital step toward building lasting wealth through homeownership.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.