
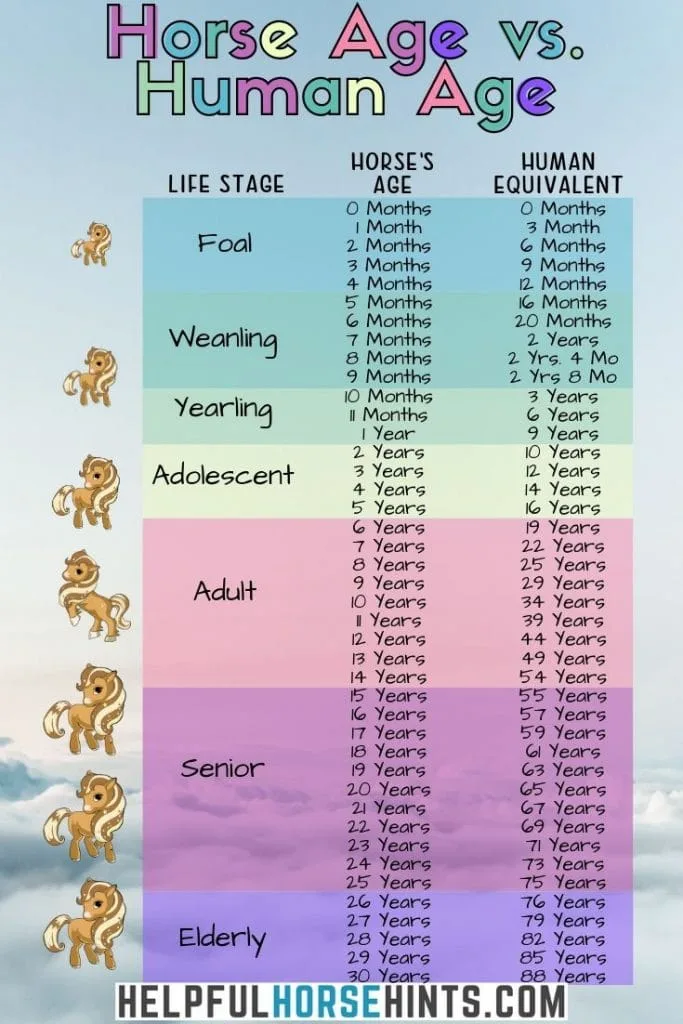
In the world of high-value assets, few investments require as much emotional and financial commitment as the purchase of a horse. Whether acquired for competitive sport, breeding, or personal recreation, a horse represents a significant capital outlay followed by decades of recurring operational expenses. Central to any robust financial plan involving equine ownership is a clear understanding of the asset’s “useful life.” While a biological horse may live for 25 to 30 years, the financial implications of that lifespan are complex, involving varying phases of productivity, maintenance costs, and eventual depreciation. Understanding the average life expectancy for a horse is not merely a matter of veterinary interest; it is the cornerstone of calculating return on investment (ROI) and managing long-term liabilities.
The ROI of Longevity: Defining the Equine Lifecycle
When analyzing the financial feasibility of a horse, investors must distinguish between biological life expectancy and “economic life expectancy.” While modern veterinary medicine has pushed the average lifespan of a horse into the late twenties and early thirties, their peak earning or performance years are considerably shorter.
The Peak Performance Window
For a performance horse—whether in dressage, show jumping, or racing—the period of maximum valuation typically occurs between the ages of 7 and 14. During this window, the horse’s physical maturity and training intersect to create the highest market value. From an investment perspective, this is the phase where capital appreciation is most likely. If a horse is purchased as a prospect (ages 3–5), the investor is betting on a decade of performance that will justify the initial purchase price and the ongoing cost of training.
The Maintenance and Sunset Phase
As a horse moves past age 15, its market value generally begins to decline, even if its utility remains high. This is the “depreciation phase.” Between ages 15 and 25, the owner transition from an appreciation-focused strategy to one centered on capital preservation or utility extraction (such as using the horse for lessons or lower-level competition). The final decade of a horse’s life—the “retirement phase”—represents a pure financial liability. With no further income-generating potential or competitive utility, the costs of boarding, farrier services, and geriatric veterinary care become a sunk cost that must be accounted for in the initial 30-year financial projection.
The Total Cost of Ownership (TCO) Over a 30-Year Horizon
To understand the financial weight of horse longevity, one must look at the Total Cost of Ownership (TCO). If a horse lives to the average age of 28, and it was purchased as a three-year-old, the owner is looking at a 25-year financial commitment.
Recurring Operational Expenses
The “cost of carry” for a horse is remarkably high compared to other asset classes. Minimum monthly expenses including boarding, feed, and basic hoof care can range from $600 to $3,000 depending on the region and the level of care. Over a 25-year period, a conservative average of $1,200 per month results in a lifetime maintenance cost of $360,000. This figure does not include specialized training, competition fees, or emergency veterinary interventions. When a horse lives beyond the expected average, reaching 32 or 35 years, the owner must be prepared for an additional $50,000 to $100,000 in unforeseen retirement costs.
The Escalating Costs of Geriatric Care
As horses age, their medical requirements become more specialized and expensive. Older horses are prone to conditions such as Equine Cushing’s Disease (PPID), arthritis, and dental issues that require expensive daily medications and frequent veterinary visits. A financial plan that fails to account for the “geriatric spike” in expenses during the final 20% of the horse’s life can lead to significant budgetary strain. Sophisticated investors treat these later years as a growing liability on their personal or business balance sheet, often setting aside a dedicated sinking fund to cover end-of-life care and eventual disposal or necropsy costs.
Risk Mitigation: Insurance and Mortality Coverage
Given the volatility of equine health and the high probability of injury, insurance is a mandatory component of the financial strategy. The average life expectancy is a statistical mean, but individual outcomes are highly variable.
Mortality and Major Medical Policies
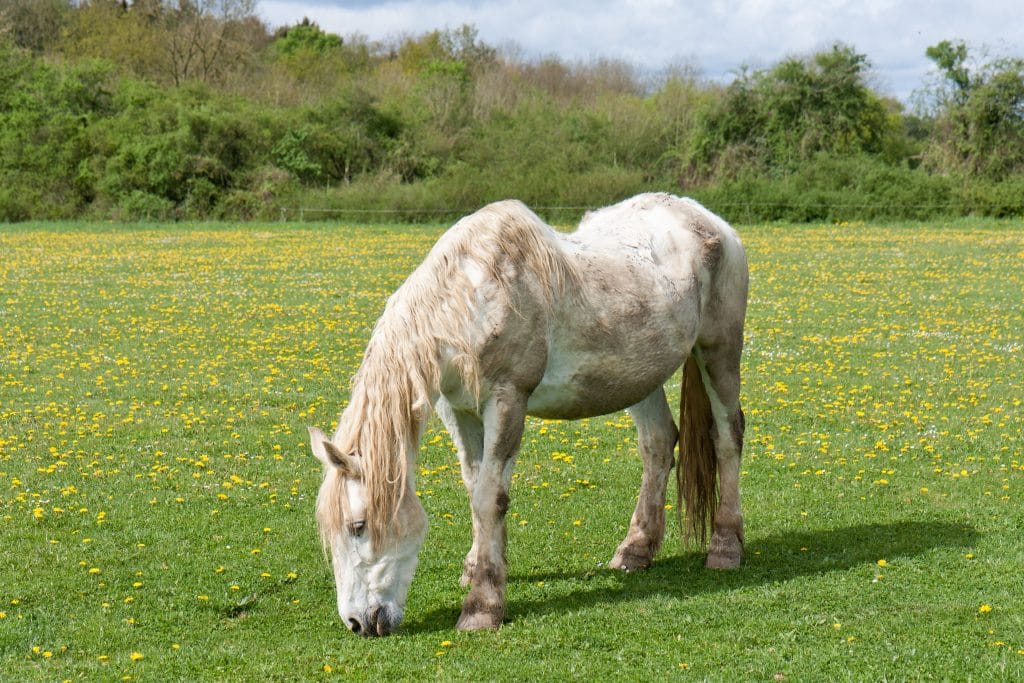
Most equine insurance providers offer mortality policies based on the horse’s fair market value. However, these policies become increasingly difficult and expensive to maintain as the horse ages. Typically, at age 15 or 20, insurance companies will either significantly raise premiums or reduce the scope of coverage, often excluding “colic” or “loss of use.” This shift forces the owner to move from an insured risk model to a self-insured model.
Calculating the Threshold for Major Medical Intervention
For a business-minded owner, every medical crisis requires a “repair vs. replace” analysis. If a 22-year-old horse requires a $10,000 colic surgery, the decision is no longer about the horse’s future performance, but about the ethics of care versus the remaining life expectancy. Understanding that the horse may only have 3–5 years of life remaining helps the owner make a calculated decision regarding the allocation of emergency funds.
Tax Implications and Business Structuring for Equine Assets
For those operating within the equine industry as a business—such as breeders, trainers, or professional stables—the horse’s life expectancy plays a vital role in tax planning and asset depreciation.
Section 179 and Accelerated Depreciation
Under current tax codes in many jurisdictions, horses used for business purposes can be depreciated over a set number of years (typically 3 to 7 years depending on the age and use of the horse). If a horse has a long life expectancy, the gap between its tax-depreciated value (which may hit zero) and its actual market value or utility value can create “hidden equity” on a business balance sheet. Conversely, if a horse dies prematurely, the business may be able to claim a casualty loss deduction, provided the asset was properly documented and valued.
Hobby Loss Rules and Financial Documentation
The Internal Revenue Service (IRS) and other tax authorities often scrutinize equine activities to determine if they are legitimate businesses or mere hobbies. Demonstrating a profit motive is essential. By mapping out the financial trajectory based on the horse’s life expectancy—including projected earnings during its prime and planned expenses during its retirement—an owner can provide a “pro forma” financial statement that supports the business status of the endeavor. This documentation is crucial for justifying the deduction of expenses against other income.
The Financial Exit Strategy: Re-homing and End-of-Life Logistics
An often-overlooked aspect of the equine investment lifecycle is the “exit strategy.” Because horses live for decades, an investor’s circumstances may change long before the horse reaches the end of its life.
Liquidity and Marketability
A horse is an illiquid asset. Selling a horse becomes progressively harder as it nears the end of its average life expectancy. An owner must decide whether to sell the horse while it still has significant market value (ages 10–12) or to hold the asset until its value reaches zero. Holding a horse into its late teens usually means committing to the full TCO until the horse’s death. This “hold to maturity” strategy requires a different capital allocation than a “flip” strategy.
Succession Planning and Final Costs
In the event that the owner predeceases the horse—a real possibility given a 30-year lifespan—the financial plan must include provisions for the horse’s continued care. This may involve equine trusts or specific bequests in a will. Furthermore, the final expenses of horse ownership, including euthanasia and carcass removal, can cost between $500 and $2,000 depending on the location. While these are small figures compared to the lifetime TCO, they are part of the total financial picture that must be managed.
Conclusion: Longevity as a Financial Metric
The average life expectancy for a horse is a critical variable in the equation of equine ownership. For the savvy investor or business owner, a horse is not a one-time purchase but a long-term capital project with a 25-to-30-year duration. By understanding the phases of the equine lifecycle—from the high-growth “prospect” years to the high-maintenance “retirement” years—owners can build a financial framework that accounts for escalating costs, tax benefits, and risk mitigation. In the final analysis, managing a horse’s life expectancy is about more than just animal husbandry; it is about the disciplined management of a unique and enduring financial asset.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.