
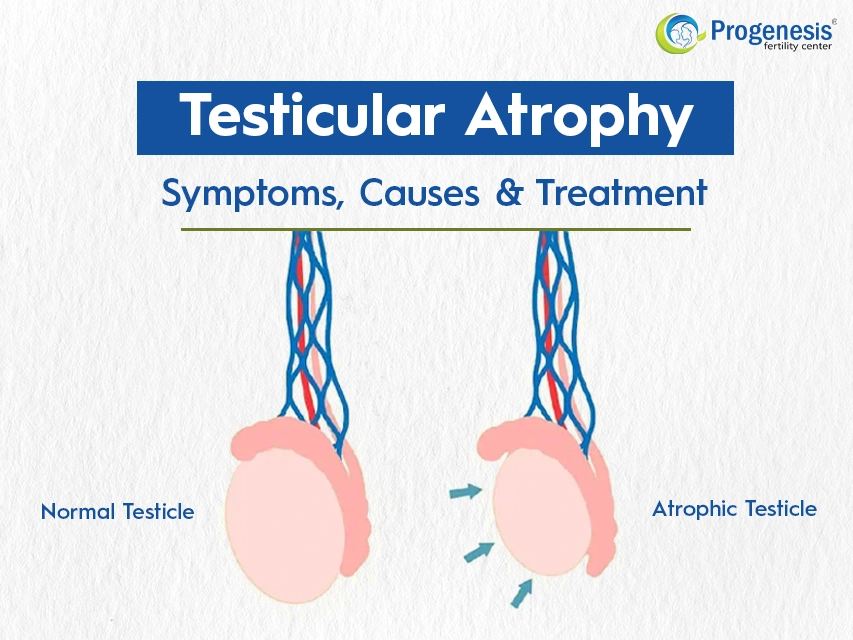
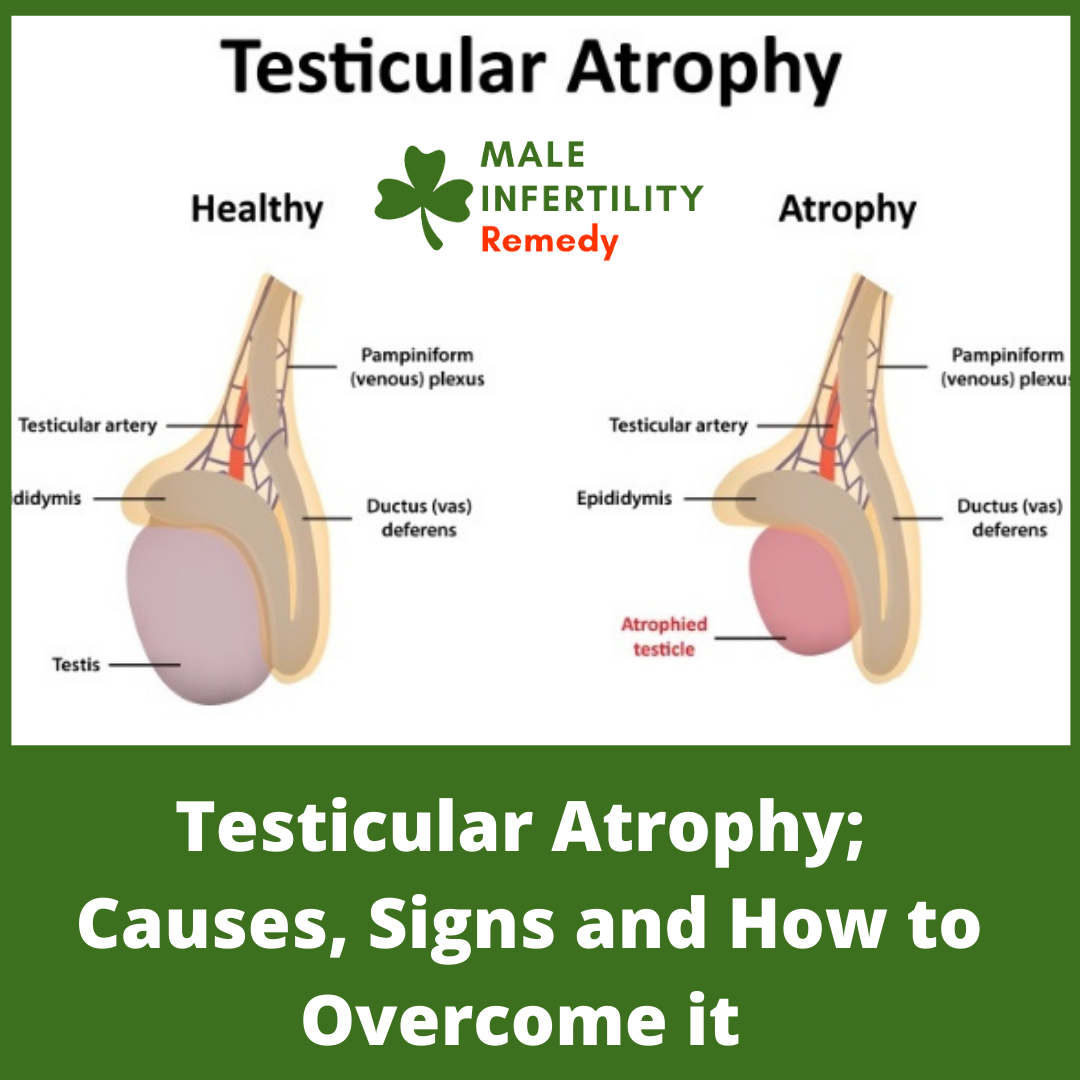
Testicular atrophy, a medical condition characterized by the shrinking of one or both testicles, carries a range of health implications that are well-documented in medical literature. While the physical and psychological toll on individuals is significant, the financial dimensions of managing and living with this condition are often underestimated and under-discussed. This article delves into the economic impact of testicular atrophy, exploring the direct and indirect costs, insurance considerations, and the broader financial planning strategies essential for those affected. Understanding the financial landscape is crucial for navigating the challenges posed by this condition, transforming a solely medical concern into a comprehensive financial planning consideration for individuals and their families.
The Hidden Costs of Diagnosis and Initial Management
The journey to understanding and addressing testicular atrophy often begins with a series of diagnostic procedures and initial consultations, each contributing to an accumulating financial burden. These early stages can be particularly challenging as individuals grapple with uncertainty while simultaneously incurring expenses.
Navigating Diagnostic Procedures and Consultations
Identifying testicular atrophy and its underlying causes requires a structured diagnostic process, which involves various medical professionals and tests. The initial step typically involves consultations with primary care physicians, followed by referrals to specialists such as urologists or endocrinologists. Each visit incurs consultation fees, which can vary widely depending on the physician’s specialty, location, and whether they are in-network with an individual’s insurance plan.
Beyond consultations, a battery of diagnostic tests is usually necessary. These commonly include:
-
Ultrasound: To assess the size, structure, and blood flow of the testicles, helping to confirm atrophy and identify potential causes like varicoceles or tumors. Costs can range from a few hundred to over a thousand dollars, depending on the facility and insurance coverage.
-
Blood Tests: To measure hormone levels (e.g., testosterone, FSH, LH), which are critical for understanding endocrine function. These tests are essential for identifying hormonal imbalances that might contribute to or result from testicular atrophy. The cost of a comprehensive hormone panel can also be substantial.
-
Semen Analysis: Though not always directly diagnostic of atrophy, it can be ordered if fertility concerns are present, adding another layer of expense.
For many, the process might involve multiple rounds of testing or seeking second opinions, each adding to the out-of-pocket expenses before a definitive diagnosis or treatment plan is established.
Early Treatment Pathways and Their Price Tags
Once diagnosed, the initial treatment strategy for testicular atrophy depends heavily on its root cause. Common early interventions, particularly for cases related to hormonal imbalances, include medication, which can lead to recurring costs.
One prevalent treatment approach is Hormone Replacement Therapy (HRT), especially if low testosterone (hypogonadism) is identified. HRT can involve various forms, such as injections, gels, patches, or oral medications. While potentially effective in managing symptoms related to low testosterone, the cost of these medications can be a significant ongoing expense:
-
Injections: Often the most cost-effective per dose but require regular administration (weekly or bi-weekly), leading to pharmacy costs and potential administration fees if done by a healthcare professional.
-
Gels/Patches: Convenient but can be more expensive on a monthly basis.
-
Oral Medications: Less common for long-term testosterone replacement due to liver concerns, but might be used for specific underlying conditions.
Beyond direct medication costs, individuals might incur expenses for lifestyle interventions suggested to support overall health and potentially mitigate symptoms. These could include consultations with nutritionists, exercise physiologists, or even therapists if the psychological impact of atrophy (e.g., body image issues, depression) necessitates mental health support. Each of these services, while beneficial for well-being, contributes to the overall financial burden.
Long-Term Financial Implications and Ongoing Care
Testicular atrophy is often a condition that requires ongoing management rather than a one-time cure, leading to sustained financial commitments over many years. This long-term perspective highlights the importance of understanding recurring costs and navigating the complexities of health insurance.
Sustaining Treatment: Recurring Expenses
For individuals on long-term treatment plans, especially those involving hormone replacement therapy, recurring expenses become a permanent fixture in their financial planning. This includes the continuous cost of prescribed medications, which can fluctuate based on pharmaceutical pricing, insurance formularies, and generic vs. brand-name availability.
Beyond medication, ongoing monitoring is essential to ensure treatment efficacy and to manage potential side effects. This involves:
-
Regular follow-up visits with specialists (urologologists, endocrinologists) to assess progress, adjust dosages, and discuss any new symptoms.
-
Periodic blood tests to monitor hormone levels and other health markers, ensuring the treatment is safe and effective. These tests, while routine, still come with associated lab fees and collection charges.
-
Management of related conditions: Testicular atrophy can sometimes be a symptom or contribute to other health issues. For example, long-term hypogonadism can increase the risk of osteoporosis, requiring additional tests (like bone density scans) and potentially new medications, further expanding the financial outlay.
Insurance Coverage and Out-of-Pocket Maximums
The role of health insurance is paramount in mitigating the financial impact of chronic conditions like testicular atrophy, yet navigating its intricacies can be a challenge. Understanding one’s plan—including deductibles, co-pays, co-insurance, and out-of-pocket maximums—is critical.
-
Deductibles: The amount an individual must pay out of pocket before insurance coverage kicks in for most services. High-deductible plans, while often having lower monthly premiums, can result in significant initial expenses for diagnostic and treatment phases.
-
Co-pays and Co-insurance: Fixed fees for doctor visits or a percentage of the cost of a service after the deductible is met. These add up over time, especially with frequent specialist visits and ongoing therapy.
-
Out-of-Pocket Maximums: The absolute maximum an individual will pay for covered services in a given year. While offering a ceiling to expenses, reaching this maximum can still represent a substantial annual cost.
Furthermore, insurance formularies for prescription drugs can change annually, potentially affecting the cost of HRT or other necessary medications. Prior authorizations may also be required for certain treatments, adding administrative hurdles and potential delays in care, which can sometimes lead to additional costs if temporary alternative solutions are needed. Denials for coverage, while frustrating, necessitate appeals processes that can be time-consuming and require additional effort, sometimes involving legal or advocacy support.
The Economic Burden on Families
The financial strain of testicular atrophy extends beyond the individual to impact the entire family unit. Indirect costs, often overlooked, can significantly strain household budgets and require careful planning. These include:
-
Time Off Work: Both the patient and potentially a family member may need to take time off work for appointments, diagnostic tests, or recovery periods, leading to lost wages or vacation days.
-
Travel and Accommodation: For individuals living in rural areas or needing specialized care, travel expenses to larger medical centers, including fuel, parking, and potentially accommodation, can add up quickly.
-
Caregiving Costs: In some severe cases, or if other health issues arise, family members may take on caregiving roles, which can impact their own employment or lead to expenses for professional care.
The cumulative effect of these direct and indirect costs can divert funds from other essential family needs, such as education savings, retirement planning, or even daily living expenses, highlighting the broad economic burden of chronic health conditions.
Testicular Atrophy’s Impact on Income and Productivity
Beyond the direct costs of medical care, testicular atrophy can exert a significant influence on an individual’s ability to earn income and maintain productivity, leading to broader economic consequences.
Affecting Work Performance and Earning Potential
The symptoms associated with testicular atrophy and its underlying causes, particularly low testosterone, can profoundly affect an individual’s professional life. These symptoms include:
-
Fatigue and Low Energy: Persistent tiredness can reduce concentration, stamina, and overall productivity at work.
-
Mood Disturbances: Depression, irritability, and anxiety are common and can impair decision-making, interpersonal interactions, and the ability to cope with job stress.
-
Reduced Libido and Erectile Dysfunction: While primarily personal, these issues can contribute to psychological distress, impacting self-esteem and indirectly affecting professional engagement.
-
Pain or Discomfort: If atrophy is accompanied by pain (e.g., from an underlying varicocele), it can make prolonged sitting or physically demanding tasks difficult, leading to discomfort and distraction.
Collectively, these symptoms can lead to decreased work performance, missed workdays, reduced work hours, or even the necessity to change careers if the current occupation becomes untenable. This directly impacts an individual’s earning potential and long-term career progression, creating a ripple effect on their financial stability.
Navigating Workplace Accommodations and Disability Benefits
For individuals whose work is significantly impacted, understanding workplace accommodations and available disability benefits becomes crucial.
-
Workplace Accommodations: Depending on the severity and nature of symptoms, employers may be legally required to provide reasonable accommodations under disability laws (e.g., Americans with Disabilities Act in the US). These might include flexible work schedules, modified duties, or ergonomic adjustments to the workspace. Navigating these discussions requires clear communication and understanding of one’s rights and the employer’s obligations.
-
Disability Benefits: If the condition severely limits an individual’s ability to work, exploring short-term and long-term disability insurance options is essential.
-
Short-term disability (STD) can provide income replacement for a limited period, often a few months, typically covering temporary incapacitation.
-
Long-term disability (LTD) offers income replacement for an extended period, potentially years or even until retirement, for conditions that permanently prevent an individual from working. Eligibility criteria are strict, and the application process can be complex and lengthy.
-
-
Government Assistance Programs: In some regions, government programs (e.g., Social Security Disability Insurance in the US) may provide financial assistance for individuals with severe, long-term disabilities that prevent them from engaging in substantial gainful activity. These programs often have strict medical eligibility requirements and lengthy application processes.
Accessing these benefits requires meticulous record-keeping, medical documentation, and often, professional assistance to navigate the application processes successfully.
Proactive Financial Planning and Support Systems
Given the potential long-term financial ramifications of testicular atrophy, proactive financial planning is not merely advisable but essential. Building a robust financial safety net and leveraging available support systems can significantly alleviate economic stress.
Building a Financial Safety Net
A cornerstone of financial resilience for anyone facing chronic health conditions is a well-structured financial safety net.
-
Emergency Funds: Beyond general emergency savings, it’s prudent to earmark a portion of funds specifically for health-related emergencies or unexpected medical costs not covered by insurance. This could involve setting aside several months’ worth of potential out-of-pocket medical expenses.
-
Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs): These tax-advantaged accounts are invaluable for managing healthcare costs.
-
HSAs: Available to those with high-deductible health plans, HSAs offer a triple tax advantage (tax-deductible contributions, tax-free growth, tax-free withdrawals for qualified medical expenses). Funds roll over year to year and are portable, making them excellent long-term savings vehicles for medical costs.
-
FSAs: Offered through employers, FSAs allow pre-tax contributions for healthcare expenses, though funds typically must be used within the plan year (with some carryover exceptions). They are beneficial for predictable annual medical costs.
-
-
Critical Illness Insurance or Supplemental Health Policies: While not a substitute for comprehensive health insurance, these policies can provide a lump-sum payment upon diagnosis of specific critical illnesses (though testicular atrophy itself may not always be covered unless it leads to a broader, covered condition like cancer). Supplemental policies can also help cover deductibles, co-pays, and other out-of-pocket expenses.
Seeking Financial Guidance and Resources
Navigating the financial complexities of a chronic condition can be overwhelming. Professional guidance and community resources can offer invaluable support.
-
Financial Planners Specializing in Healthcare Costs: Some financial advisors specialize in planning for healthcare expenses, particularly for individuals with chronic conditions. They can help integrate medical costs into broader financial plans, including retirement and estate planning.
-
Patient Advocacy Groups and Non-Profit Organizations: Many organizations are dedicated to supporting individuals with specific medical conditions. While not always directly offering financial aid for testicular atrophy specifically, they can provide information on patient assistance programs for medications, connect individuals with support networks, and offer guidance on navigating healthcare systems.
-
Online Resources and Prescription Assistance Programs: Pharmaceutical companies often have patient assistance programs (PAPs) to help eligible individuals afford high-cost medications. Websites and non-profit organizations often compile lists of these programs and provide information on generic drug alternatives, discount cards, and other ways to reduce prescription costs. Hospital financial aid departments can also be a resource for managing large medical bills.
By actively engaging in proactive financial planning and utilizing available support systems, individuals affected by testicular atrophy can build greater economic resilience and reduce the stress associated with managing the condition’s financial implications.
Conclusion
Testicular atrophy, while fundamentally a medical condition, casts a long shadow over an individual’s financial well-being. From the initial diagnostic tests and ongoing treatment costs to its potential impact on income and long-term financial stability, understanding the monetary aspects is crucial for comprehensive management. Proactive financial planning, including building an emergency fund, utilizing tax-advantaged health savings accounts, and exploring supplemental insurance, becomes indispensable. Moreover, seeking professional financial advice and leveraging patient advocacy resources can significantly mitigate the economic burden. By addressing the financial dimension head-on, individuals can navigate the challenges of testicular atrophy with greater confidence, ensuring that health management does not disproportionately compromise their financial future.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.