
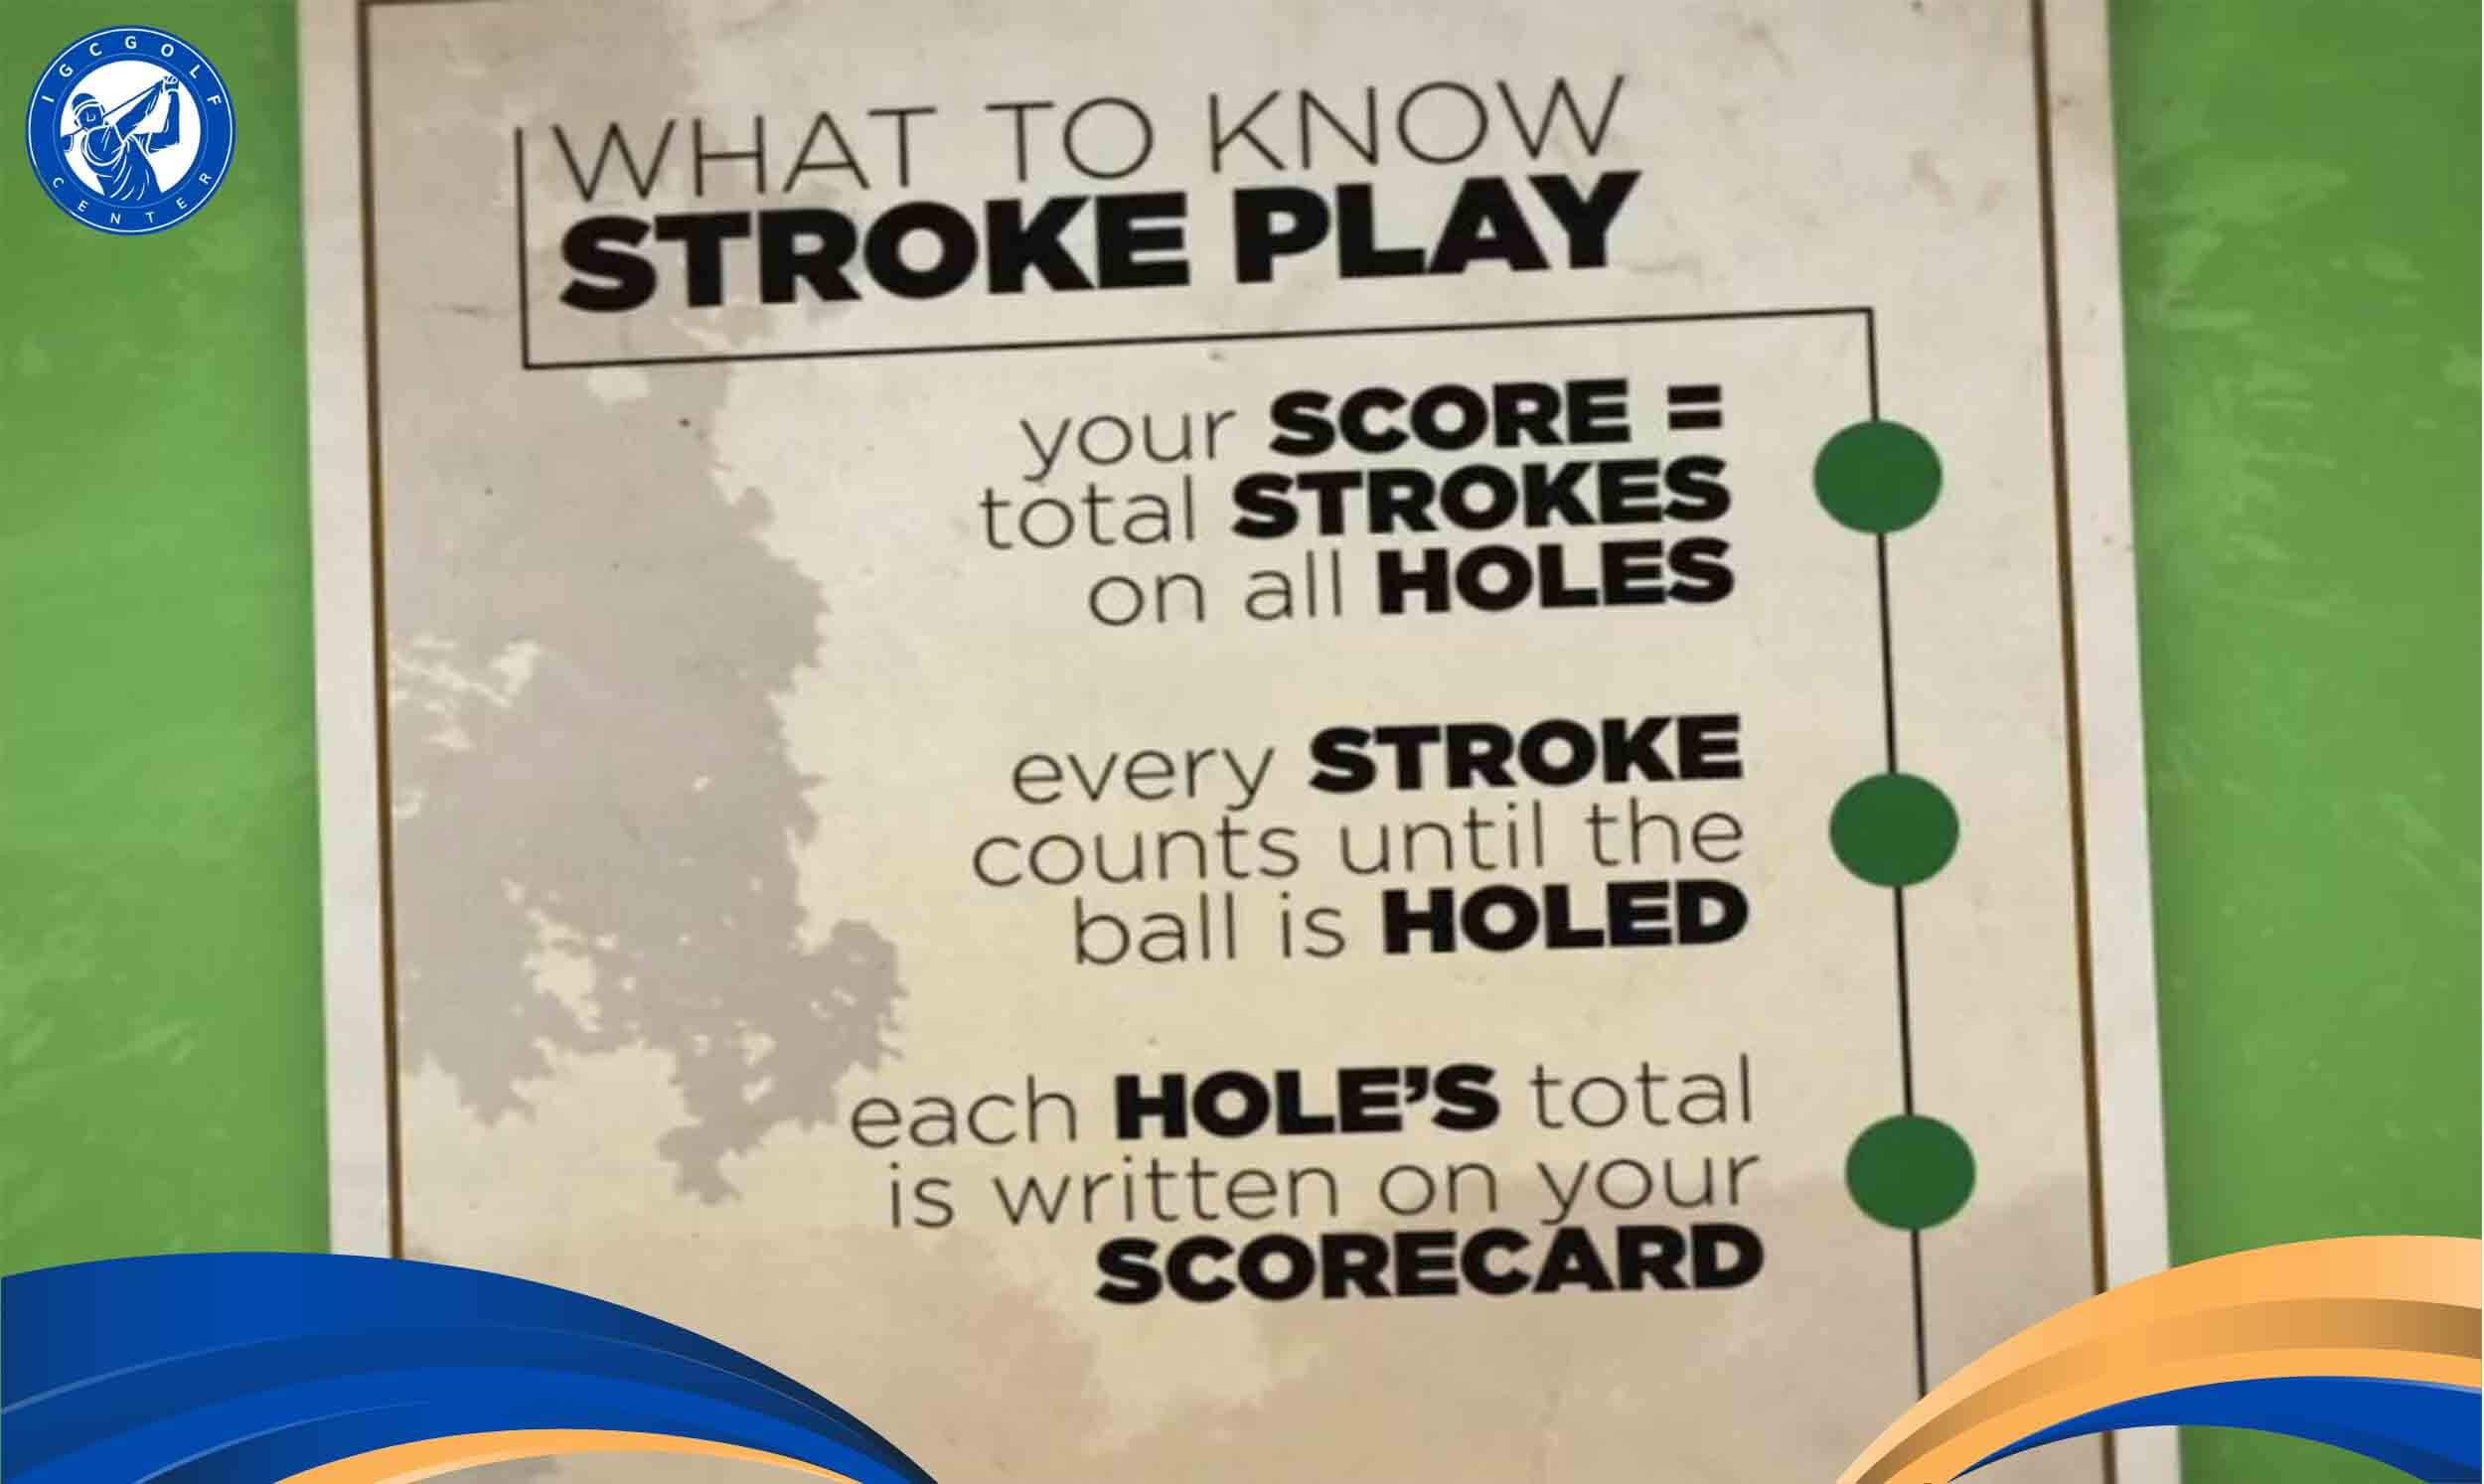
In the world of competitive golf, stroke play is the ultimate test of consistency. Unlike match play, where a player only needs to win individual holes to succeed, stroke play requires the athlete to count every single shot taken over the course of a round. One bad hole can ruin a scorecard, but a series of disciplined, average shots can lead to a championship. When translated to the world of personal finance, investing, and corporate strategy, “Stroke Play” becomes a powerful metaphor for cumulative success. It is a philosophy that prioritizes the total aggregate result over individual tactical wins.
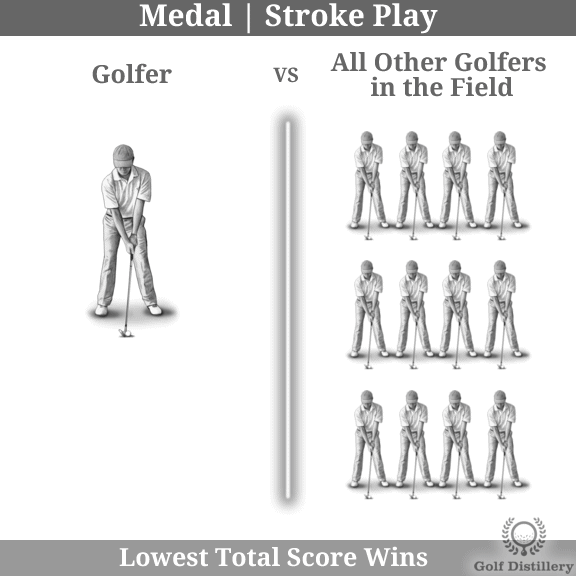
In a financial context, practicing stroke play means acknowledging that every dollar spent, every fee paid, and every percentage point earned contributes to a final “score”—your net worth or your company’s bottom line. By understanding the mechanics of stroke play in money management, investors and business leaders can move away from high-risk “match play” mentalities and toward a sustainable, precision-based approach to wealth.
Defining Stroke Play in the Context of Wealth Management
At its core, financial stroke play is the discipline of aggregate performance. In many investment circles, there is a preoccupation with “beating the market” on a short-term basis. This is the financial equivalent of match play: trying to win a specific “hole” (a quarter or a fiscal year) against a specific opponent (an index or a competitor). While winning a single match is satisfying, it does not guarantee long-term solvency or wealth accumulation.
The Shift from Match Play to Stroke Play in Investing
The match play mentality often leads to emotional decision-making. If an investor feels they are “down” compared to a benchmark, they may take excessive risks to catch up. In contrast, an investor practicing stroke play understands that their only true opponent is the cumulative cost of their decisions. They focus on the internal rate of return (IRR) over decades rather than the headlines of a single month.
This shift requires a transition from seeking “alpha”—the excess return over a benchmark—to seeking “efficiency.” In stroke play, a “par” performance that is maintained consistently over 30 years will almost always outperform a strategy that alternates between spectacular “birdies” and catastrophic “triple bogeys.” The goal is to minimize the outlier events that drag down the average.
Why Cumulative Accuracy Trumps Short-Term Gains
In finance, the math of loss is non-linear. If a portfolio loses 50% of its value, it requires a 100% gain just to return to the break-even point. This is the ultimate lesson of stroke play. By avoiding the “big miss,” an investor keeps their score low. High-net-worth individuals rarely build their fortunes through a single “lucky” trade; they build it by ensuring that their “strokes”—their capital allocations—are consistently productive and protected from significant downside.
Applying Stroke Play Principles to Corporate Finance
For businesses, stroke play is synonymous with operational efficiency and disciplined capital allocation. In a corporate environment, a company might “win” a high-profile contract (a match play win), but if the cost of servicing that contract is too high, their total “stroke count” for the year will suffer. Sustainable businesses are those that treat every line item on the P&L statement as a stroke that must be optimized.
Cost Management as a Precision Exercise
In a stroke play financial model, cost management is not about drastic, one-time cuts. Instead, it is about the “marginal gains” philosophy. Just as a golfer works to shave half a stroke off their putting average, a CFO looks to shave basis points off their cost of capital or percentage points off their operational overhead.
When a company operates with a stroke play mindset, they prioritize processes that are repeatable and scalable. They look at the “all-in” cost of a project, including opportunity costs and long-term maintenance. This prevents the “vanity project” trap, where a business pursues a flashy initiative that looks good in a press release but negatively impacts the aggregate financial health of the organization.
The “Total Score” Mentality in Business Operations
The total score in business is the free cash flow. Every decision made by management—from hiring a new executive to investing in R&D—is a stroke that either adds to or subtracts from that final number. Companies that master this realize that a series of small, disciplined decisions often outweighs a single “transformational” merger or acquisition. By focusing on the total score, leadership can remain objective, avoiding the ego-driven traps of trying to “out-compete” rivals in ways that do not actually build shareholder value.
Stroke Play and Personal Finance: Building an Efficient Portfolio
For the individual investor, stroke play is the ultimate tool for retirement planning and wealth preservation. It shifts the focus from “What is the hottest stock right now?” to “How can I reduce the total number of strokes between me and my financial goals?” In personal finance, these “strokes” often take the form of taxes, management fees, and inflation.
Tax Efficiency: Reducing the Cost of Every Transaction
Taxes are often the highest “score” an investor pays. A stroke play strategy involves utilizing tax-advantaged accounts (like 401(k)s or IRAs) and employing tactics like tax-loss harvesting. In this framework, every dollar saved in taxes is a stroke removed from your total score.
If two investors both earn a 7% annual return, but one pays 1% in annual fees and 15% in capital gains taxes while the other uses low-cost index funds in a tax-shielded account, the difference in their “final score” over thirty years will be hundreds of thousands, if not millions, of dollars. The stroke play investor wins not because they picked better stocks, but because they played a more efficient game.
Compound Interest and the “Low Score” Strategy
Compound interest is the wind at the back of a stroke play investor. However, compounding works both ways. High-interest debt is a series of penalty strokes that compound against you. A stroke play approach to personal finance prioritizes the elimination of high-interest debt because it represents a guaranteed “bogey” on the financial scorecard. By clearing the path of these negative strokes early, the investor allows the positive strokes of equity growth to compound uninterrupted.
Tools and Metrics to Master Your Financial Stroke Play
To play the game effectively, you must keep an accurate scorecard. In the modern financial era, this means leveraging technology and data analytics to track every movement of capital. You cannot manage what you do not measure, and in stroke play, every measurement counts.
Data Analytics for Performance Tracking
Modern financial tools allow for a granular view of spending and investment performance. Using apps that aggregate net worth, track expense ratios, and analyze asset allocation provides the “real-time yardage” needed to make informed decisions. A stroke play investor looks at their “weighted average cost of capital” even for personal purchases. They use data to identify where “leakage” is occurring—those small, recurring expenses that, like a persistent slice in a golf swing, add unnecessary strokes to the total over time.
Risk Mitigation and the Margin for Error
In professional stroke play, the best players aren’t necessarily those who hit the longest drives; they are the ones who stay out of the bunkers and water hazards. In finance, this translates to risk management. Diversification is the “safe play” to the middle of the green. It might not result in a “hole-in-one” (a 1000% return on a single crypto asset), but it ensures that you don’t “post a 10” on a single hole (lose your entire nest egg).
Building a “margin of safety”—a concept popularized by Benjamin Graham—is a quintessential stroke play move. It involves buying assets at a discount to their intrinsic value, providing a cushion that protects the total score even when things go wrong.
Transitioning Your Strategy: From Tactical Wins to Aggregate Success
Mastering stroke play in the financial realm requires a psychological shift. It demands patience, a high tolerance for boredom, and a relentless focus on the long term. While the “match play” of day trading or chasing the latest trend offers immediate dopamine hits, it rarely leads to the lowest “score” over a lifetime.
To adopt a stroke play strategy, start by auditing your current financial “swing.” Identify the high-fee funds, the unnecessary subscriptions, and the tax inefficiencies that are bloating your score. Then, establish a disciplined routine of automated savings and low-cost investing.
In the end, the winner of the financial game is not the person who had the single most impressive “shot,” but the one who navigated the entire course with the fewest errors. By treating your money as a game of stroke play, you ensure that every move you make is calculated, efficient, and directed toward the ultimate goal of long-term financial freedom. Consistency, not brilliance, is the key to a championship scorecard.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.