
The phrase “what is RDW high in a blood test” typically initiates a medical inquiry into one’s health. However, beyond the clinical implications, understanding this particular blood marker — Red Cell Distribution Width (RDW) — can unveil critical insights into one’s financial health, particularly concerning future medical expenses, insurance considerations, and long-term financial planning. In an era where healthcare costs are a significant financial burden for many, integrating health literacy with financial acumen is not just wise; it’s essential. This article delves into the financial implications of an elevated RDW, offering a strategic perspective on how this seemingly small health detail can inform robust financial management.

Understanding RDW: A Prerequisite for Prudent Financial Health Management
Before we can dissect the financial ramifications, a foundational understanding of what RDW represents is crucial. It’s not merely a medical statistic but a potential early warning signal that savvy financial planners should integrate into their broader risk management strategy.
Demystifying Red Cell Distribution Width (RDW)
Red Cell Distribution Width (RDW) is a parameter found in a standard complete blood count (CBC) test. It measures the variation in the size and volume of your red blood cells (anisocytosis). In simpler terms, it tells you how uniform your red blood cells are in size. A ‘normal’ RDW indicates that your red blood cells are relatively consistent in size. Conversely, a ‘high’ RDW means there’s a greater variation in the size of your red blood cells – some are much larger or much smaller than average.
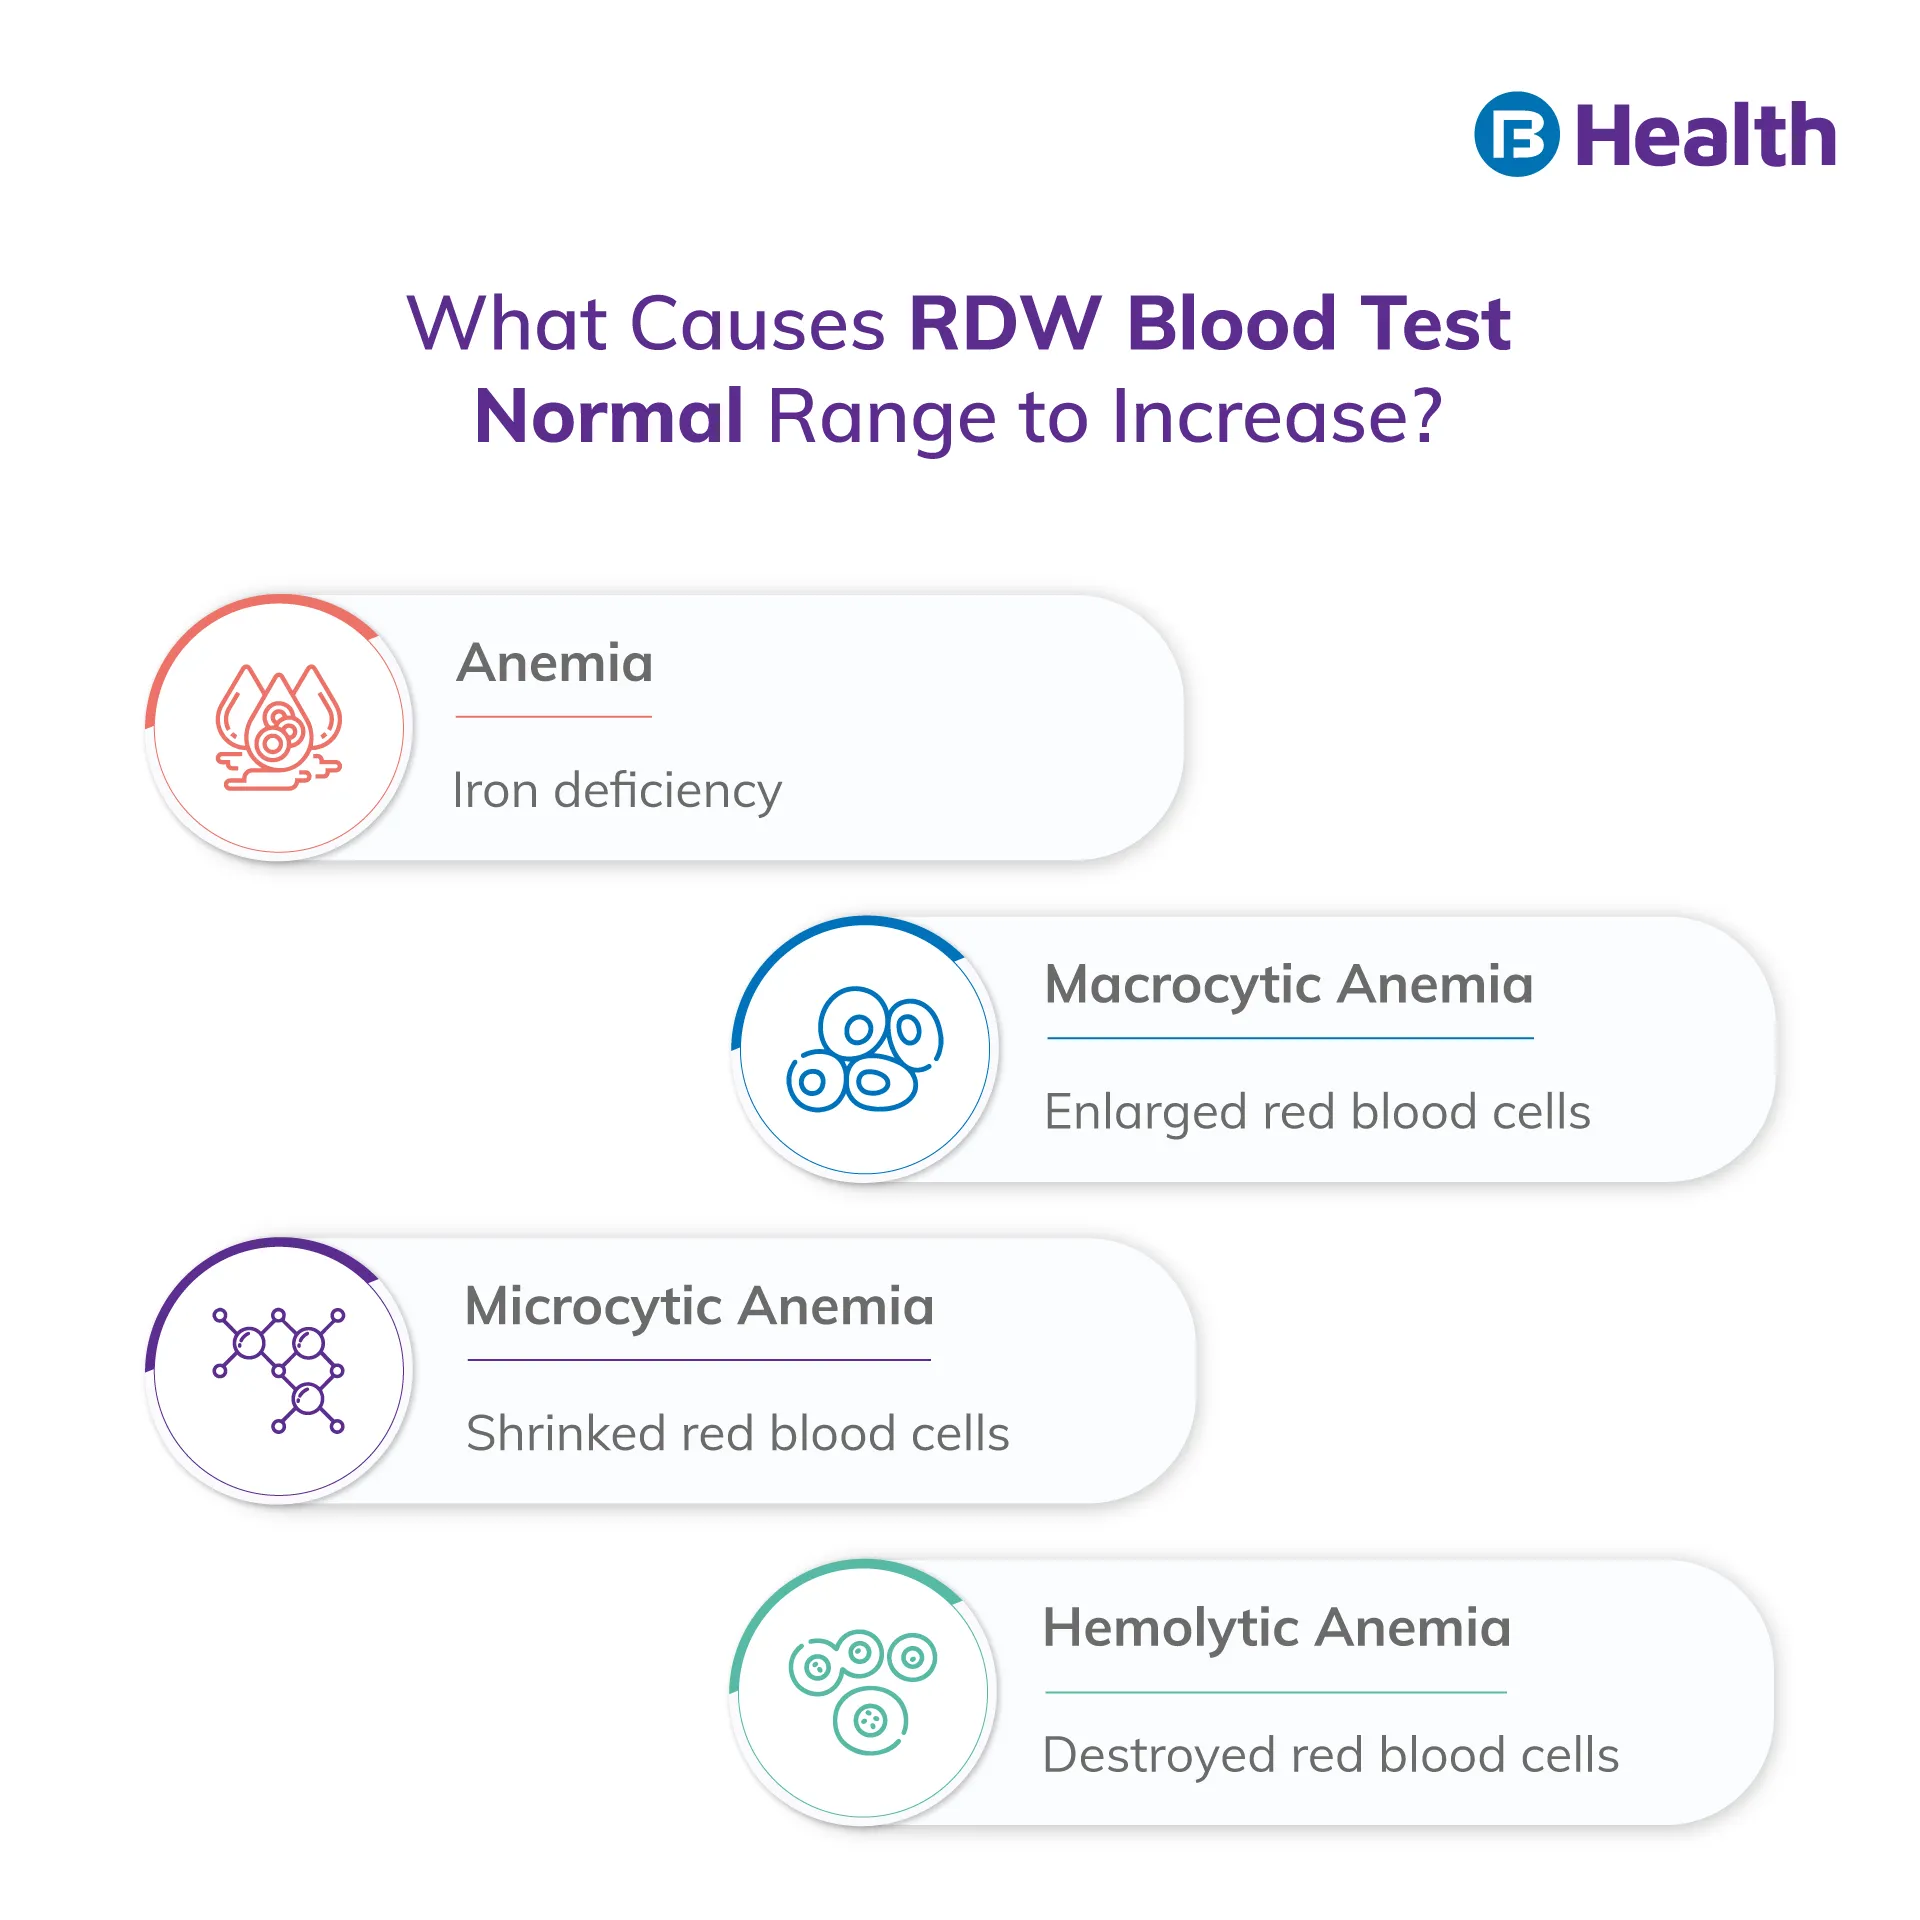
From a medical standpoint, a high RDW is not a diagnosis in itself but rather an indicator that prompts further investigation. It can be associated with various conditions, most commonly different types of anemia (iron deficiency, B12 deficiency, folate deficiency) but also chronic inflammation, liver disease, kidney disease, and even certain cardiovascular conditions. The financial implication here is immediate: a high RDW signals the potential need for further diagnostic tests, specialist consultations, and potentially long-term treatment, all of which come with a price tag. For a financially conscious individual, this initial RDW result should trigger a review of their current health insurance coverage and emergency fund status.
The Link Between High RDW and Potential Financial Liabilities
The presence of a high RDW isn’t just a clinical curiosity; it’s a marker that can be directly correlated with increased financial liabilities down the line. Many of the conditions indicated by an elevated RDW—such as chronic anemias or inflammatory diseases—often necessitate ongoing medical care. This isn’t just about a single doctor’s visit; it can involve a cascade of expenses:
-
Repeated blood tests: Monitoring blood counts, iron levels, vitamin B12, and folate.
-
Specialist visits: Consultations with hematologists, gastroenterologists, or other specialists depending on the underlying cause.
-
Medication costs: Daily supplements, iron infusions, B12 injections, or other prescribed drugs.
-
Lifestyle modifications: Dietary changes, which might involve purchasing specific (and sometimes more expensive) foods or supplements.
-
Potential procedures: In some cases, more invasive diagnostics like endoscopies or colonoscopies may be required to pinpoint the cause of an RDW anomaly.
Each of these steps translates directly into out-of-pocket expenses, even with robust health insurance. Deductibles, co-pays, and non-covered services can accumulate rapidly, underscoring the necessity of viewing a high RDW through a financial lens from the outset. Ignoring these early warning signs not only jeopardizes health but also risks significant unforeseen financial strain.
The Direct and Indirect Financial Impact of Elevated RDW Markers
An elevated RDW marker isn’t just a statistical anomaly on a lab report; it’s a precursor to a potential financial burden that can manifest in various forms, both obvious and subtle. Understanding these multifaceted impacts is crucial for comprehensive financial planning.
Calculating Direct Medical Costs: From Diagnostics to Treatment
The most immediate financial consequence of a high RDW is the direct cost associated with further medical investigation and subsequent treatment. As previously mentioned, a high RDW usually prompts additional diagnostic tests. These can range from more detailed blood panels to imaging studies (e.g., ultrasound, MRI) or even biopsies, each incurring its own charge. Specialist consultations, often necessary to interpret complex results and formulate a treatment plan, also add to the expense.
Once a diagnosis is made, the treatment phase begins, bringing with it costs for prescription medications, therapies, or even hospitalizations in more severe cases. Consider a scenario where iron deficiency anemia, often flagged by a high RDW, requires several rounds of intravenous iron infusions. Each infusion session, facility fees, and the cost of the medication itself can amount to hundreds or thousands of dollars. Even with insurance, co-pays, deductibles, and co-insurance can quickly deplete savings if one is unprepared. A high RDW, therefore, should be a trigger to review one’s health insurance policy, understand its coverage limits, and assess potential out-of-pocket maximums for the year.
The Opportunity Cost: Lost Income, Productivity, and Caregiving Burdens
Beyond direct medical expenses, a high RDW can signal underlying health issues that lead to significant indirect financial costs. Chronic fatigue, weakness, or other symptoms associated with conditions indicated by a high RDW can severely impact an individual’s ability to work. This can translate into:
-
Lost Wages: Missing work for doctor’s appointments, diagnostic tests, or recovery periods directly reduces income. For hourly workers or those without generous sick leave, this impact is immediate and substantial.
-
Reduced Productivity: Even when present at work, individuals suffering from chronic conditions may experience reduced focus, energy, and overall productivity, potentially affecting career advancement and earning potential over the long term.
-
Caregiving Burdens: If the individual with a high RDW is a primary caregiver for children or elderly parents, their illness can create a ripple effect, forcing other family members to take time off work or necessitating paid caregiving services, adding another layer of financial strain to the household.
These opportunity costs are often overlooked in financial planning but can be just as devastating as direct medical bills, quietly eroding wealth and financial stability over time.
Health Insurance: A Critical Financial Shield, Not Just a Policy
In the face of potential health challenges indicated by a high RDW, health insurance transcends its role as a mere policy document and becomes a crucial financial shield. It is the primary mechanism through which individuals can mitigate the substantial financial risks associated with medical expenses. However, simply having insurance is not enough; understanding its intricacies is paramount.
Individuals should meticulously review their insurance plan’s summary of benefits to grasp what is covered, to what extent, and under what circumstances. Key elements to scrutinize include:
-
Deductibles: The amount you must pay out-of-pocket before your insurance begins to cover costs.
-
Co-pays: Fixed amounts you pay for doctor visits or prescription drugs.
-
Co-insurance: A percentage of the cost of covered services that you pay after meeting your deductible.
-
Out-of-pocket maximums: The cap on the total amount you will have to pay for covered medical expenses in a given year.
Understanding these components can help estimate potential costs associated with investigating and treating conditions related to a high RDW. For instance, if a high RDW leads to chronic treatment, hitting the out-of-pocket maximum might become a reality, which, while providing a ceiling, still represents a significant upfront cost that needs to be budgeted for. Furthermore, individuals should be aware of in-network versus out-of-network costs, as utilizing out-of-network providers can dramatically increase personal financial responsibility. Proactive engagement with one’s insurance provider to clarify coverage for specific tests or treatments triggered by a high RDW can prevent unwelcome financial surprises.
Proactive Financial Planning for Health Resilience
Recognizing the potential financial implications of a high RDW transforms this health marker into a critical data point for proactive financial planning. Building financial resilience against health challenges requires strategic foresight and the intelligent utilization of available financial tools.
Maximizing Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs)
Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs) are invaluable financial tools designed to help individuals save and pay for qualified medical expenses with tax advantages. For those facing or anticipating health issues like those indicated by a high RDW, maximizing these accounts is a shrewd financial move.
-
HSAs: Available to those with high-deductible health plans (HDHPs), HSAs offer a triple tax advantage: contributions are tax-deductible, earnings grow tax-free, and withdrawals for qualified medical expenses are tax-free. They are owned by the individual and can roll over year after year, making them excellent long-term savings vehicles for future medical costs, even into retirement. Funds can be used for deductibles, co-pays, prescriptions, and other eligible expenses arising from RDW-related investigations or treatments.
-
FSAs: Typically offered through employer-sponsored plans, FSAs allow employees to set aside pre-tax money from their paycheck for healthcare costs. While usually subject to a “use-it-or-lose-it” rule by the end of the plan year (though some plans offer a grace period or a small rollover amount), FSAs can be highly effective for managing known or anticipated medical expenses within a specific year, such as recurring specialist visits or medication costs for a chronic condition identified by a high RDW.
Strategically contributing the maximum allowable amounts to these accounts can significantly reduce the out-of-pocket burden associated with managing conditions highlighted by an elevated RDW, turning a health challenge into a manageable financial undertaking.
Budgeting for the Unexpected: Creating a Health Emergency Fund
Just as one plans for unexpected car repairs or job loss, creating a dedicated health emergency fund is a non-negotiable component of robust financial planning, especially when health markers like a high RDW suggest potential future medical needs. This fund serves as a crucial buffer against unforeseen medical expenses that even comprehensive insurance may not fully cover.
The size of this fund should be tailored to individual circumstances, taking into account factors like current health status, family history, and the specifics of one’s health insurance plan (e.g., the deductible and out-of-pocket maximum). A good starting point might be to aim for enough to cover at least your annual health insurance deductible and a few months’ worth of potential co-pays and prescription costs. For those with a high RDW, factoring in potential specialist fees, advanced diagnostic costs, and ongoing treatment expenses becomes even more critical. Separating this health emergency fund from a general emergency fund ensures that medical crises don’t derail other financial goals. Automated transfers from checking to a dedicated savings account can help build this fund steadily over time, offering peace of mind when health challenges inevitably arise.
Long-Term Financial Projections: Integrating Health Outcomes into Retirement Planning
The long-term implications of health conditions, often hinted at by early markers like a high RDW, extend far beyond immediate medical bills. They can significantly impact retirement planning and overall financial security in later life. Chronic diseases, which a high RDW might precede, often lead to increased healthcare spending in retirement, impacting the longevity of savings.
When formulating retirement projections, it’s vital to incorporate realistic estimates for healthcare costs. This includes potential long-term care needs, which are not typically covered by Medicare or standard health insurance. Conditions like chronic anemia or inflammatory diseases, if left unmanaged, can worsen over time, potentially leading to increased debilitation and a greater reliance on costly long-term care services (e.g., home healthcare, assisted living facilities). Financial advisors specializing in retirement planning often recommend factoring in a significant portion of retirement savings specifically for healthcare. Understanding your RDW and taking proactive health steps today can mitigate these future costs, ensuring that your financial nest egg isn’t prematurely depleted by health expenses in your golden years. Integrating discussions about health risks with your financial advisor can lead to more accurate and resilient long-term financial projections.
Investing in Wellness: A Strategic Financial Decision
In the realm of personal finance, the concept of “investment” typically refers to stocks, bonds, or real estate. However, perhaps the most undervalued investment is in one’s own health and wellness. For those monitoring markers like RDW, this perspective is particularly pertinent, framing preventative care not as an expense, but as a strategic financial decision with tangible returns.
The Economic Benefits of Preventative Care and Early Detection
Viewing preventative care and early detection through a financial lens reveals compelling economic benefits. Regular check-ups, screenings, and understanding your basic blood markers—including RDW—are analogous to routine maintenance for a valuable asset. Just as maintaining a car prevents costly breakdowns, investing in preventative health minimizes the likelihood of developing more severe, expensive conditions.
A high RDW, when detected early, serves as an alert to investigate underlying issues before they escalate. Addressing iron deficiency anemia, for example, early on through dietary changes or supplements is far less costly than managing severe, chronic anemia that might require intravenous therapy or even blood transfusions. The financial return on investment (ROI) for preventative care is substantial: a small expenditure on a yearly physical or follow-up blood tests can avert much larger expenses associated with advanced disease states, hospitalizations, or complex treatments. Furthermore, maintaining good health means less missed work, sustained productivity, and a higher quality of life, all of which have direct and indirect financial advantages.
Digital Financial Tools for Health-Related Expense Tracking and Management
In today’s digital age, a plethora of financial tools and apps can significantly aid in tracking and managing health-related expenses, especially when dealing with ongoing conditions or investigations indicated by a high RDW. These tools integrate seamlessly into the “Money” category by providing clarity and control over healthcare spending.
Many personal finance apps allow users to categorize expenses, making it easy to track medical bills, prescription costs, and insurance payments. Some advanced apps can even link to health insurance portals, helping users understand their benefits, deductibles met, and claims status in real-time. For individuals managing conditions that involve numerous specialist visits or chronic medication, these tools can:
-
Monitor Spending: Keep a running tally of out-of-pocket expenses to ensure you’re on track to meet your deductible or out-of-pocket maximum.
-
Organize Records: Digitally store medical bills, insurance statements, and receipts, which is invaluable for tax purposes (if eligible for medical expense deductions) or disputing billing errors.
-
Set Budgets: Allocate specific funds for anticipated health costs, much like budgeting for groceries or utilities.
-
Identify Trends: Help recognize patterns in healthcare spending, informing future financial planning and potentially identifying areas for cost reduction.
Leveraging these digital financial tools transforms the often-overwhelming task of managing healthcare finances into a more streamlined and transparent process, empowering individuals to make informed decisions about their money and health.
The Broader Economic Impact: Health, Wealth, and Society
The individual’s journey with health markers like RDW and their financial implications extends beyond personal balance sheets to touch upon broader economic and societal well-being. A healthier populace is inherently a more productive and financially secure populace, contributing to national economic stability.
When individuals manage their health proactively, they reduce their reliance on public healthcare systems, contribute more consistently to the workforce, and have more disposable income to save, invest, and spend, stimulating economic growth. Conversely, a society grappling with widespread chronic illness faces immense economic burdens through increased healthcare expenditures, decreased productivity, and strain on social welfare programs. The emphasis on understanding personal health markers like RDW, and integrating this knowledge into personal financial planning, thus contributes to a more resilient individual and, by extension, a more robust economy. It underscores the profound interconnectedness between personal health, individual wealth, and the collective financial strength of society.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.