
In the landscape of modern finance, understanding the mechanisms of wealth generation is essential for both individual investors and corporate entities. Among the various streams of income that populate a financial statement, interest revenue stands as one of the most fundamental yet misunderstood concepts. At its core, interest revenue represents the earnings generated by lending funds to another entity or by allowing a third party to use one’s capital for a specified period. Whether it is a bank providing a mortgage, a corporation holding government bonds, or an individual maintaining a high-yield savings account, interest revenue is the “rent” paid for the use of money.
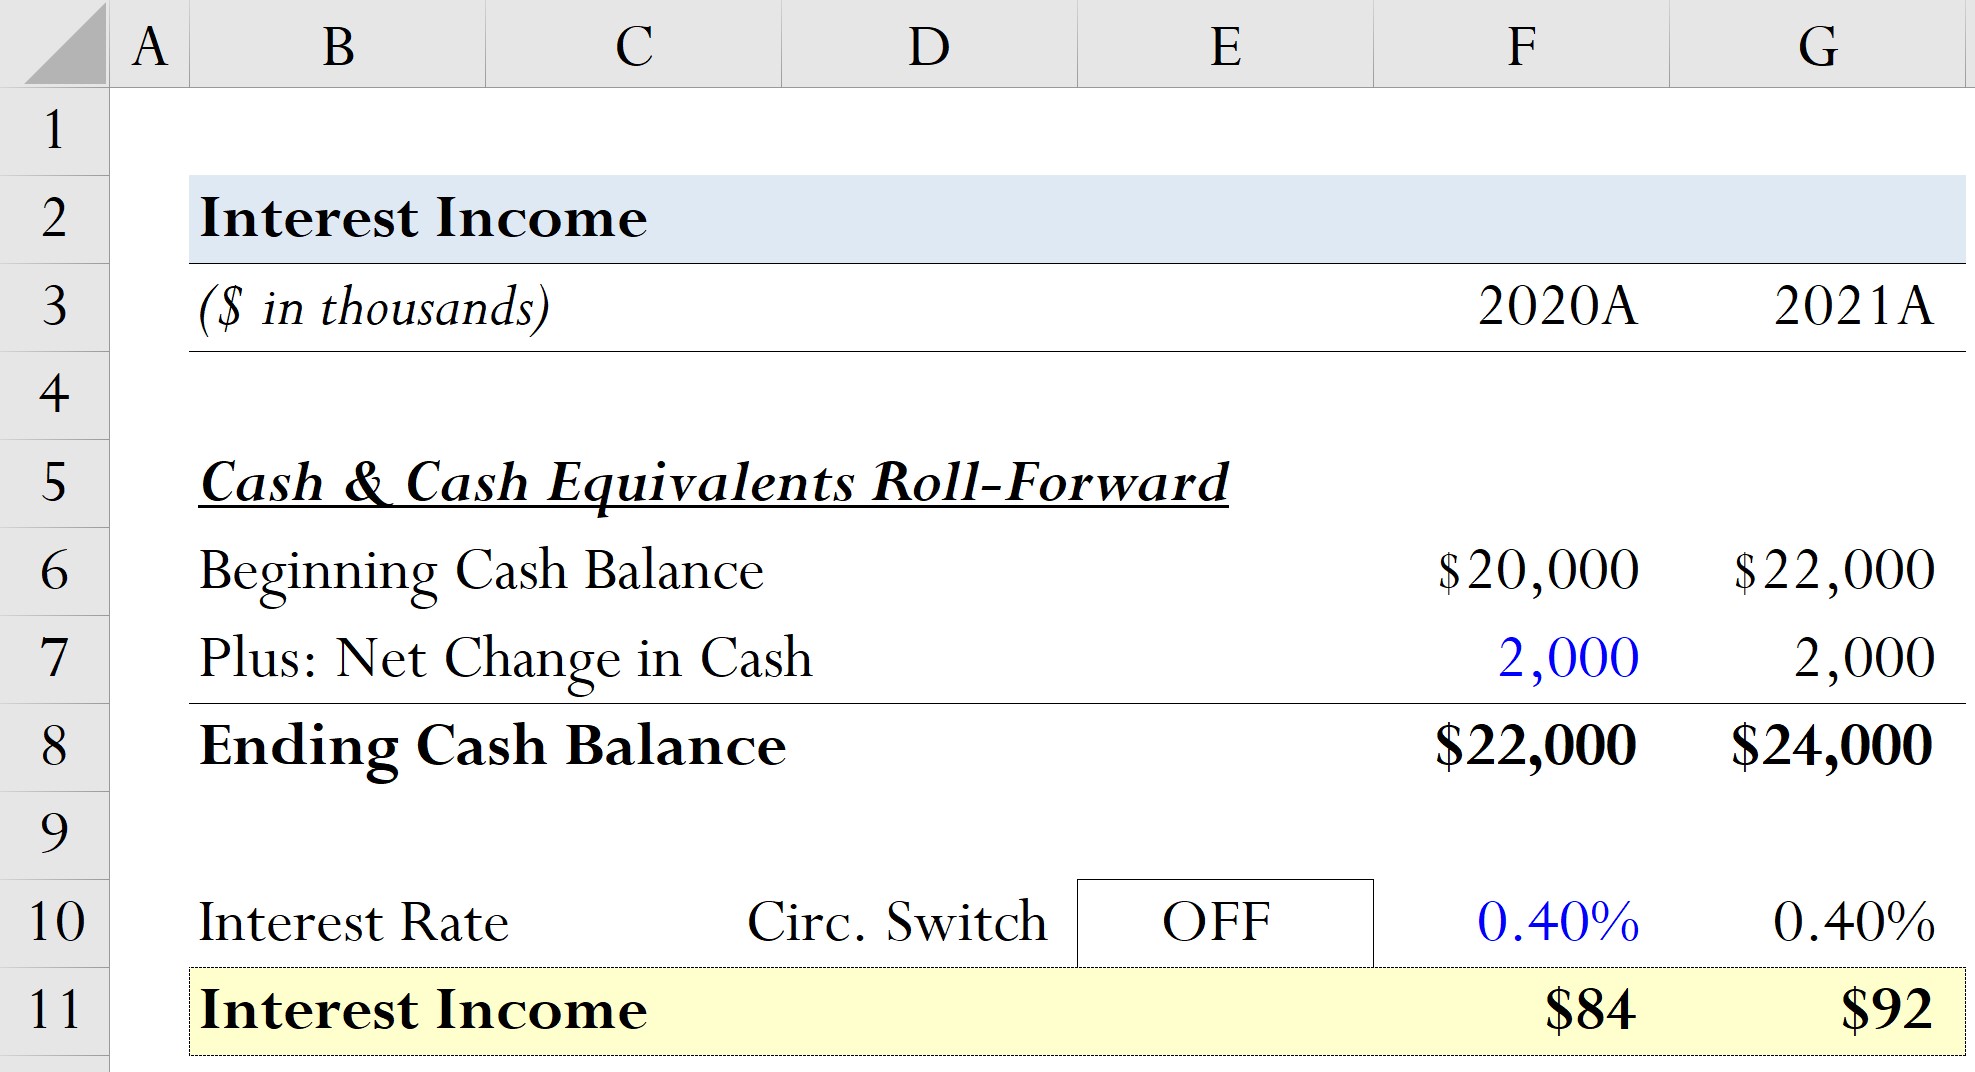
For businesses, interest revenue is typically categorized as non-operating income, distinguishing it from the primary revenue generated through the sale of goods or services. However, for financial institutions, interest revenue is the lifeblood of the business model. Regardless of the entity, mastering the nuances of interest revenue—how it is calculated, recognized, and optimized—is a cornerstone of effective financial management.
The Mechanics of Interest Revenue and Accounting Principles
To fully grasp what interest revenue is, one must look at it through the lens of accounting standards, specifically the Accrual Basis of Accounting. Unlike the cash basis, which records income only when money changes hands, the accrual basis requires that interest revenue be recognized in the period it is earned, regardless of when the payment is actually received.
Accrual vs. Cash Accounting for Interest
In a professional financial environment, interest revenue is recognized as it accrues over time. For example, if a company lends $100,000 to a partner at a 6% annual interest rate, it earns $500 every month. Under accrual accounting, the company must record $500 of interest revenue on its income statement every month, even if the borrower only makes a single payment at the end of the year. This ensures that the financial statements accurately reflect the economic activity of the business during a specific timeframe.
Interest Revenue vs. Interest Income
While the terms are often used interchangeably in casual conversation, a subtle distinction exists in professional reporting. Interest revenue is the broader term used to describe the earnings from the perspective of the lender or the investor. Interest income is the specific line item found on an income statement. In a corporate setting, if the primary business is not lending (such as a retail chain or a software firm), this is listed under “Other Income.” Conversely, for a bank, it is the primary “Operating Revenue.”
The Role of the Principal and the Rate
The volume of interest revenue is governed by three primary variables: the principal (the amount of money lent), the interest rate (the percentage charged), and the time (the duration for which the money is utilized). The interplay between these three factors determines the “yield” of an investment. In a fluctuating economic climate, the interest rate becomes the most volatile variable, often dictated by central bank policies and market demand for credit.
Primary Sources of Interest Revenue
Interest revenue does not emerge from a single source; it is the byproduct of various financial instruments and strategic placements of capital. For both individuals looking to grow their net worth and businesses looking to manage their treasury, identifying these sources is key to a diversified income stream.
Debt Securities and Bonds
One of the most common sources of interest revenue is the purchase of bonds. When an investor buys a corporate or government bond, they are essentially acting as the lender. The issuer of the bond agrees to pay a fixed or floating interest rate—known as the coupon rate—until the bond reaches maturity. For a corporation with excess cash, investing in Treasury bonds can turn stagnant capital into a steady stream of interest revenue with minimal risk.
Interest-Bearing Bank Accounts
On a more accessible level, interest revenue is generated through certificates of deposit (CDs), money market accounts, and high-yield savings accounts. While the rates on these accounts are generally lower than those of riskier investments, they provide liquidity and security. For a business, keeping “operating cash” in an interest-bearing account ensures that every dollar is working, even if it is slated for payroll or rent the following month.
Trade Credit and Late Fees
In the world of B2B (business-to-business) commerce, interest revenue can be generated through trade credit arrangements. If a company sells goods on credit and the customer fails to pay within the agreed-upon timeframe (e.g., Net-30), the seller may charge interest on the outstanding balance. While the primary goal of these charges is to encourage timely payment, they represent a legitimate form of interest revenue that compensates the seller for the “time value” of their missing cash.
Loans and Notes Receivable
For entities that engage in direct lending, such as private equity firms or specialty finance companies, notes receivable are a primary driver of interest revenue. These are formal written promises to pay a specific sum of money at a future date, inclusive of interest. The complexity of these notes can vary, ranging from simple amortized loans to complex convertible notes that may eventually turn into equity.
Calculating Interest Revenue: From Simple to Compound

Understanding how to calculate interest revenue is vital for forecasting cash flows and assessing the viability of an investment. The calculation methods can range from straightforward arithmetic to complex formulas that account for the frequency of compounding.
The Simple Interest Formula
The most basic way to calculate interest revenue is via the simple interest formula:
Interest = Principal × Rate × Time
This formula is typically used for short-term loans or simple debt instruments. If an investor puts $10,000 into a one-year note at a 5% simple interest rate, the interest revenue at the end of the year is $500.
The Power of Compounding
In most modern financial contexts, interest is compounded. Compounding occurs when the interest earned is added back to the principal, and subsequent interest is calculated on that new, larger amount. The formula for compound interest is:
A = P (1 + r/n)^(nt)
Where:
- A = the future value of the investment, including interest
- P = the principal amount
- r = the annual interest rate
- n = the number of times interest is compounded per year
- t = the time the money is invested for
For a financial manager, understanding the frequency of compounding (daily, monthly, or annually) is crucial, as more frequent compounding results in higher total interest revenue over time.
The Effective Interest Method
For sophisticated corporate reporting, especially concerning bonds sold at a discount or a premium, the “Effective Interest Method” is used. This method calculates interest revenue based on the carrying amount of the investment at the beginning of each period, multiplied by the market interest rate at the time the investment was initiated. This ensures a constant rate of return over the life of the investment, providing a more accurate reflection of the economic reality than simple straight-line methods.
Interest Revenue in Financial Reporting and Taxation
How interest revenue appears on financial documents can significantly influence a company’s perceived health and its tax liabilities.
Impact on the Income Statement
As previously noted, for most non-financial businesses, interest revenue is listed below the “Operating Income” line. This is an important distinction for analysts. If a company shows a high net income but a significant portion of that income is derived from interest revenue rather than sales, it may suggest that the core business is struggling while the treasury department is performing well. Investors typically look for sustainable growth in operating revenue, viewing interest revenue as a beneficial “extra” rather than a primary driver.
Tax Implications
Interest revenue is generally taxable as ordinary income. For individuals, this means the interest earned on a savings account or bond is added to their total income and taxed at their marginal tax rate. For corporations, interest revenue increases the taxable income of the firm. However, there are exceptions, such as municipal bonds in the United States, which often provide interest revenue that is exempt from federal (and sometimes state) income taxes. Strategic tax planning often involves balancing high-yield taxable interest revenue with lower-yield tax-exempt revenue.
Strategic Importance in Modern Business Finance
In an era of fluctuating interest rates, interest revenue has moved from a footnote in the back of an annual report to a central component of strategic financial planning.
Liquidity Management and the “Carry Trade”
Large corporations often find themselves sitting on billions of dollars in cash. Effective liquidity management involves ensuring that this cash is not losing value due to inflation. By moving cash into short-term liquid instruments that provide interest revenue, companies can offset inflationary pressures. In some cases, companies engage in a “carry trade” strategy—borrowing money at a low interest rate and investing it in assets that provide a higher interest revenue, pocketing the difference as profit.
Macroeconomic Influence
The level of interest revenue available in the market is heavily influenced by central bank decisions, such as the Federal Reserve’s adjustments to the federal funds rate. When rates rise, interest revenue on new investments increases, making fixed-income assets more attractive. This can lead to a shift in capital away from the stock market and into debt instruments. For a business or an individual investor, staying ahead of these trends is essential for maximizing the revenue-generating potential of their capital.

Risk and Reward
It is important to remember that interest revenue is not “free money.” It is compensation for risk—specifically, credit risk (the risk that the borrower will default) and interest rate risk (the risk that rates will rise, making existing fixed-rate investments less valuable). Higher interest revenue usually indicates a higher level of perceived risk. A corporate bond from a startup may offer 10% interest revenue, while a government bond offers 3%. The difference represents the market’s assessment of the startup’s likelihood of repayment.
Interest revenue remains a vital metric of financial success. Whether it is viewed as a passive income stream for a retiree or a strategic tool for a corporate CFO, the ability to generate and manage interest revenue is a hallmark of financial literacy and institutional strength. By understanding its sources, calculations, and reporting requirements, one can better navigate the complexities of the global financial system.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.