
In the modern landscape of global commodities and consumer packaged goods (CPG), “GF Flour”—shorthand for Gluten-Free flour—has transitioned from a niche dietary requirement to a high-performance asset class. While a chef might view GF flour through the lens of chemistry and texture, an investor or business strategist views it as a disruptive force in the $500 billion global flour and grain market. Understanding what GF flour represents in a financial context requires a deep dive into market valuation, supply chain volatility, and the shifting consumer demographics that drive its premium pricing.

The GF flour market is no longer a peripheral concern for health food stores; it is a central pillar of the modern food-processing industry’s growth strategy. With the global gluten-free market projected to grow at a compound annual growth rate (CAGR) of approximately 9.5% through 2030, the “GF” prefix represents one of the most reliable signals for value-add investment in the grocery sector.
The Market Fundamentals: Why GF Flour is a High-Growth Asset
To define GF flour from a financial perspective, one must look at the valuation of the ecosystem it supports. Unlike traditional wheat flour, which is a low-margin commodity subject to extreme price sensitivity, gluten-free flour blends represent a value-added product that commands a significant “health premium.” This premium is not merely a reflection of production costs; it is a result of strategic market positioning and the monetization of wellness trends.
The Shift from Medical Necessity to Lifestyle Choice
Initially, the demand for GF flour was driven by the medical necessity of Celiac disease patients. However, the financial explosion occurred when the “Health and Wellness” sector successfully marketed gluten-free living to the broader population. This expanded the Total Addressable Market (TAM) by over 500%. For a business, this shift transformed GF flour from a low-volume medical supply into a high-volume lifestyle commodity.
Capital Infusion and M&A Activity
The robust growth of GF flour brands has sparked a wave of Mergers and Acquisitions (M&A). Large-scale conglomerates such as General Mills and Mondelez have aggressively acquired smaller, specialized gluten-free brands to bolster their portfolios. These acquisitions are driven by the need to capture higher margins that traditional wheat-based products can no longer provide in a saturated market.
The Unit Economics of Production and Profit Margins
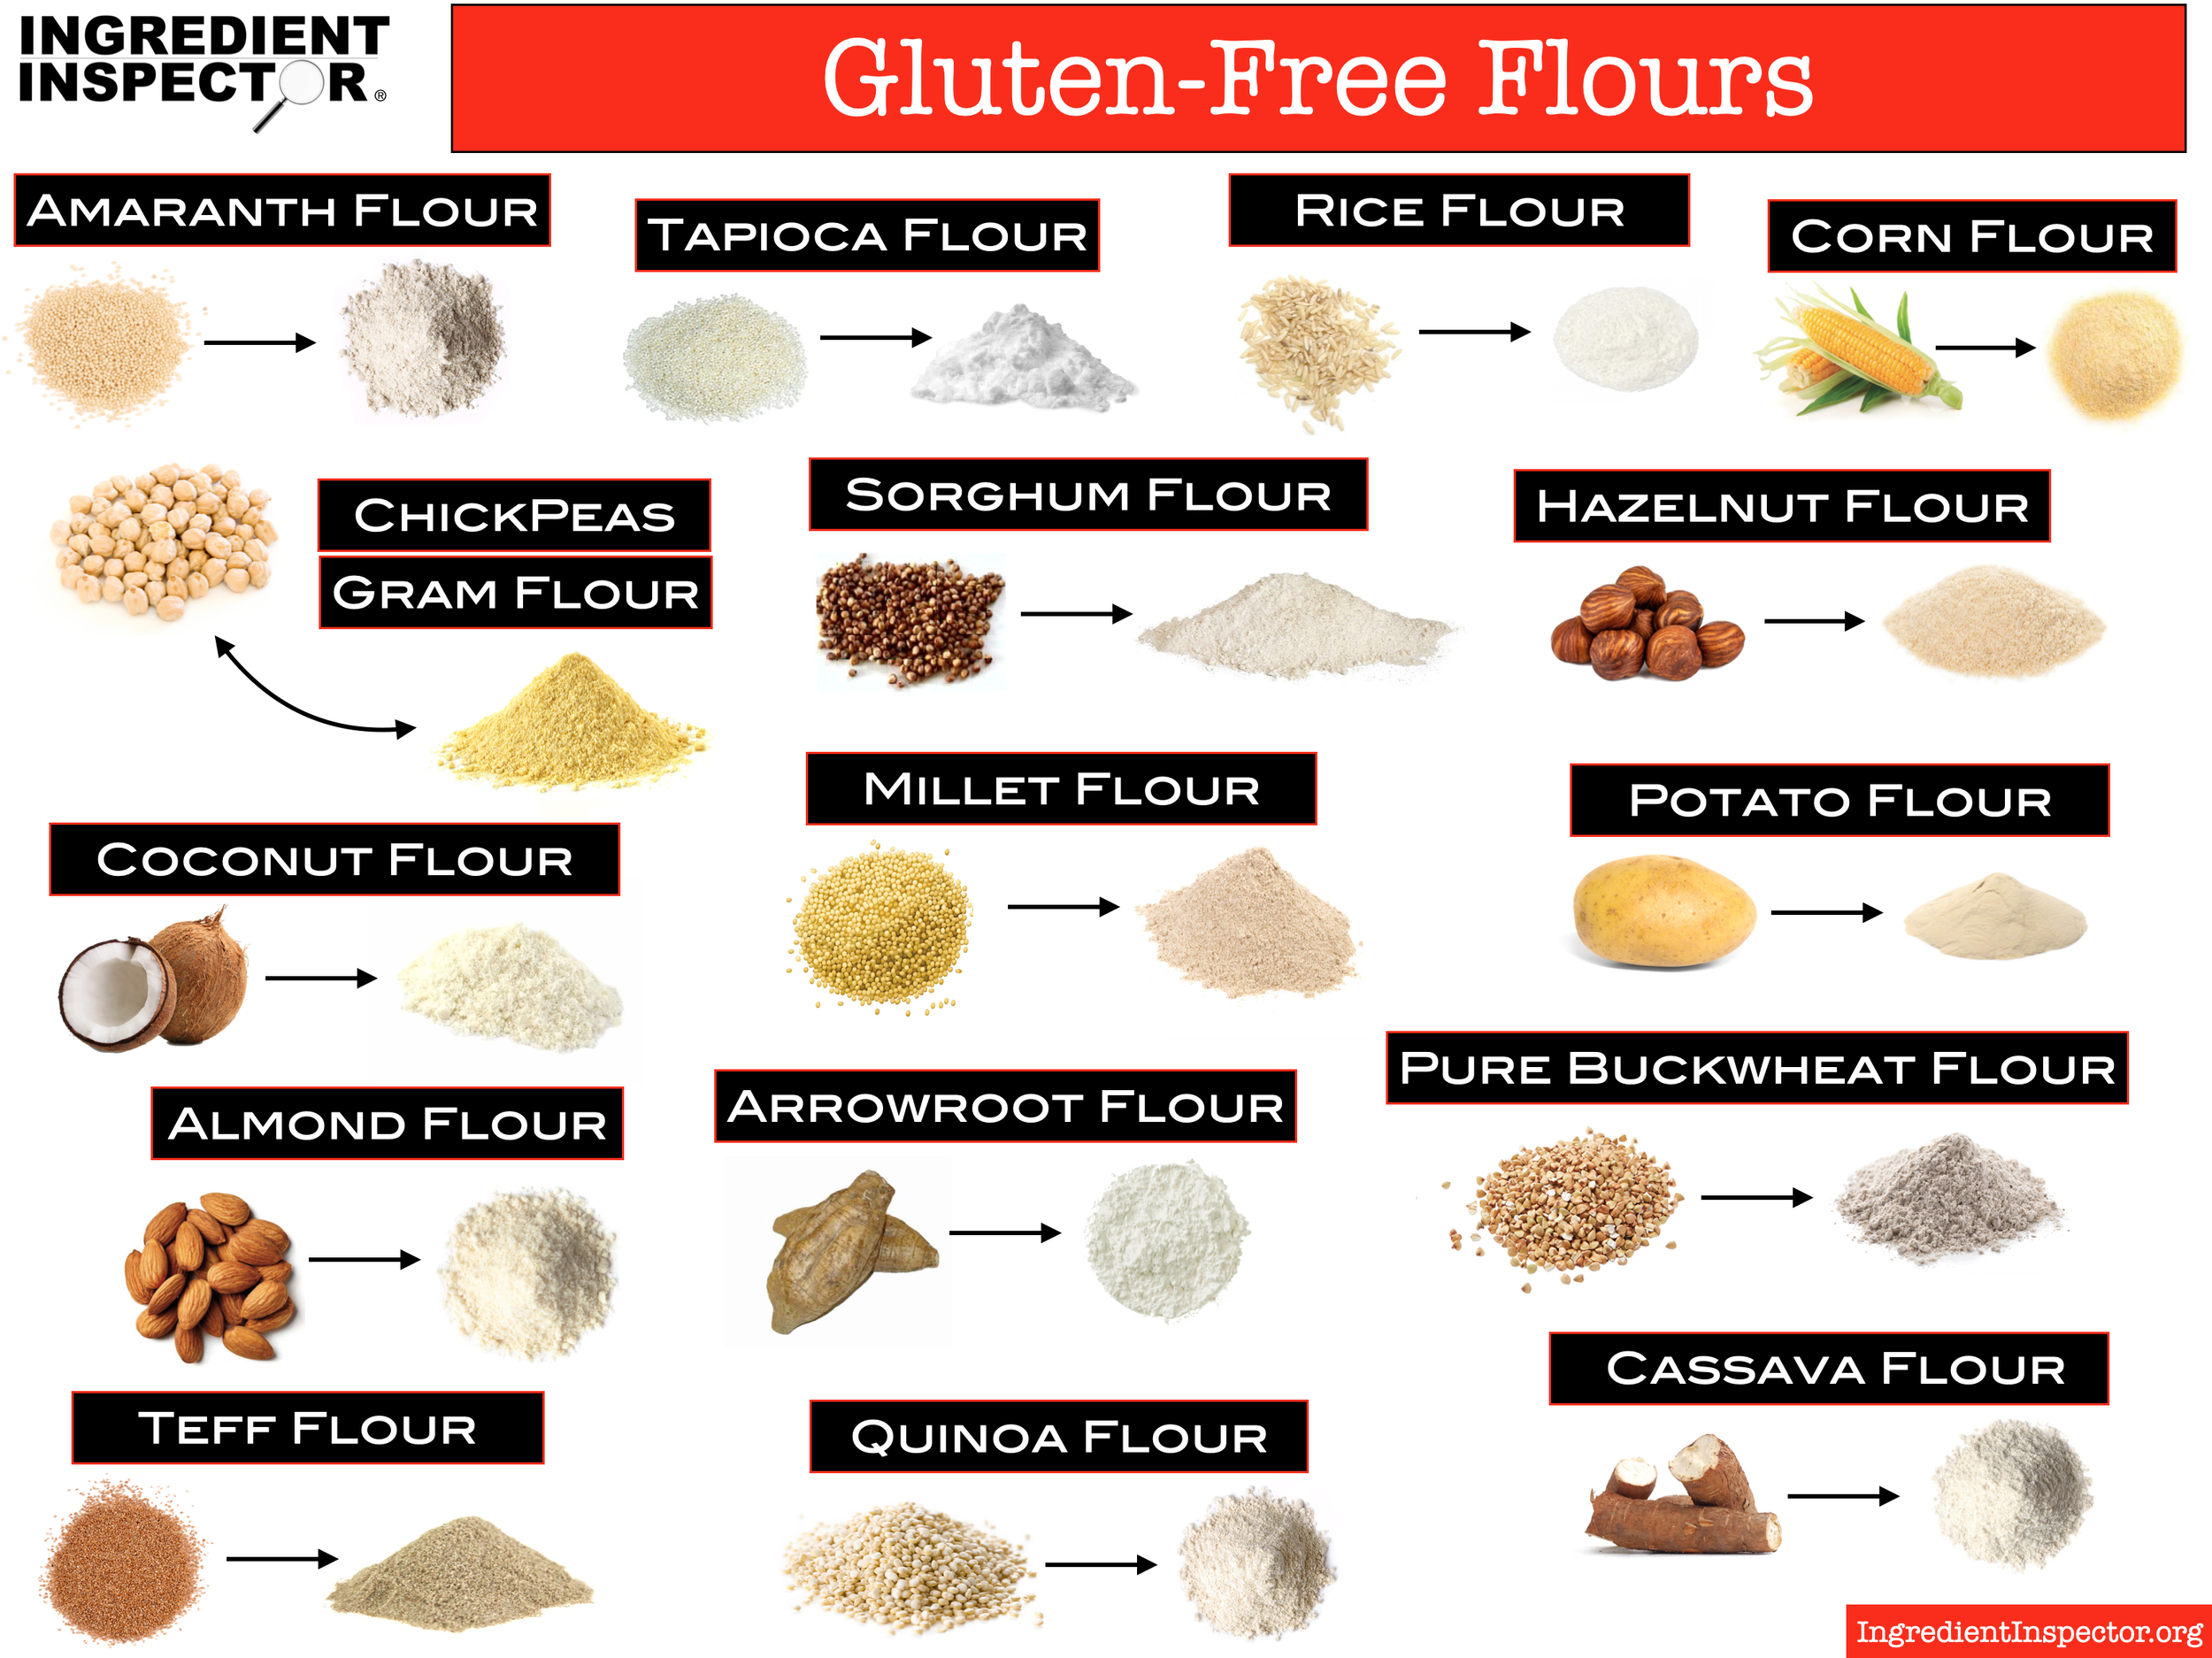
From a business finance perspective, the “what” of GF flour is defined by its complex cost structure. Traditional wheat flour benefits from centuries of industrialized scaling, keeping the Cost of Goods Sold (COGS) remarkably low. GF flour, conversely, is a sophisticated blend of various starches and proteins—such as rice, almond, coconut, sorghum, and tapioca—each with its own independent supply chain and price volatility.
Raw Material Diversification
The diversification of ingredients in GF flour blends acts as both a risk and an opportunity. While it protects manufacturers from a failure in a single crop (like a wheat blight), it exposes them to the price fluctuations of multiple global markets. For instance, a drought in California can spike the price of almond flour, while political instability in Southeast Asia can affect tapioca starch supplies. Managing these diverse inputs requires advanced hedging strategies and sophisticated procurement teams.
The Cost of Purity: Capex and Compliance
One of the most significant financial barriers to entry in the GF flour market is the Capital Expenditure (Capex) required for dedicated facilities. To maintain a “Gluten-Free” certification, which is essential for brand trust and premium pricing, companies must ensure zero cross-contamination. This often requires building entirely separate manufacturing plants or investing in rigorous, high-cost cleaning protocols. These overhead costs are a primary driver of the “Gluten-Free Tax”—the 150% to 400% markup consumers pay compared to traditional flour.
Investment Strategies: From CPG Stocks to AgTech Startups
For those looking to capitalize on the GF flour trend, the investment landscape offers multiple entry points, ranging from conservative equities to high-risk venture capital.
Consumer Packaged Goods (CPG) and Retailers
Investors seeking stable returns often look toward large CPG firms that have successfully integrated GF flour into their core offerings. Additionally, major retailers like Whole Foods (Amazon) and Kroger have seen significant growth in their private-label gluten-free lines. Private labels are particularly lucrative because they allow retailers to capture the manufacturer’s margin while offering a slightly lower price point to the consumer, effectively squeezing branded competitors.
AgTech and Biotechnology Innovation
The next frontier of investment in GF flour is not in the blending, but in the bioengineering of the grains themselves. Venture capital is flowing into AgTech startups focused on developing “ancient grains” with higher yields or engineering wheat varieties that lack the reactive gluten protein. An investment in this space is a bet on the technological disruption of the traditional grain industry, promising to lower the COGS for GF products and move them toward price parity with wheat.
Vertical Integration Opportunities
There is a growing financial case for vertical integration within the GF flour sector. Companies that control the supply chain from the farm (growing sorghum or buckwheat) to the milling facility and finally to the retail shelf are better positioned to weather inflationary pressures. This strategy allows for tighter control over quality and “certified” status, which are the primary drivers of brand equity in this niche.
The “Gluten-Free Tax” and the Retail Margin Strategy
A critical aspect of GF flour’s economic identity is its role in retail strategy. For grocery chains and online marketplaces, GF flour is a “destination product.” Consumers who purchase gluten-free flour tend to have higher household incomes and larger total basket sizes.
Price Elasticity of Demand
GF flour exhibits lower price elasticity than many other food staples. Because it is often viewed as a health requirement rather than a luxury, consumers are less likely to stop purchasing it when prices rise due to inflation. This allows manufacturers and retailers to pass on increased costs to the consumer more easily than they could with traditional bread or pasta, protecting the bottom line during economic downturns.
Strategic Loss Leaders
In some instances, retailers may use GF flour as a “loss leader” to attract high-value shoppers. By pricing a popular GF flour blend competitively, they draw in the health-conscious demographic, which then purchases high-margin supplements, organic produce, and premium meats. Understanding this interplay is essential for any financial analysis of the retail sector.
Future Financial Forecasts: The Next Decade of GF Flour
The future of GF flour as a financial instrument looks promising, but it is not without its risks. As the market matures, we can expect several key shifts in the economic landscape.
Globalization of Demand
While the North American and European markets are currently the primary drivers of GF flour revenue, the Asia-Pacific region is emerging as a massive growth opportunity. As Western dietary habits influence developing economies and diagnostic capabilities for Celiac disease improve globally, the demand for GF flour is expected to skyrocket in previously untapped markets.
The Impact of Sustainability and ESG
Environmental, Social, and Governance (ESG) factors are becoming increasingly important to investors. GF flour production, particularly those blends using almond or rice, faces scrutiny over water usage and carbon footprints. Companies that can innovate sustainable, low-impact GF flour sources—such as perennial grains or upcycled ingredients—will likely see a “valuation lift” as ESG-focused funds allocate more capital to sustainable food systems.
Regulatory Risks and Labeling Laws
Investors must also monitor the regulatory environment. Changes in FDA or European Food Safety Authority (EFSA) labeling requirements can have immediate impacts on stock prices. Any tightening of “gluten-free” definitions could force expensive reformulations or lead to costly recalls, representing a significant “black swan” risk for the industry.
In conclusion, GF flour is far more than a dietary substitute; it is a sophisticated economic engine. From the high-stakes world of AgTech innovation to the strategic shelf-space battles in global retail, GF flour represents a convergence of health trends and hard-nosed business finance. For the savvy investor or brand strategist, understanding the nuances of this market—the high margins, the supply chain complexities, and the loyal consumer base—is essential for navigating the future of the global food economy. GF flour has proven that it is not a passing fad, but a permanent, high-value fixture in the financial world of consumer goods.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.