
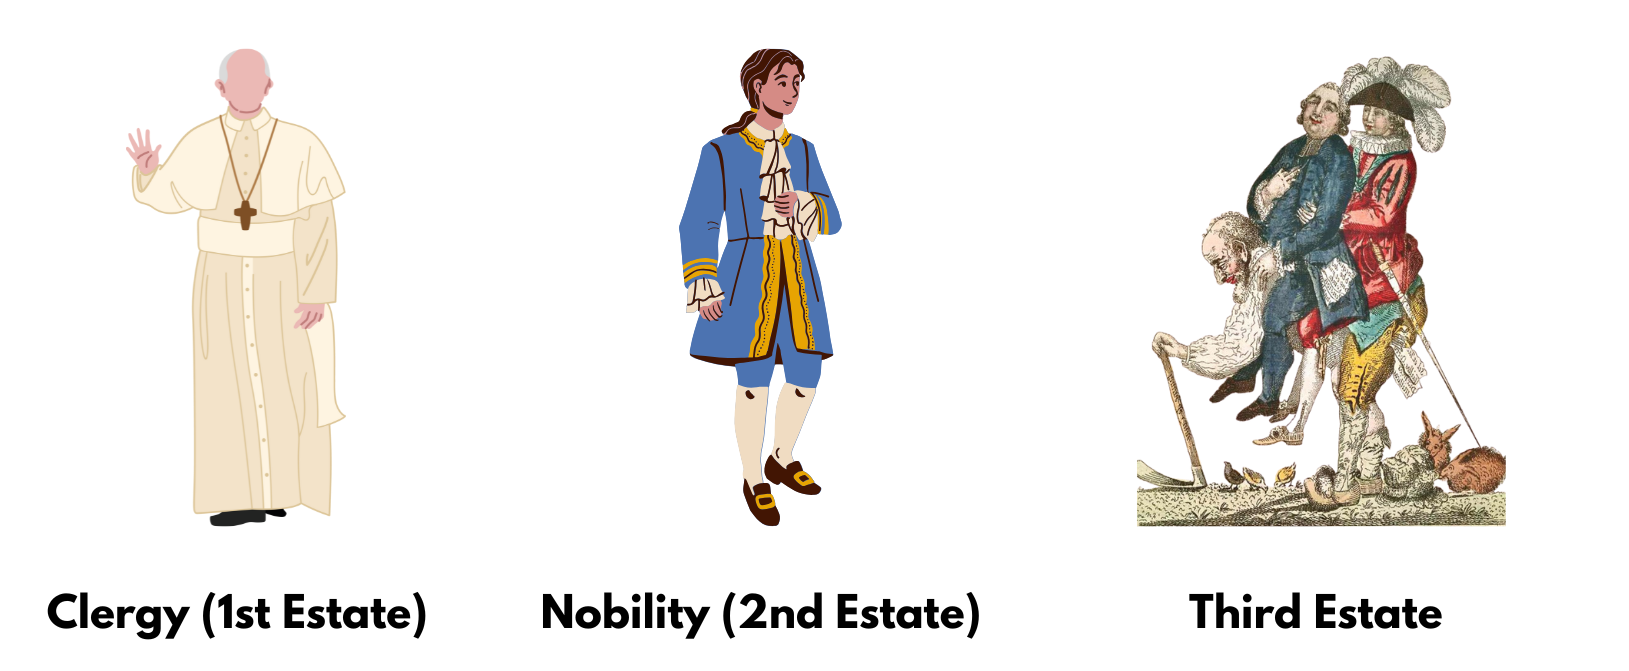
In the lexicon of modern finance and investment, the term “First Estate” has transcended its historical roots to represent the ultimate foundation of a robust financial portfolio. Historically, the First Estate referred to the clergy in a tripartite social hierarchy, representing the moral and structural bedrock of society. In a contemporary economic context, however, the First Estate represents the primary, non-negotiable assets that form the base of personal wealth. It is the cornerstone of financial independence—the tier of investments and capital that provides both security and the leverage required to scale into more speculative ventures.

Understanding what constitutes your First Estate is the first step toward moving from a cycle of earned income to a life sustained by passive growth and asset appreciation. Whether you are an aspiring entrepreneur, a seasoned investor, or someone looking to optimize their personal finances, defining and securing your First Estate is the most critical strategic move you can make.
The Evolution of the First Estate in Modern Finance
To master one’s finances, one must first recognize that not all income is created equal. In the modern money niche, the First Estate is defined as the foundational asset class that produces consistent value regardless of market volatility. This is often synonymous with prime real estate, blue-chip holdings, and high-liquidity business interests. Unlike the “Third Estate” of common labor or the “Second Estate” of corporate management, the First Estate is characterized by ownership and control.
The Shift from Labor to Asset Ownership
For decades, the standard path to financial stability was through the “Second Estate”—rising through the ranks of corporate identity and securing a high salary. However, inflation, shifting job markets, and the devaluation of traditional currencies have rendered the salary-only model obsolete. The modern First Estate focuses on the transition from selling time to owning systems. By prioritizing the acquisition of assets that appreciate over time, an individual builds a defensive perimeter around their wealth.
Real Estate: The Traditional Pillar
Real estate remains the most common manifestation of the First Estate. It is a tangible asset with intrinsic value. Unlike digital currencies or speculative stocks, physical property offers a dual benefit: utility (shelter or commercial space) and financial yield (rental income and appreciation). When we speak of a “First Estate” in a financial plan, we are often referring to the primary properties that anchor a portfolio, providing the tax advantages and equity necessary to fund future growth.
Strategic Asset Allocation: Why the First Estate Matters
A financial strategy without a First Estate is a house built on sand. High-risk investments, such as cryptocurrency or venture capital, can lead to explosive growth, but they lack the stability required to survive economic downturns. The First Estate acts as the stabilizer. It is the portion of your net worth that allows you to sleep at night, knowing that even if the market fluctuates, your core wealth remains intact.
Risk Mitigation and Inflation Hedging
The primary function of the First Estate is protection. Inflation is the silent predator of personal finance, eroding the purchasing power of cash sitting in traditional savings accounts. First Estate assets—particularly real estate and commodities—historically track with or exceed inflation rates. By locking capital into these vehicles, you ensure that your wealth retains its value relative to the cost of living. This creates a “floor” for your lifestyle that is shielded from the whims of central bank policies.
The Power of Leverage and Equity
One of the most profound benefits of establishing a First Estate is the ability to use leverage. Banks and financial institutions are far more willing to lend against tangible assets than speculative ones. By owning a piece of the First Estate, you gain access to credit at lower interest rates. This equity can be harvested to reinvest in side hustles, business expansions, or further asset acquisition. In this way, the First Estate becomes an engine for compounding wealth, turning a single solid investment into a multi-stream income machine.
Identifying First Estate Opportunities in the Digital Age
While physical land remains a primary component, the definition of the First Estate is expanding to include digital infrastructure and scalable business systems. In the current economy, an “estate” can also be a portfolio of high-performing digital assets that generate recurring revenue with minimal overhead.

PropTech and Fractional Ownership
The barrier to entry for the First Estate has historically been high, requiring significant down payments and creditworthiness. However, financial technology (FinTech) has democratized access. Through PropTech platforms, investors can now engage in fractional ownership of institutional-grade real estate. This allows individuals to build their First Estate incrementally, diversifying across various geographical locations and property types without the burden of direct property management.
Real Estate Investment Trusts (REITs)
For those who prefer a hands-off approach to the money niche, REITs offer a way to invest in the First Estate via the stock market. A REIT is a company that owns, operates, or finances income-producing real estate. By investing in these trusts, you receive a portion of the income produced through dividends. This is a powerful financial tool for those looking to build a foundation of passive income while maintaining the liquidity to pivot their strategy as new opportunities arise.
Digital Real Estate and IP
In the realm of online income, “First Estate” can also refer to intellectual property (IP) and established digital platforms. A high-traffic website, a proprietary software-as-a-service (SaaS) product, or a patented invention represents a modern form of estate. These assets provide the same recurring revenue and appreciation potential as physical property, often with significantly higher profit margins.
Building Your First Estate: A Roadmap to Financial Independence
Building a First Estate does not happen by accident; it requires a disciplined approach to personal finance and a strategic long-term vision. It involves moving from the “Consumer” mindset to the “Owner” mindset.
Step 1: Capital Accumulation Through Side Hustles
The first step in building an estate is generating the surplus capital required for investment. In today’s economy, a single source of income is rarely enough to fund the acquisition of significant assets. This is where the world of side hustles and online income becomes vital. By leveraging skills in consulting, digital marketing, or e-commerce, you can create an “accumulation engine” that feeds directly into your First Estate fund.
Step 2: Debt Optimization and Credit Mastery
You cannot build an estate while being weighed down by high-interest consumer debt. Mastery of the First Estate requires an understanding of the difference between “bad debt” (depreciating assets) and “good debt” (leveraged investments). Professional investors use debt as a tool to accelerate their growth, but this is only possible once the foundation of personal financial discipline is established.
Step 3: Consistent Reinvestment and Compounding
The hallmark of the First Estate is its ability to grow over time. The most successful wealth builders do not spend the dividends or rental income generated by their primary assets. Instead, they reinvest those earnings back into the estate. This creates a compounding effect where the asset itself funds the purchase of more assets. Over a decade or more, this cycle transforms a modest portfolio into a legacy-defining fortune.
The First Estate as a Legacy and Financial Tool
Ultimately, the First Estate is about more than just money; it is about sovereignty and the ability to dictate the terms of your own life. When you own your foundation, you are no longer at the mercy of employers, landlords, or volatile economic shifts. You have created a “private economy” that supports your goals and values.
Tax Advantages and Wealth Preservation
In many jurisdictions, the First Estate—specifically real estate—enjoys significant tax protections. From depreciation write-offs to 1031 exchanges, the legal framework of modern finance is designed to reward those who hold foundational assets. Understanding these financial tools is essential for any investor looking to minimize their tax liability and maximize their net returns.
The Generational Impact
The First Estate is the vehicle through which generational wealth is passed down. While cash can be spent and businesses can fail, a well-managed estate of tangible and high-value assets provides a platform for future generations to build upon. By establishing your First Estate today, you are not just securing your own retirement; you are creating a financial legacy that can provide security and opportunity for your descendants.
In conclusion, the First Estate represents the pinnacle of strategic financial planning. It is the bedrock upon which all other wealth is built. By identifying the right assets, utilizing modern financial tools, and maintaining a disciplined approach to reinvestment, anyone can move toward owning their First Estate. It is the ultimate transition from the uncertainty of the labor market to the enduring power of asset ownership. Focus on your foundation, secure your primary assets, and let the First Estate be the engine that drives your long-term financial freedom.
aViewFromTheCave is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.