
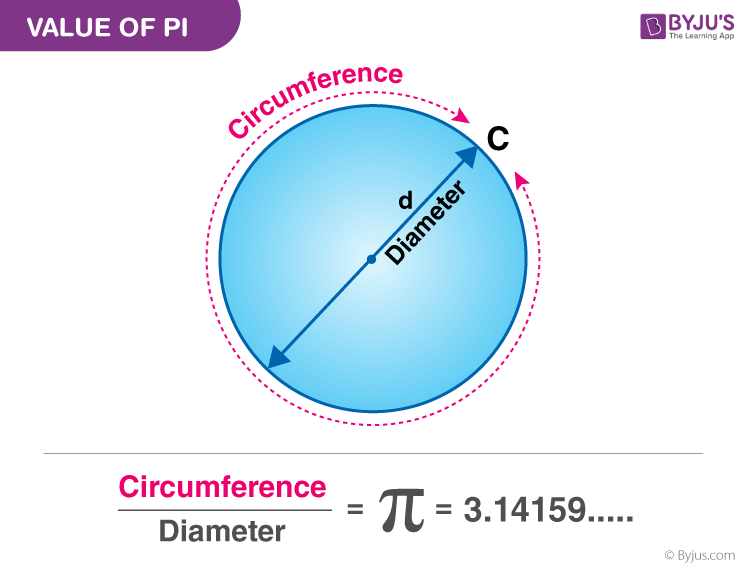
In the realm of personal finance and wealth management, consistency is the ultimate currency. Just as the mathematical constant pi (π)—approximately 3.14159—serves as the foundational ratio for understanding the geometry of a circle, there exists a “mathematical constant” for financial independence. While pi represents the relationship between a circle’s circumference and its diameter, in the world of money, the constant that dictates your financial trajectory is the relationship between your savings rate, your rate of return, and your time horizon. To build a robust portfolio, one must treat these variables with the same precision mathematicians apply to the irrational number that defines circular perfection.
The Geometry of Compound Interest
The most significant constant in your financial life is not a fixed number, but a mechanism: compound interest. Often called the “eighth wonder of the world,” compounding functions similarly to the infinite nature of pi. Because pi is irrational and non-repeating, it requires infinite precision to fully map a circle. Similarly, compound interest requires the precision of time to fully map the growth of an investment portfolio.
The Power of the Constant Savings Rate
Much like pi remains constant regardless of the size of the circle, your savings rate must remain constant regardless of your income level. Many individuals fall into the trap of “lifestyle creep,” where their spending scales in direct proportion to their earnings. This essentially “shrinks the diameter” of your financial potential. To achieve a geometry of growth, you must ensure that your savings rate remains a fixed, non-negotiable ratio of your gross income. Whether you earn $50,000 or $500,000, maintaining a consistent savings percentage is the only way to ensure that your financial circumference—your total net worth—expands at an accelerating rate.
Time as the Infinite Variable
In the formula for a circle, the radius determines the reach. In finance, time is your radius. Because the interest earned on your interest grows exponentially, every additional year you leave your capital untouched adds a disproportionate amount of volume to your terminal wealth. If pi is the bridge between a line and a curve, time is the bridge between a standard salary and true generational wealth. The mistake most investors make is attempting to “shorten” the circle by seeking high-risk, high-return ventures, rather than trusting the mathematical constant of consistent, long-term compounding.
Defining Your Financial Constant: The Asset Allocation Ratio
If pi is the ratio of circumference to diameter, your asset allocation is the ratio of risk to reward. Achieving financial balance requires a rigorous approach to diversification. Just as pi is derived from an objective truth of physics, your investment strategy must be derived from an objective assessment of your risk tolerance and your specific financial goals.
The Role of Index Funds and ETFs
For the majority of investors, the “constant” that delivers the most reliable performance is the low-cost index fund. These instruments represent the closest thing to a mathematical certainty in the stock market. By owning the entire market, you remove the “variable” of human error—specifically the errors of stock picking and market timing. When you align your portfolio with the total market, you are essentially adopting a strategy of efficiency that mirrors the mathematical elegance of pi. You stop fighting the market and start mirroring its inherent, long-term growth.
Rebalancing as the Equilibrium Mechanism
A circle maintains its shape because every point on the circumference is equidistant from the center. In finance, your portfolio will naturally drift. If a bull market causes your equity allocation to swell from 70% to 85%, your risk profile has fundamentally changed, just as a circle would warp if one side expanded while the other remained static. Periodic rebalancing—the act of selling high-performing assets to buy underperforming ones—is the financial equivalent of maintaining the perfect circular ratio. It forces you to maintain your “constant” risk-to-reward profile, regardless of the chaotic external environment.
The Psychology of Financial Constants
While the math of finance is static, the psychology of the investor is fluid. The greatest challenge to your financial “pi”—the absolute, unchanging truth of your plan—is the emotional reaction to market volatility. When the market dips, the temptation is to abandon the strategy. However, the most successful investors treat their financial plans with the same reverence mathematicians treat pi: as an unalterable, structural truth that does not change simply because the market is having a bad day.
Avoiding the Variable of Fear
Fear is the most expensive variable in finance. When investors allow emotion to dictate their movements, they break the mathematical consistency of their portfolio. Just as you cannot change the value of pi to make a circle easier to draw, you cannot change the rules of market returns to make your journey to wealth faster. The constant remains the constant: you must save, you must invest, and you must wait. By removing emotion from the equation, you treat your wealth accumulation like a mathematical proof—reliable, predictable, and ultimately successful.
Establishing Financial Non-Negotiables
To ensure your financial life is as consistent as pi, you must establish non-negotiables. These are the “constants” of your personal economy. For instance, the automatic transfer of a set percentage of your paycheck into a tax-advantaged account is a structural constant. By automating your financial behavior, you remove the need for willpower. You are effectively hard-coding the “pi” of your financial success into your daily routine, ensuring that your wealth grows in the background, untouched by the noise of the headlines or the lure of impulsive consumption.
The Convergence of Wealth and Discipline
True financial mastery is not about finding the “secret” investment that will yield infinite returns; it is about respecting the constraints of the system. Pi is an irrational number, meaning it cannot be expressed as a simple fraction, yet it is the key to everything round in the universe. Wealth is similar—it often feels elusive and irrational, especially during periods of economic instability. However, when you adhere to the fundamental principles of compounding, low-cost diversification, and long-term discipline, you create a structure that is perfectly balanced.
Measuring Success Beyond the Balance Sheet
Finally, remember that the goal of financial planning is to create the “circle” of your life—the ability to focus on what matters most. Whether that is family, philanthropy, or personal pursuits, money is merely the resource that allows the shape to hold. When you have mastered your financial constants, you no longer worry about the day-to-day fluctuations of your net worth. You understand that your financial plan is a geometric certainty, a well-defined space where you can operate with peace of mind.
The Final Equation
If you were to sum up your financial life in a single expression, it would be: (Savings Rate × Time) + Compounding = Financial Independence. This is your pi. It is a constant that, when applied with discipline and an eye for long-term growth, yields a result that is both infinite in its possibilities and precise in its execution. Do not look for shortcuts or “new math” that promises to outperform the fundamental laws of capital accumulation. Embrace the constants of finance, nurture your savings rate, and allow the mathematical engine of compound interest to do the heavy lifting. In the world of money, as in the world of mathematics, the truth is found in the constants. Respect the math, stay the course, and watch as your financial circle becomes stronger, larger, and more secure with every passing year.